
Why Should Businesses Conduct Stocktakes?
A stocktake is not merely a process of counting goods. It is an important control procedure that helps ensure the company’s accounting records agree with the inventory physically held and that its operational data can be relied upon. Regular stocktakes can help businesses: A properly conducted stocktake helps a business understand the condition and quantity […]
Receivables Turnover Ratio: Why Cash Collection Matters
A high receivables turnover ratio generally indicates that customers are paying more quickly, helping the business maintain stronger cash flow. A low ratio may indicate: However, the ratio should not be analysed in isolation. It should be compared with the company’s performance in prior years and with relevant industry benchmarks. Sales may look impressive, but […]
Gross Margin: Formula, Example and Interpretation
Gross Margin is a key indicator of how efficiently a company produces and prices its products or services. Formula Gross Margin = (Gross Profit ÷ Revenue) × 100% Where: Gross Profit = Revenue − Cost of Goods Sold (COGS) Quick Example Assume: Therefore: Gross Margin = (RM300,000 ÷ RM1,000,000) × 100% = 30% This means […]
Technical Accountants in Malaysia: Bridging Accounting Standards, Systems and Business Decisions
Technical Accountants have become increasingly sought after in Malaysia in recent years. However, one point should first be clarified: “Technical Accountant” is not a formal position defined by MIA, ACCA or the Companies Act 2016. It is an industry term commonly used by Big Four firms, listed companies and multinational corporations to describe a particular […]
ROIC: Measuring the Return on Invested Capital
Let’s talk about ROIC, or Return on Invested Capital. Imagine that you are a typical Malaysian uncle who invests RM10,000 to open a small mamak stall near an office. After paying for staff, gas, Maggi, teh tarik and other operating expenses, the stall generates a net profit of RM1,500 a month. In this simplified example, […]
Understanding the Five Elements of Financial Statements
Accounting is not merely about recording numbers in a ledger. More importantly, it is about understanding the financial story behind a business. The five fundamental elements of financial statements are: These five concepts form the foundation for reading and understanding financial statements. Whether an entity applies MFRS or MPERS 2025, understanding these elements is essential […]
IFRS 9: How to Classify Financial Assets
Correctly classifying a financial asset under IFRS 9 is essential because its subsequent measurement, presentation and accounting entries depend on the classification. For debt financial assets, classification is determined primarily by two core tests: 1. The Business Model Test The Business Model Test asks: Why does the entity hold the financial asset? This test applies […]
MPERS 2025: Key Changes and How Private Entities Can Prepare for 2027
The Malaysian Accounting Standards Board (MASB) has issued a revised Malaysian Private Entities Reporting Standard (MPERS), aligned with the third edition of the IFRS for SMEs Accounting Standard issued in 2025. The revised MPERS applies to annual periods beginning on or after 1 January 2027, with early adoption permitted. For private entities, this is more […]
Capital Allowance for Business Fit-Outs: The Functional Test Following PETRONAS Dagangan
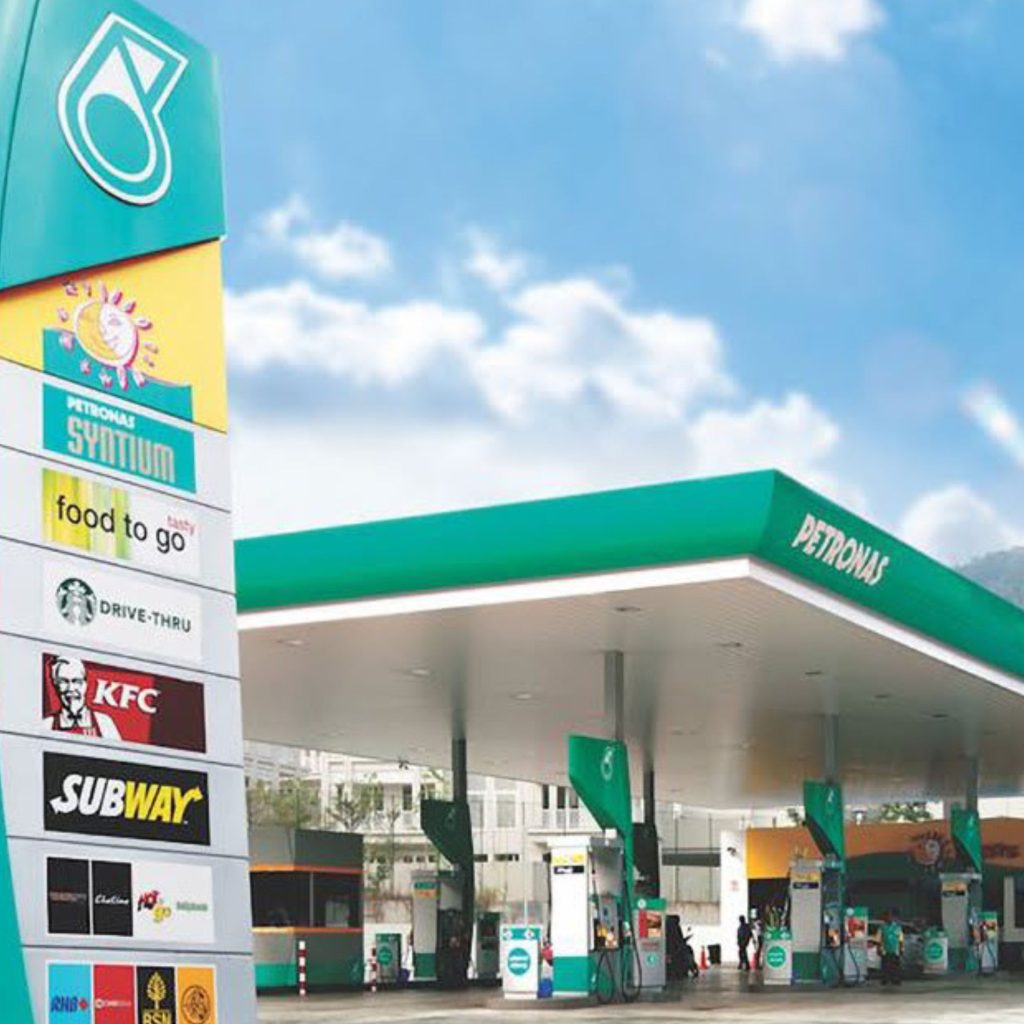
The most interesting aspect of PETRONAS Dagangan Berhad v. KPHDN [2026] MLRHU 213 is not simply that a petrol station canopy may qualify for capital allowance. More importantly, the case brings an old question back into focus: Tax law does not ask, “Does this asset look like part of the premises?”It asks, “What does this […]
Dormant Companies Still Have Accounting and Statutory Obligations in Malaysia
“My company was incorporated six months ago but has had no transactions. Do I still need to keep accounting records?” Yes. Under the Companies Act 2016, a company has statutory obligations to maintain accounting records for as long as it remains incorporated and in existence. No Revenue Does Not Mean No Obligations A company with […]