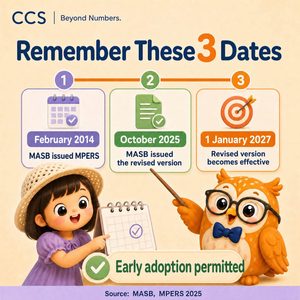
The Malaysian Accounting Standards Board (MASB) has issued a revised Malaysian Private Entities Reporting Standard (MPERS), aligned with the third edition of the IFRS for SMEs Accounting Standard issued in 2025.
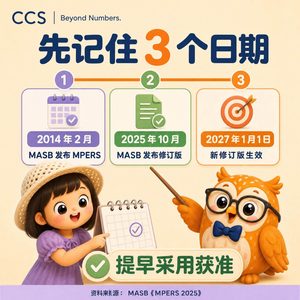
The revised MPERS applies to annual periods beginning on or after 1 January 2027, with early adoption permitted.
For private entities, this is more than a future accounting update. It is an opportunity to review accounting policies, reporting processes, financial systems and disclosure practices before the changes take effect.
Key Areas to Watch
The main areas include:
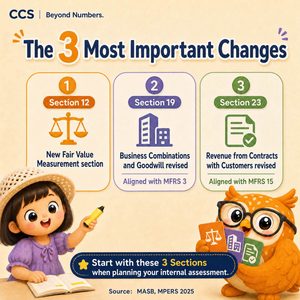
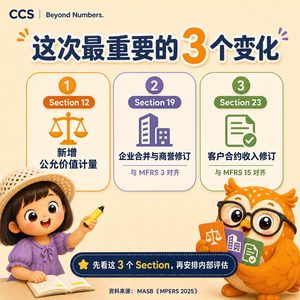
- Section 12: A new section on Fair Value Measurement;
- Section 19: Revised requirements for Business Combinations and Goodwill, aligned with MFRS 3;
- Section 23: Revised requirements for Revenue from Contracts with Customers, aligned with MFRS 15;
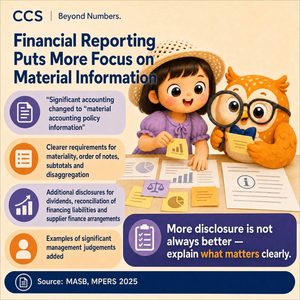
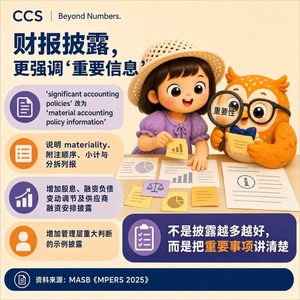
- Financial reporting and disclosures: Greater focus on material accounting policy information, materiality, note disclosures, management judgements and financing-related information;
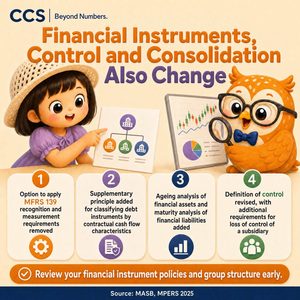
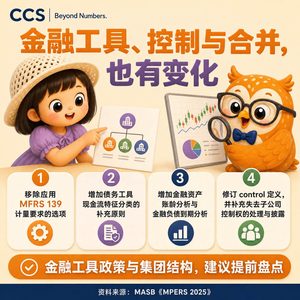
- Financial instruments and group matters: Updates affecting debt instrument classification, financial asset ageing analysis, financial liability maturity analysis, control and loss of control of a subsidiary; and
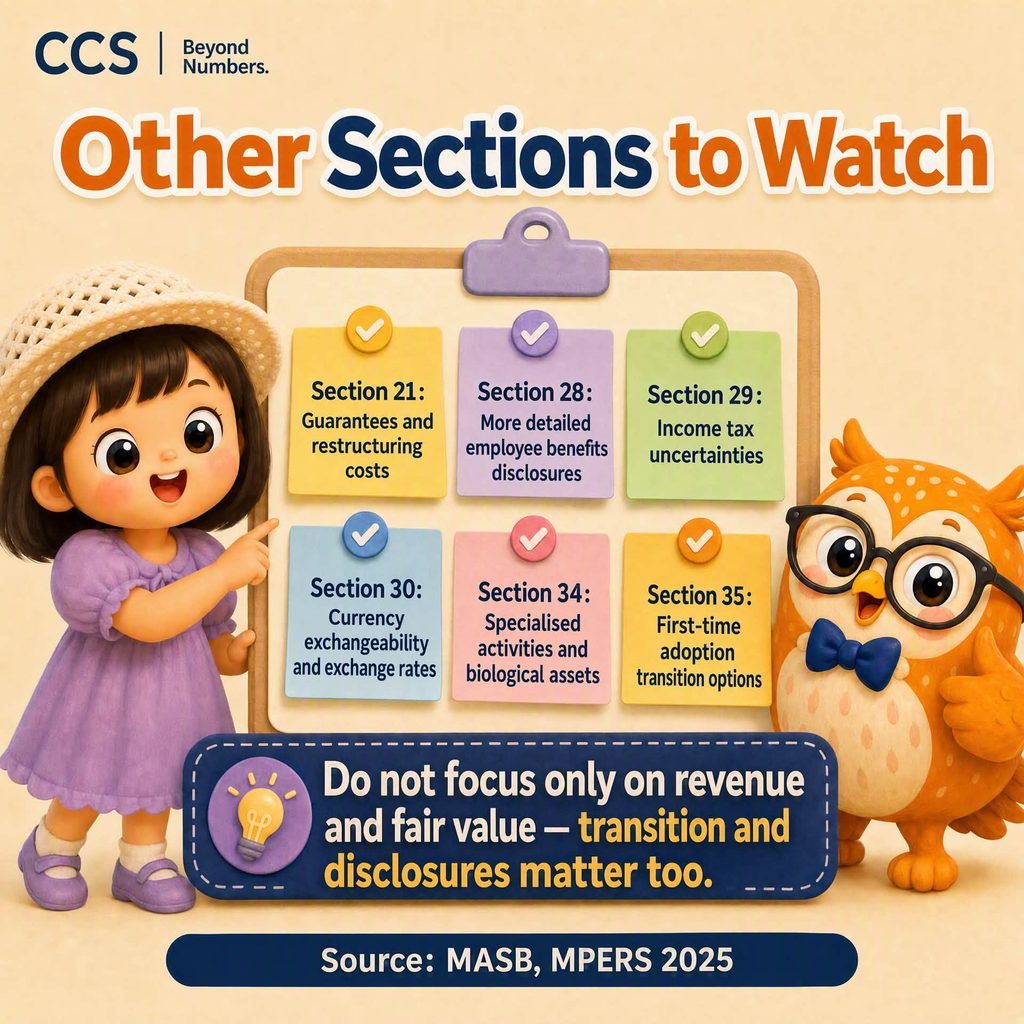
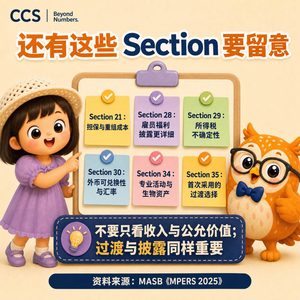
- Other areas: Employee benefits, income tax uncertainties, foreign currency transactions, specialised activities and transition options for first-time adoption.
What Can Businesses Do Now?
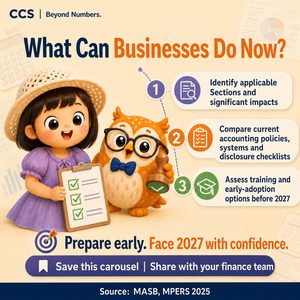
Private entities can begin preparing by:
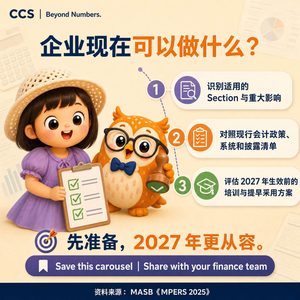
- Identifying the MPERS Sections relevant to their business and assessing the potential impact;
- Comparing their current accounting policies, financial systems and disclosure checklists with the revised requirements; and
- Planning the necessary training, process changes, system updates and early-adoption assessment before 2027.
Early preparation can help businesses identify potential gaps, improve the quality of their financial reporting and approach the 2027 changes with greater confidence.
Prepare early. Face 2027 with confidence.
This article is a general information summary based on the MASB MPERS 2025 publication. It does not replace the full Standard and does not constitute accounting, auditing or other professional advice.
Businesses should assess the requirements based on their individual facts and circumstances and seek professional advice where appropriate.
CCS | Beyond Numbers
MPERS 2025 修订了什么?私人企业现在应该准备什么?
马来西亚会计准则委员会(MASB)已经发布修订版 Malaysian Private Entities Reporting Standard(MPERS)。修订内容与 2025 年发布的第三版 IFRS for SMEs Accounting Standard 对齐。
修订版 MPERS 适用于私人实体,并将于 2027 年 1 月 1 日或之后开始的年度期间生效。企业也可以选择提早采用。
这次修订不只是文字上的调整。多个会计处理、财务报告及披露领域都会受到影响,企业应在新要求生效前,提前检讨现有的会计政策、报告流程、财务系统及披露做法。
企业需要关注的主要领域
重点包括:
- **Section 12:**新增公允价值计量(Fair Value Measurement)章节;
- **Section 19:**修订企业合并与商誉(Business Combinations and Goodwill)的要求,并与 MFRS 3 对齐;
- **Section 23:**修订客户合约收入(Revenue from Contracts with Customers)的要求,并与 MFRS 15 对齐;
- **财务报告与披露:**更加关注重要会计政策信息、重要性、附注披露、管理层判断及融资相关信息;
- **金融工具及集团事项:**更新债务工具分类、金融资产账龄分析、金融负债到期分析、对附属公司的控制及失去控制权等相关要求;以及
- **其他领域:**雇员福利、所得税不确定性、外币交易、特殊活动及首次采用时的过渡安排。
企业现在可以开始做什么?
私人企业可以从以下几个方面开始准备:
- 识别与自身业务相关的 MPERS Sections,并评估可能受到的影响;
- 将现有会计政策、财务系统及披露清单与修订后的要求进行对照;以及
- 在 2027 年前规划所需的培训、流程调整、系统更新及提早采用评估。
提早准备有助于企业及时发现现有流程与新要求之间的差距,提升财务报告质量,并更有信心地应对 2027 年的变化。
越早准备,越能从容面对 2027 年的变化。
本文内容根据 MASB 发布的 MPERS 2025 资料整理,仅作一般资讯用途,不取代完整准则,也不构成会计、审计或其他专业意见。
企业应根据自身的事实与情况评估相关要求,并在适当情况下咨询专业顾问。
CCS | Beyond Numbers