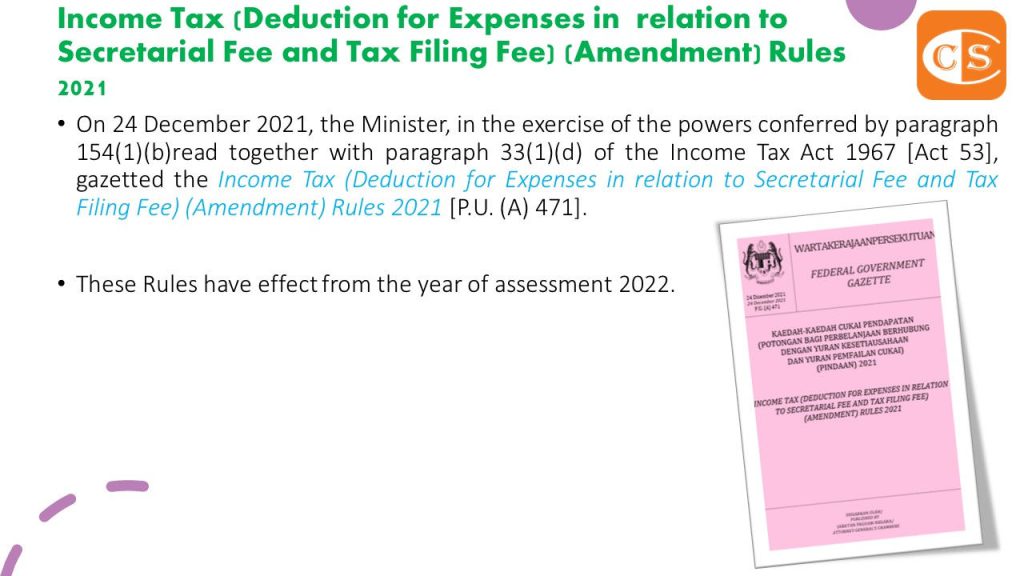
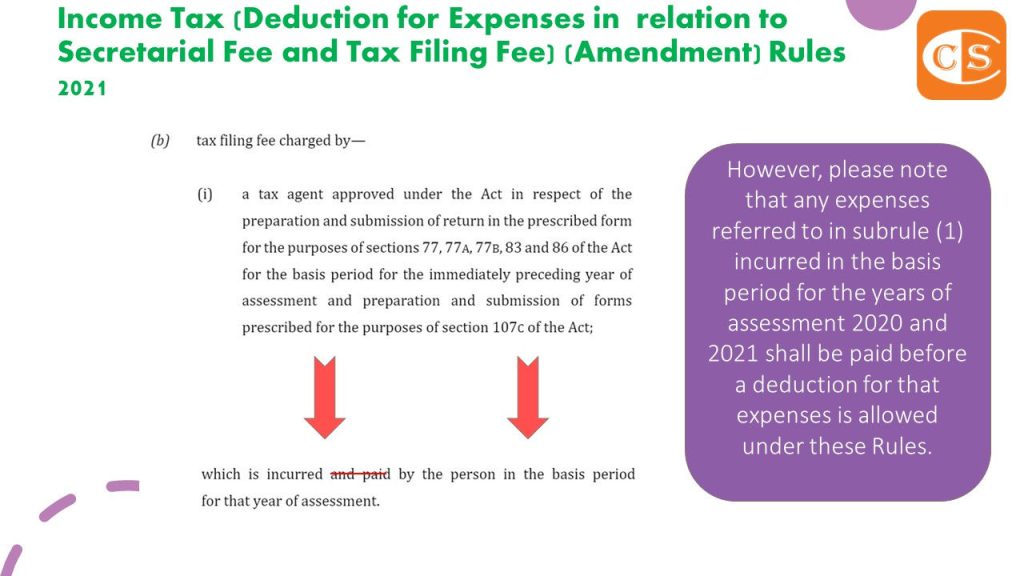
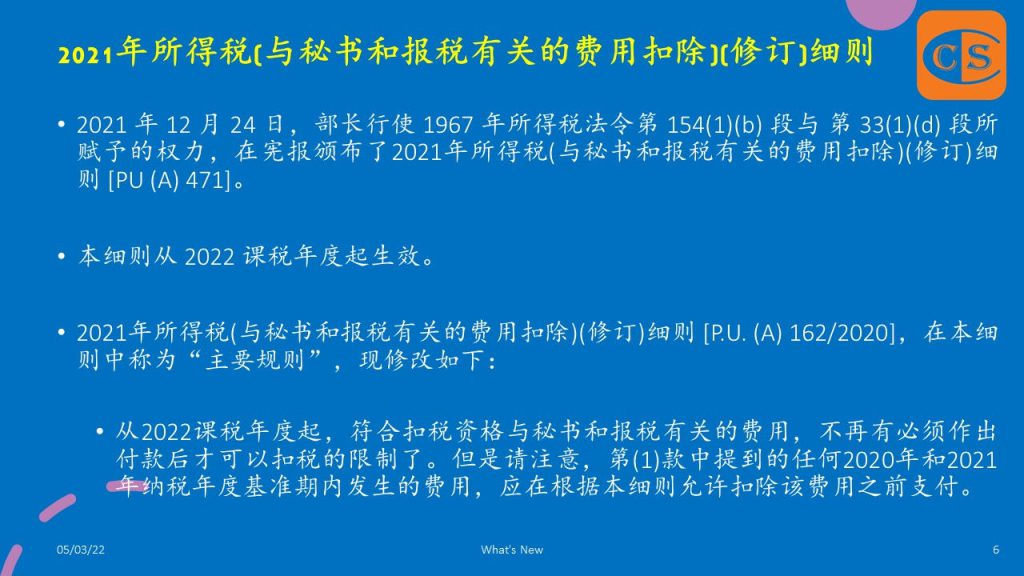
1. On 24 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b)read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) (Amendment) Rules 2021 [P.U. (A) 471].
2. These Rules have an effect from the year of assessment 2022.
1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Costs of Renovation and Refurbishment of Business Premise)(Amendment) Rules 2021 [P.U. (A) 481].
2. These Rules have effect from the year of assessment 2022 to amend Subrule 3(1) of the Income Tax (Costs of Renovation and Refurbishment of Business Premise) Rules 2020 [P.U. (A) 381/2020]
3. With this amendment, it is allowable to deduct the costs of renovation and renovation of business premises incurred by the person between March 1, 2020, and December 31, 2022, and used for its business to determine the adjusted income from the business on the Basis Period for the Year of Assessment.
4. As a result, the Government has extended the eligibility period from December 31, 2021 [Under P.U. (A) 381/2020], to December 31, 2022.
1) To improve compliance and governance, income tax deductions for secretarial and tax filing expenses have been merged and limited to a maximum of RM15,000 each year of assessment effective in the assessment year 2020.
2) The Guideline dated 11 May 2021 revise the Guideline dated 18 September 2020 to explain the tax treatment of secretarial fees and tax filing fees, including filing fees for sales tax, services tax, levy, and tourism taxes.
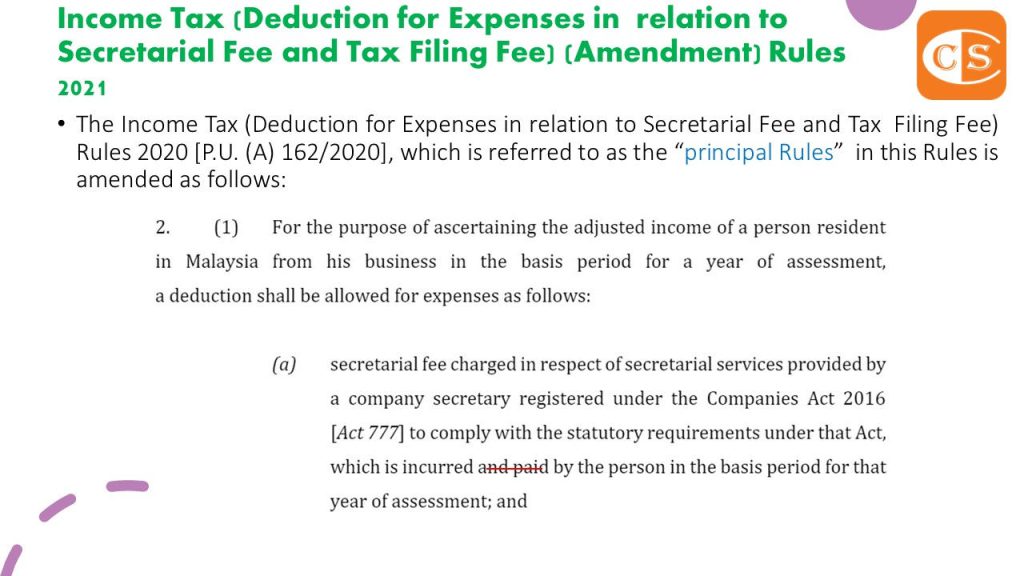
“For the purposes of paragraph (1)(a) and subsection (2), where any sum payable for a basis period for a year of assessment is not due to be paid in that period, the sum shall when it is due to be paid to be deducted in arriving at the adjusted income of a person for that period.”
2. Based on LHDNM’s Response to CTIM Memorandum on Compliance and Operational Issues dated 13 July 2021, on the Income Tax Treatment of Interest expense incurred by SMEs and individuals, that are charged by bank institutions during the moratorium period, the IRBM concludes that: …….. [Please refer to the slide]
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. 根据1967年所得税法令第33(4)条: 就第(1)(a)段和第(2)款而言,如果在某一课税年度 [year of assessment] 的计税基期 [basis period] 内,任何应支付 [due to be paid] 的利息并没有支付的责任,那么相关的利息则在有关人士在需要履行支付的责任时,才在相关的计税基期 [basis period] 从调整收入 [adjusted income] 作出扣除。
1. NDTS is the acronym for the National Dual Training System. ‘Dual’ means training in two learning situations, namely:
👉 The actual workplace (company) that covers 70% to 80% practical training (performance) and;
👉 Training Centre which covers 20% to 30% of theory (knowledge).
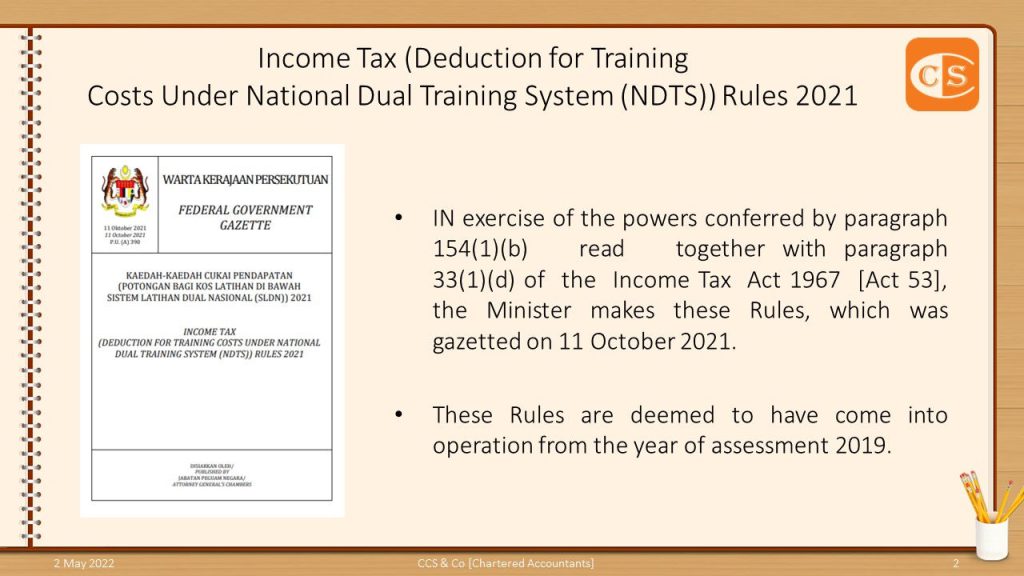
2. IN exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], the Minister makes these Rules, which were gazetted on 11 October 2021.
3. These Rules are deemed to have come into operation from the year of assessment 2019.
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. 参加由人力资源部批准的国家双重培训计划(National Dual Training Scheme)的费用可享有双重扣税。
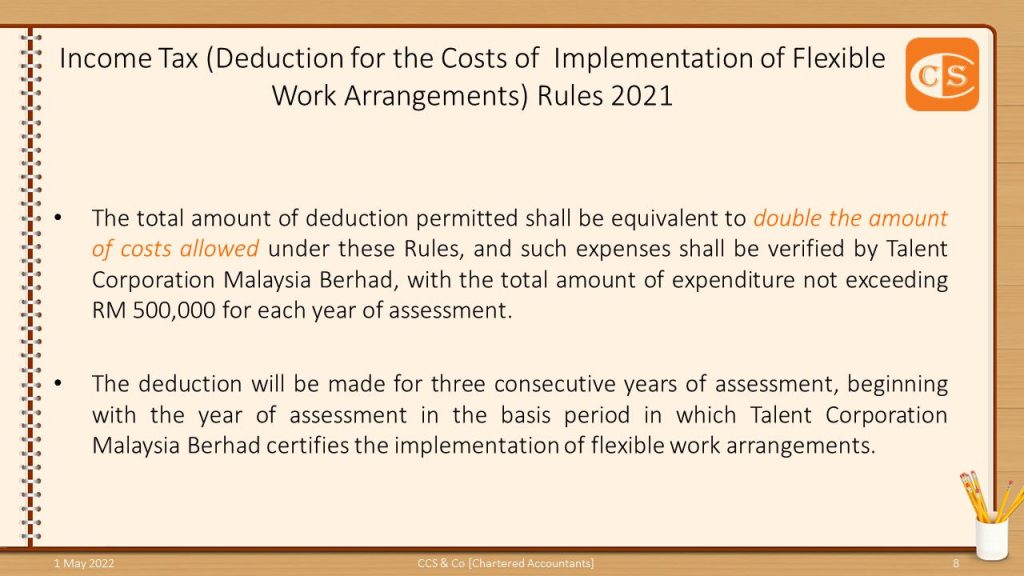
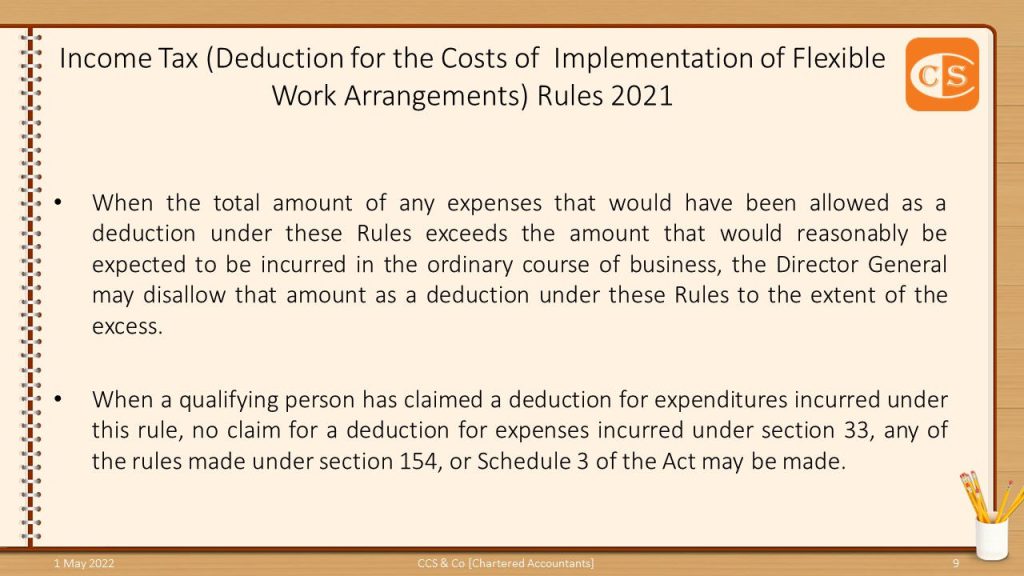
In determining the adjusted income of that qualifying person from his business inthat year of assessment, a deduction shall be allowed for expenses incurred by thatqualifying person in the basis period for the implementation of flexible workarrangements in relation to consultation fee, cost of capacity development, cost of software, and software subscription.
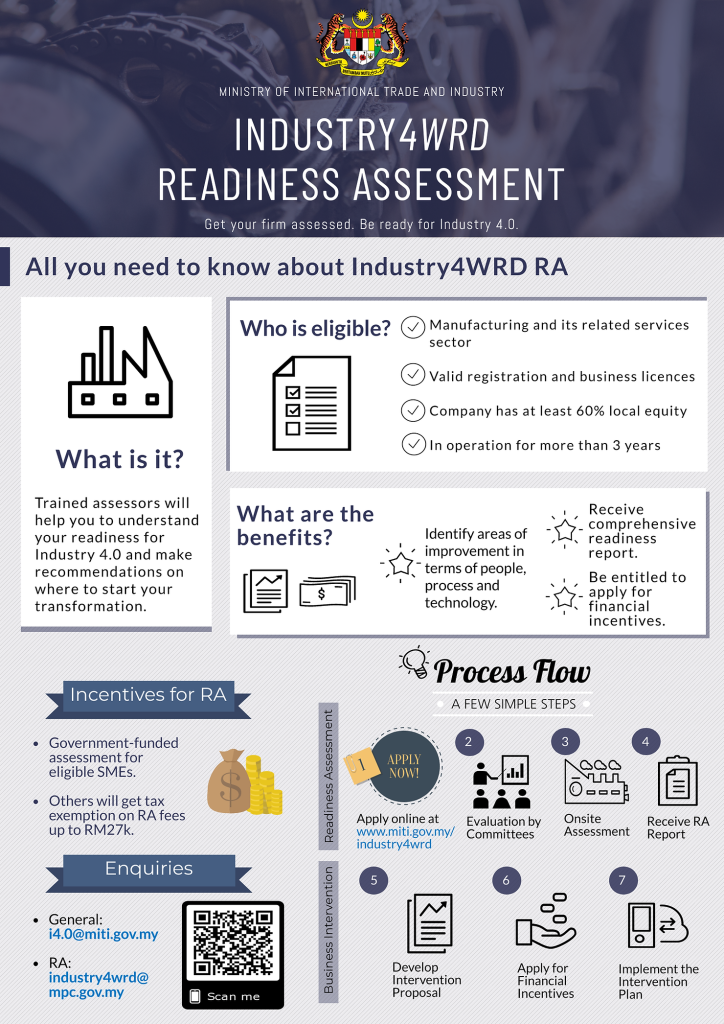
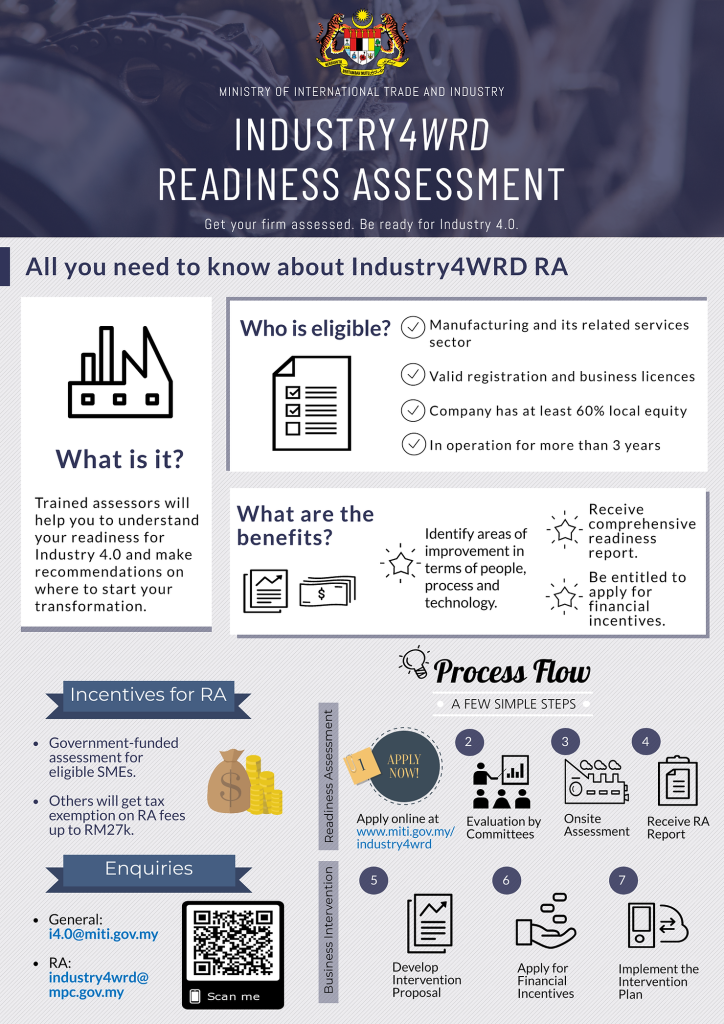
Tax incentives have been announced as part of the Budget 2019 to encourage businesses to work toward reaching Industry4WRD.
One of the incentives relates to allowing the deduction for fee expenses incurred on Industry4WRD Readiness Assessment.
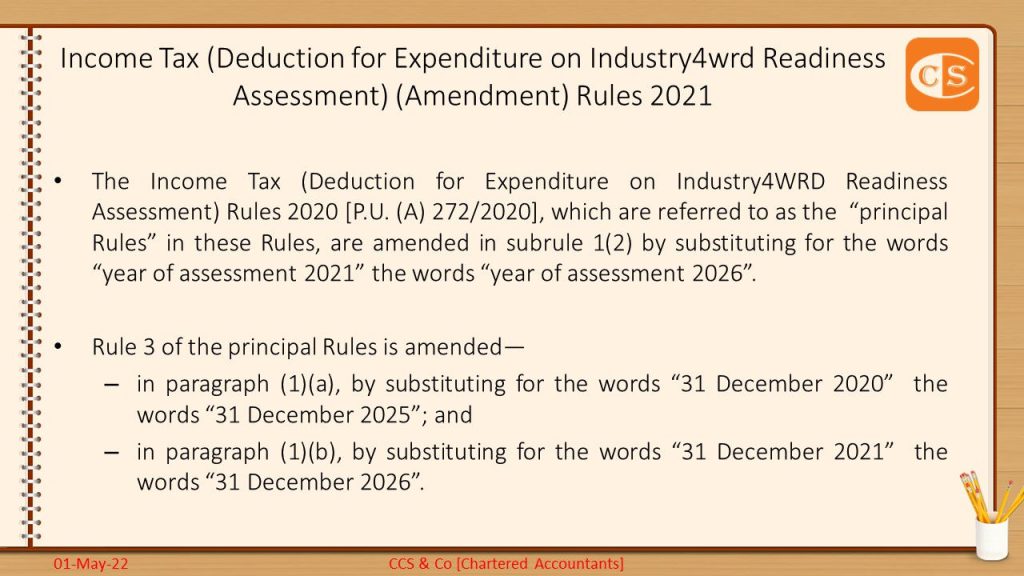
This incentive is provided under the Income Tax (Deduction for Expenditure on Industry4WRD Readiness Assessment) Rules 2020 with the extension under Income Tax (Deduction for Expenditure on Industry4WRD Readiness Assessment) (Amendment) Rules 2021 effective from YA 2019 to YA 2026.
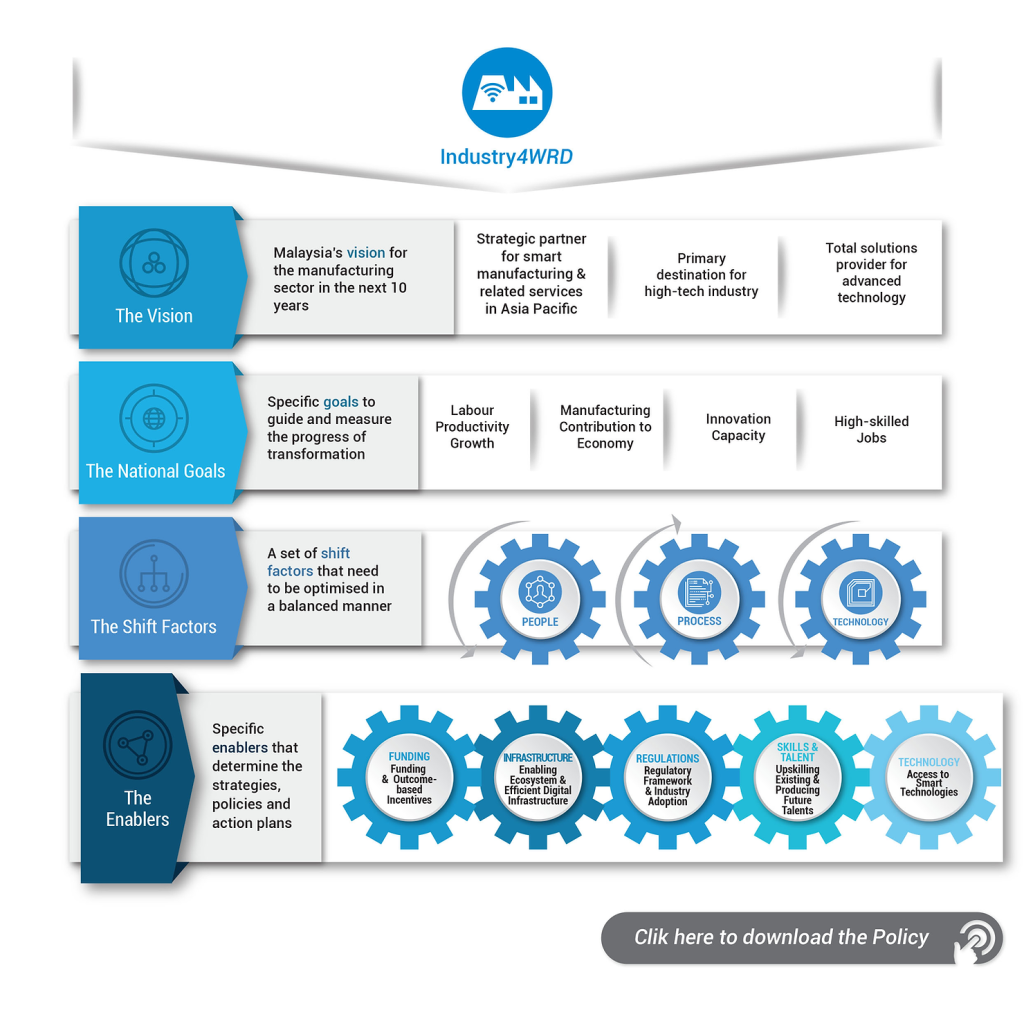
Industry4WRD
In response to the Fourth Industrial Revolution (4IR), the Industry4WRD: National Policy on Industry 4.0 was launched on 31 October 2018 to drive the Digital Transformation of the manufacturing and related services sectors in Malaysia.
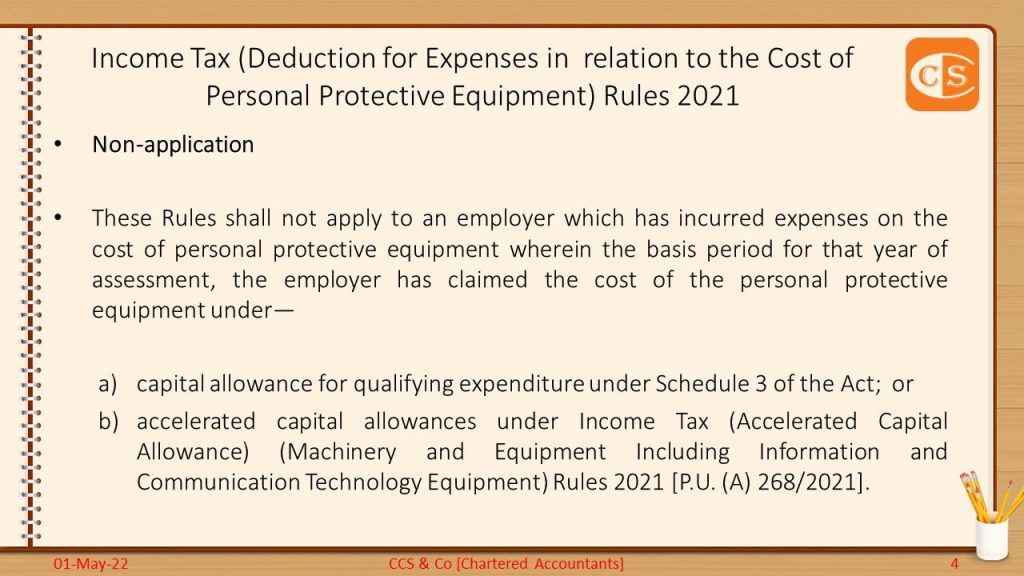
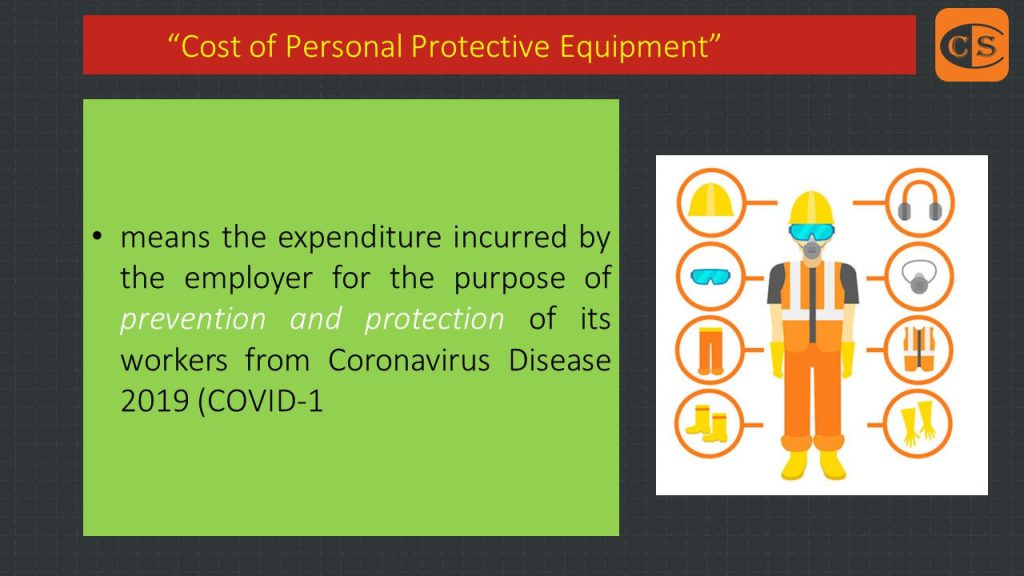
1. Tax deductions for employers on the cost of personal protective equipment (PPE) are offered by the Income Tax (Deduction for Expenses in Relation to the Cost of Personal Protective Equipment) Rules 2021, which are effective from YA 2020 and define personal protective equipment (PPE) as “expenditure incurred by the employer for the purpose of prevention and protection of its workers from COVID-19.” 2. From the first day of March 2020, the deduction for spending on personal protective equipment (PPE) will be applied against adjusted income. 3. However, a deduction will not be given in which:
the employer has claimed capital allowances under the Income Tax Act on the cost of such personal protective equipment, or
the employer has claimed ACA under the Income Tax (Accelerated Capital Allowance) (Machinery and Equipment. Including Information and Communication Technology Equipment) Rules 2021 on the cost of such personal protective equipment.
2. 2021年6月15日,政府在宪报上,颁布了 2021年所得税(针对个人防护装备费用的扣税)细则 [Income Tax (Deduction for Expenses in relation to the Cost of Personal Protective Equipment) Rules 2021]
1) IN exercise of the powers conferred by paragraph 154(1)(b) of, and paragraphs 10 and 15 of Schedule 3 to, the Income Tax Act 1967 [Act 53], the Minister makes these Rules, which were gazetted on 15 June 2021.
2) These Rules shall have effect from the year of assessment 2020.。
3) These rules provide that qualifying plant expenditure incurred by a person in the basis period for a year of assessment from 1 March 2020 until 31 December 2021 and used for the purpose of his business, capital expenditure incurred in relation to provision of machinery and equipment including information and communication technology equipment except motor vehicle qualify for an initial allowance of 20% and an annual allowance of 40%.
4) As specified in the Income Tax (Accelerated Capital Allowance) (Machinery and Equipment, Including Information and Communication Technology Equipment) Rules 2021, capital portions of instalment payments made during the period on machinery and equipment purchased under hire purchase arrangements would be eligible for the ACA.
5) Anyone who has incurred plant expenditure and has already claimed ACA under the Income Tax (Accelerated Capital Allowance) (Automation Equipment) Rules 2017 or exemption under the Income Tax (Exemption No 8) Order 2017 would not be eligible to claim. 1. 大家应该知道,公司买 Assets,只要符合 Plant 的定义,都可以扣税
5. 2021年6月15日,政府在宪报上,颁布了 2021年所得税(加速资本津贴)(机械和设备,包括信息和通信技术设备)细则 [Income Tax (Accelerated Capital Allowance) (Machinery and Equipment including Information and Communication Technology Equipment) Rules 2021]