The change from “real-time or near real-time validation” to “near real-time validation” seems to be providing more flexibility and clarity on the timing of the e-Invoice validation process.
“Near real-time validation” implies that the validation happens very quickly after submission but not necessarily instantaneously.
By changing it to “near real-time validation”, it opens up the possibility that the validation could happen either:
1) In real-time – meaning instantaneously or with an imperceptible delay upon submission of the e-Invoice.
2) Or in near real-time – meaning with a slight delay, but still very quickly after submission.
The key impact and reason for this change is to account for the fact that while the system aims for real-time validation, there may be instances where due to high volumes or other factors, the validation may not be truly instantaneous but still extremely fast (near real-time).
This phrasing provides more accurate expectations and covers both the ideal real-time scenario as well as any instances where there is a slight delay but still very rapid validation occurring.
It gives the e-Invoicing system a bit more flexibility in terms of managing volumes and loads, while still committing to a highly efficient and prompt validation process – either real-time or as close to real-time as possible.
So in summary, it is a minor change to set appropriate expectations and provide a small buffer, in case rare scenarios arise where validations cannot be precisely real-time but still occur almost instantaneously after submission.
Based on the comparison between the e-Invoice Specific Guideline Version 2.0 and Version 2.1, one of the key changes is Section 3.6.4, a new addition stating that to improve the MyInvois System’s performance, there are limitations on the maximum size (5MB) and number (100) of e-Invoices per submission and the maximum size per e-Invoice (300KB) for the submission of the consolidated e-Invoices.
Suppliers can split receipts into several consolidated e-Invoices to meet these requirements.
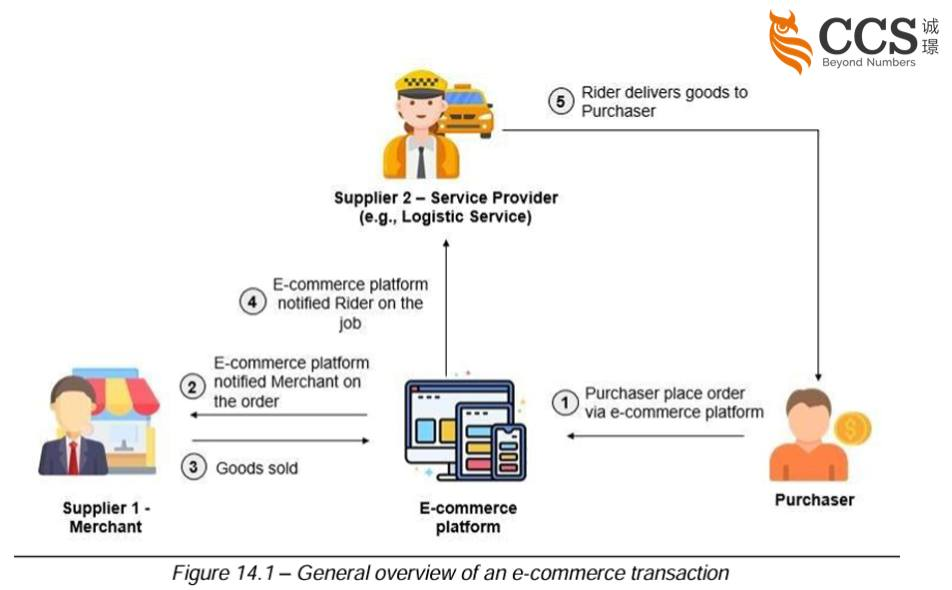
Below is a structured outline for e-commerce transactions, specifically focusing on the issuance of e-invoices by e-commerce platform providers, as per the E-INVOICE SPECIFIC GUIDELINE (VERSION 2.0).
Definition: E-commerce transactions refer to the sale or purchase of goods or services conducted over a platform designed specifically for order placement or receipt. Notably, the actual payment and delivery of goods or services may not be conducted online.
Participants: These transactions can involve a variety of parties including businesses, households, individuals, governments, and other organisations.
Key Responsibility: E-commerce platform providers are tasked with issuing invoices, bills, or receipts to record transactions.
Upon implementing e-invoicing, they must issue either an e-invoice upon the purchaser’s request or a receipt if no e-invoice is requested.
第 2 部分:电子商务平台提供商的作用
主要责任: 电子商务平台提供商的任务是开具发票、账单或收据以记录交易。
在实施电子发票后,他们必须根据购买者的要求开具电子发票,如果没有要求开具电子发票,则必须开具收据。
🔴 Part 3: E-Invoice Issuance Process
Process Overview: Merchants or service providers on the e-commerce platform are not required to issue e-invoices or receipts directly to purchasers.
This responsibility falls on the e-commerce platform providers.
Required Information: The e-Invoice must include specific data fields as outlined in Appendices 1 and 2 of the e-Invoice Guideline, ensuring comprehensive transaction details.
Special Consideration: For consolidated e-invoices, e-commerce platform providers must complete the required fields and certain transaction details, as the guideline specifies.
🔴 Part 5: e-commerce transactions between platform providers and merchants or service providers
The process involves the e-commerce platform provider issuing self-billed e-invoices to the merchant or service provider upon the conclusion of a sale or transaction on the platform.
This is a critical aspect concerning the financial transactions and record-keeping between the two parties involved.
Upon concluding a sale or transaction on the e-commerce platform, the merchant and/or service provider is eligible to receive payment from the e-commerce platform provider for the goods sold and/or services performed.
In this scenario, the e-commerce platform provider assumes the role of the buyer, and the merchant or service provider assumes the role of the supplier.
The e-commerce platform provider is then responsible for issuing a self-billed e-invoice to the merchant and/or service provider for all transactions concluded on the e-commerce platform.
For the issuance of these self-billed e-Invoices, the e-commerce platform provider must input specific details such as the merchant or service provider’s business or residential address, contact number, and, where available, email address. If such information is unavailable or not provided, the platform provider must input “NA” in the respective fields.
This structured approach to issuing self-billed e-invoices facilitates a clear and transparent financial relationship between e-commerce platform providers and merchants or service providers, ensuring that all transactions are properly documented in compliance with relevant guidelines and regulations.
🔴 Part 6: Issuance of e-Invoice from e-commerce platform provider to Merchant and/or Service Provider
Furthermore, e-commerce platform providers also charge merchants and/or service providers for using the platform.
Upon implementing an e-invoice, the e-commerce platform provider is responsible for issuing an e-invoice for the charges imposed on the merchant and/or service provider for using the platform.
This ensures that all financial transactions and charges associated with using the e-commerce platform are accurately documented and invoiced.
In the past, some local businesses in Malaysia have been under-declaring the true value of imported goods to save on customs duties.
However, when it comes to bookkeeping, they have been recording the transactions at their actual values, which are relatively higher, to take advantage of tax deductions.
With the introduction of the e-invoicing era, these local businesses need to take note of this matter.
Yes, sub-contractors and sole proprietors are required to issue e-invoices if they are undertaking commercial activities in Malaysia.
This requirement applies to all individuals and legal entities, including sole proprietors and sub-contractors, as part of the broader mandate to comply with the e-invoicing requirement for commercial transactions.
Based on the guidelines and the scenario provided (Example 1), it appears that issuing a refund note e-Invoice by Mr. Jamal to document the refunded amount for the faulty chairs directly addresses the situation without the need for a separate credit note.
The refund note e-Invoice serves the dual purpose of documenting the refund and making the necessary adjustment to the original transaction value.
In this context, the refund note e-Invoice effectively reduces the value of the original e-Invoice by the amount refunded for the returned goods.
This approach simplifies the process by directly adjusting the original transaction’s value to reflect the return and refund in a single step.
Therefore, issuing a separate credit note before the refund note e-Invoice would not be necessary unless there was a specific requirement or scenario not covered in the provided example.
The key distinction here is that the refund note e-Invoice is used when there is an actual return of monies to the buyer, as opposed to a credit note which is typically used to adjust the value of transactions without a direct refund.
Since the scenario explicitly involves a refund for the faulty chairs, the use of a refund note e-Invoice is appropriate and aligns with the guidelines for handling such transactions.
However, most accounting software may require the taxpayer to issue a credit note first, subsequently followed by a refund note if the buyer requests for a refund, even though issuing a separate credit note before the refund note e-Invoice would not be necessary based on the e-Invoicing guidelines.
This question about e-invoices is one that many people want to know: Can self-billed e-invoices be consolidated?
The E-INVOICE SPECIFIC GUIDELINE (VERSION 2.1) answers but needs to say how to do it. I believe the SDK will explain it.
My view is, the primary reason for permitting consolidation in these specific circumstances could be to provide flexibility to taxpayers and reduce the administrative burden of submitting self-billed e-Invoices for validation on a day-to-day basis. Instead, taxpayers can consolidate these transactions and submit a consolidated self-billed e-invoice once a month.
However, it’s crucial to note that while the consolidated self-billed e-Invoice may be submitted to the LHDN on a monthly basis, it is likely that LHDN will still require taxpayers to include all the relevant details of the individual transactions in the consolidated e-Invoice. This would ensure that LHDN has access to the necessary information for each transaction, even if they are consolidated into a single e-invoice.
By providing these details in the consolidated self-billed e-invoice, taxpayers would maintain transparency and enable the tax authorities to verify the accuracy of the consolidated amount and cross-reference it with other available information.
It’s important to wait for more announcements and clarifications from LHDN regarding the specific requirements and format for consolidated self-billed e-invoices.
Once LHDN provides more detailed guidelines, taxpayers will have a clearer understanding of the information they need to include in these consolidated e-invoices and can ensure compliance accordingly.
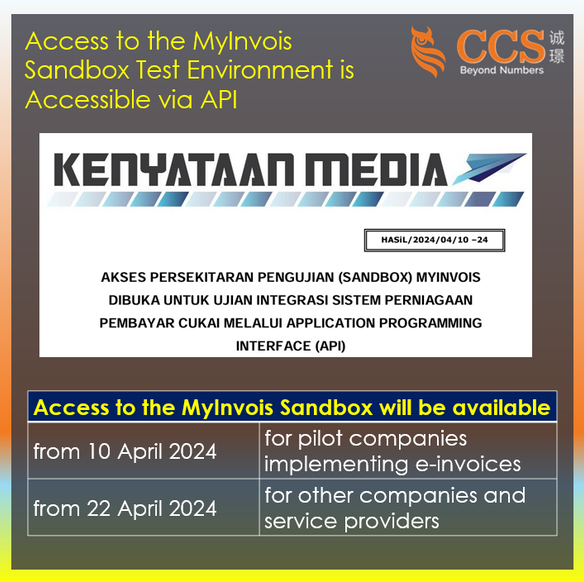
The Inland Revenue Board of Malaysia (IRBM) informed that the MyInvois Testing Environment (Sandbox) is now accessible to enable taxpayers and service providers to conduct integration testing between systems developed by taxpayers or service providers with MyInvois via Application Programming Interface (API).
Access to the MyInvois Sandbox will be available:
from 10 April 2024 for pilot companies implementing e-invoices; and
from 22 April 2024 for other companies and service providers.
To access this sandbox, taxpayers or service providers need to apply for a Client ID and Client Secret key from IRBM via email at [email protected], providing the following information:
Tax Identification Number (TIN),
Business Registration Number,
Company Name,
Company email, and
Name of the Enterprise Resource Planning (ERP) system used.
Further information regarding access to the MyInvois Sandbox can be found in the:
IRBM also wishes to inform taxpayers that the Software Development Kit (SDK) version 1.0, General Guidelines for e-Invois (Version 2.3), and Specific Guidelines for e-Invois (Version 2.1) were uploaded to the Micro e-Invois Page on the Official IRBM Portal via the link https://www.hasil.gov.my/e-invois on 6 April 2024 as references and guidance
For further inquiries regarding the SDK and MyInvois System Sandbox, taxpayers can contact the hotline at 03-8682 8000 or email [email protected].
The Inland Revenue Board of Malaysia (IRBM) has informed that payments for Labuan Business Activity Tax (CAPL) can be made using the Billing Number as the payment reference starting from 1 April 2024.
The Billing Number can be obtained by applying the Labuan International Section, IRBM Sabah.
This can be done through the following methods:
Calculating the tax rate and payment amount first according to the assessment year;
Filling in the required information in the relevant application form; and
Submitting the completed application form to the respective section for processing to generate the Billing Number. The generated Billing Number will be communicated to the taxpayer through the Payment Slip.
The application form is subject to one assessment year and one tax rate only.
If the payment involves multiple assessment years, separate forms must be filled out.
Payments using the Billing Number can be made through the ByrHASiL Portal at https://byrhasil.hasil.gov.my > Payment Options > Payment Using Billing Number.
Further information regarding the application for the Billing Number can be referred to the user manual accessible through the MyTax Portal at https://mytax.hasil.gov.my/ > User Guides > CAPL Billing Number Application User Manual.
For any inquiries or feedback, please contact us via:
Hasil Contact Centre (HCC) at 03-8911 1000 / 603-8911 1100 (International);