Special Program For Revenue Saved Abroad
Tag: Foreign-Sourced Income
-

1: What Is International Tax?
What Is International Tax? – PDF

- THE Budget 2022 proposed that foreign-sourced income received in Malaysia would be subject to income tax in Malaysia with effect from Jan 1, 2022
- For convenience, we use the term “international tax” in our sharing, and “international tax laws” are the laws of a particular country that deal with the international aspect of income tax.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 2022年预算案提出:
👉 从2022年1月1日起,
👉 在马来西亚收到的源自外国的收入
👉 将在马来西亚缴纳所得税。
2 . 为了方便起见,我们在分享中使用了 “国际税收”一词,”国际税法”是特定国家应对国际间的所得税法。
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
2: International Organizations involved In International Tax – OECD

1. Despite the fact that sovereign nation-states are largely responsible for creating the rules of the international tax system through domestic law and tax treaties, other international organisations play a significant role in international tax.
2. The OECD, the International Monetary Fund (IMF), the United Nations (UN), and the World Bank Group (WGB) are the four primary international organisations involved in international taxation.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 尽管主权国家在很大程度上负责通过国内法律和税收协定建立国际税收制度的规则,但其他国际组织在国际税收中也发挥着重要作用。
2. 经合组织 [OECD]、国际货币基金组织 [IMF]、联合国 [UN] 和世界银行集团 [WBG] 是涉及国际税收的四个主要国际组织。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
3: International Organizations involved In International Tax – Group of Twenty
94.-International-Organizations-involved-In-International-Tax-Group-of-Twenty-The-G20-参与国际税收的国际组织Download
1. The Group of Twenty (G20) and the OECD initiated a cooperative endeavour in 2012 to combat Base Erosion and Profit Shifting (“BEPS”).
2. The OECD’s Action Plan on BEPS was released in 2013, outlining a robust agenda with fifteen specific action items; the final reports were released in October 2015. (available at www.oecd.org).
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 为了打击税基侵蚀和利润转移(“BEPS”),二十国集团(G20)和经合组织在2012年发起了一项合作项目。
2. 经合组织关于 BEPS 的行动计划于 2013 年发布,概述了一个包含 15 个具体行动项目的强大议程;各项工作的最终报告于2015年10月发布。(可在www.oecd.org)。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
4: International Organizations involved In International Tax – G20
95.-International-Organizations-involved-In-International-Tax-G20_OECD-Inclusive-Framework-参与国际税收的国际组织Download
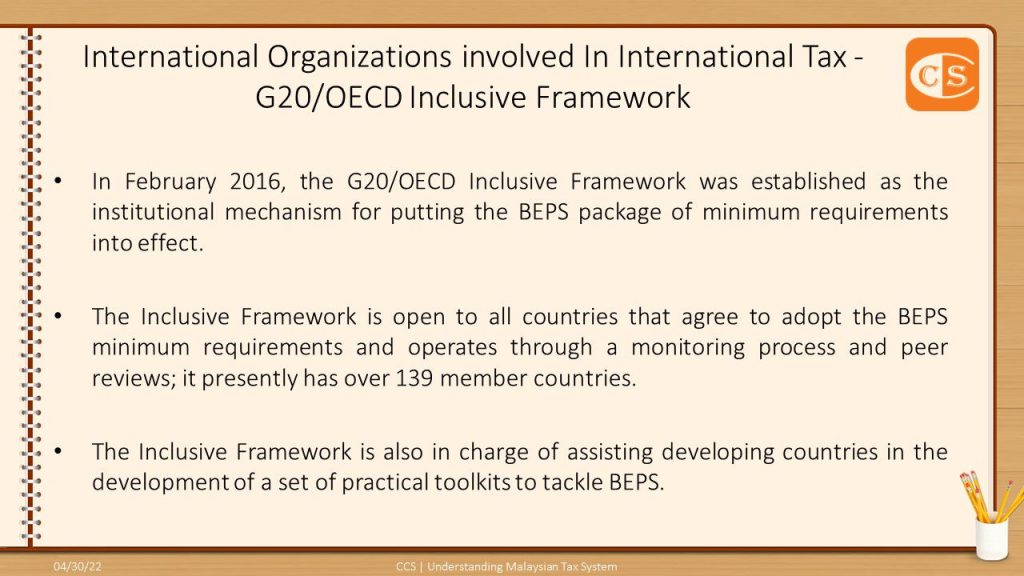
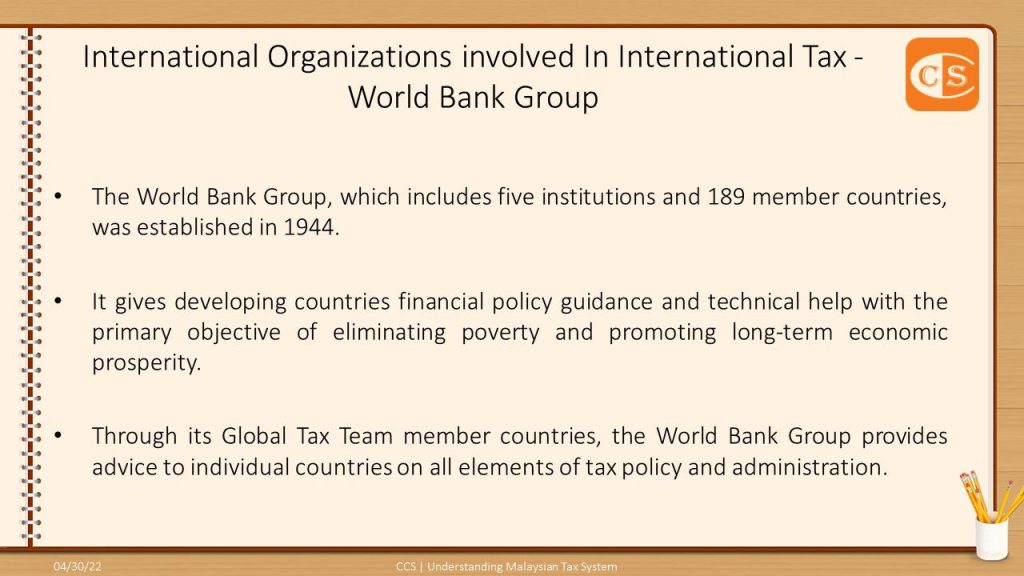
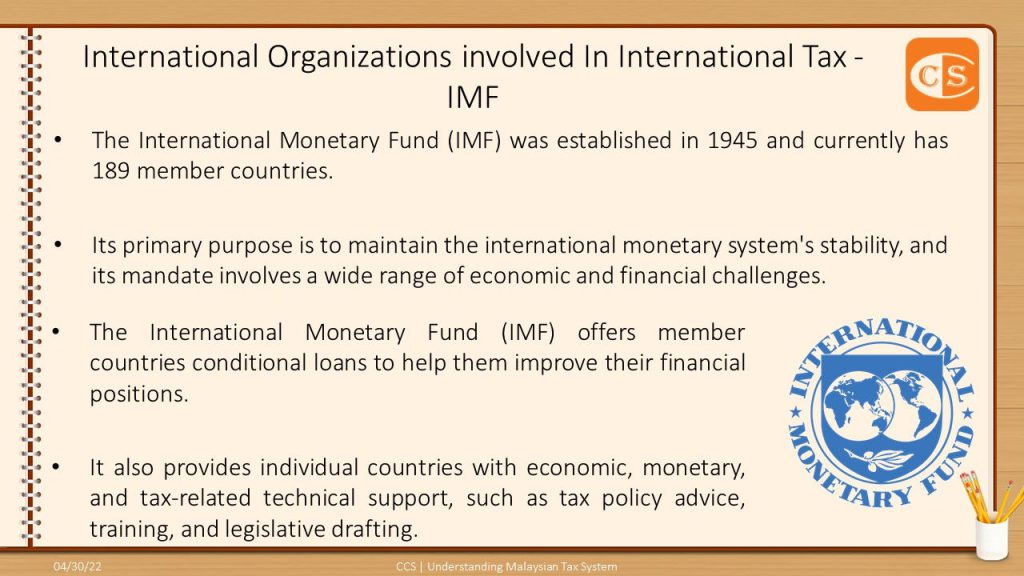
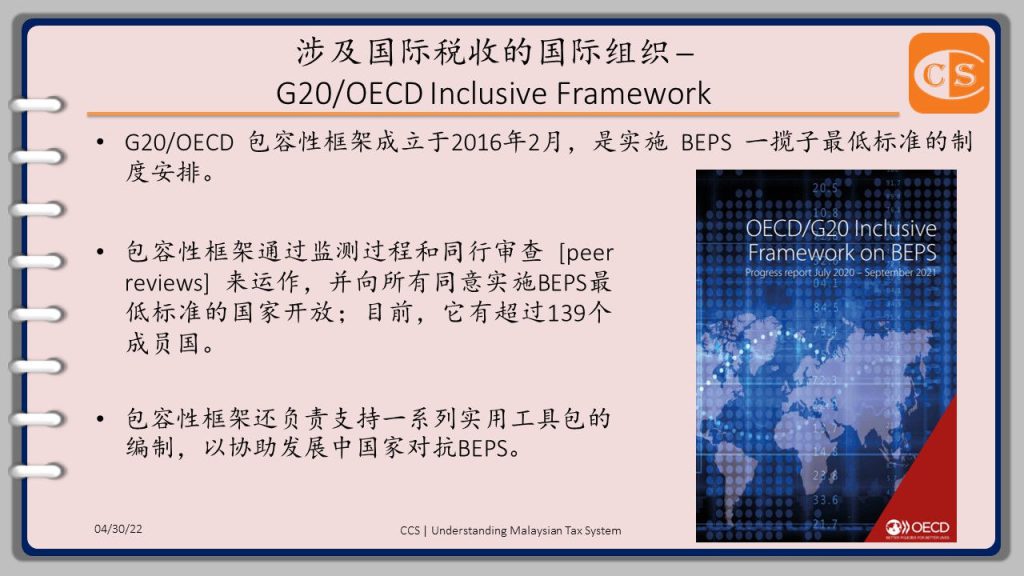
1. The OECD, the International Monetary Fund (IMF), the United Nations (UN), and the World Bank Group (WGB) are the four primary international organisations involved in international taxation.
2. The G20/OECD Inclusive Framework, the International Monetary Fund [IMF], and the World Bank Group [WBG] will all be discussed today.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 经合组织 [OECD]、国际货币基金组织 [IMF]、联合国 [UN] 和世界银行集团 [WBG] 是涉及国际税收的四个主要国际组织。
2. 今天我们就来谈谈G20/OECD 包容性框架、际货币基金组织 [IMF] 和世界银行集团 [WBG]
3. 为了打击税基侵蚀和利润转移(“BEPS”),二十国集团(G20)和经合组织在2012年发起了一项合作项目。
4. 经合组织关于 BEPS 的行动计划于 2013 年发布,概述了一个包含 15 个具体行动项目的强大议程;各项工作的最终报告于2015年10月发布。(可在www.oecd.org)。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy


-
5: International Organizations involved In International Tax – United Nations

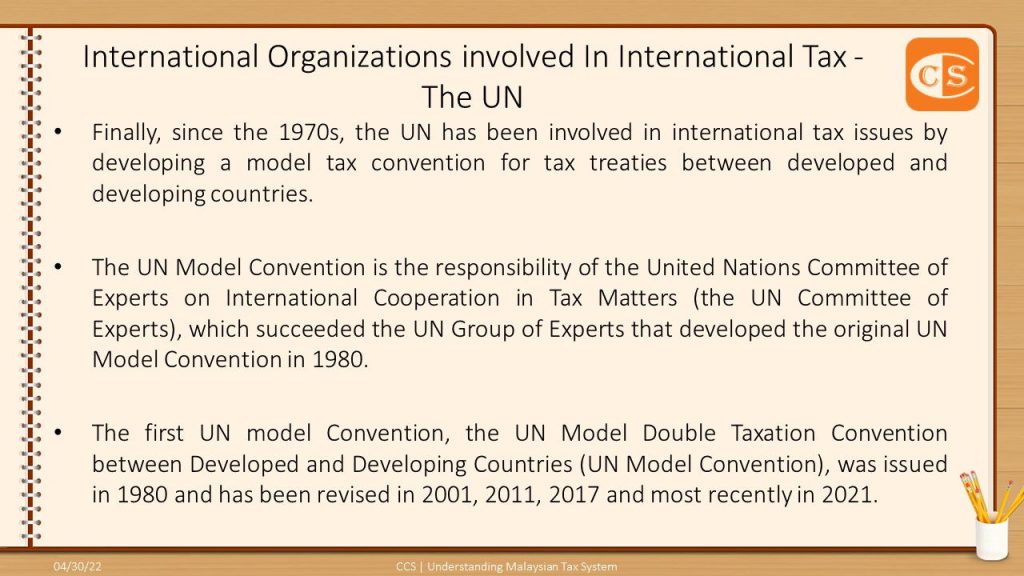
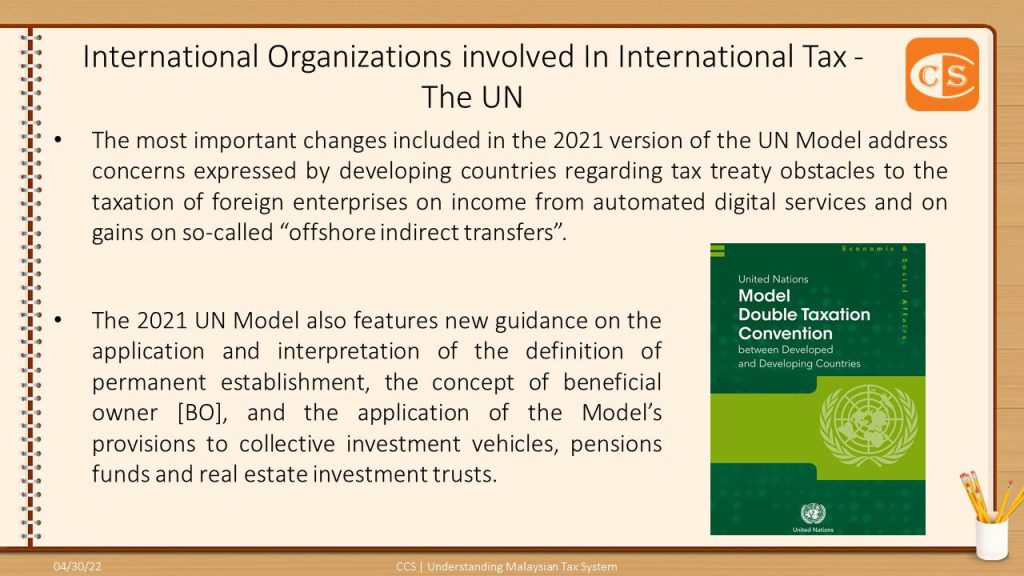
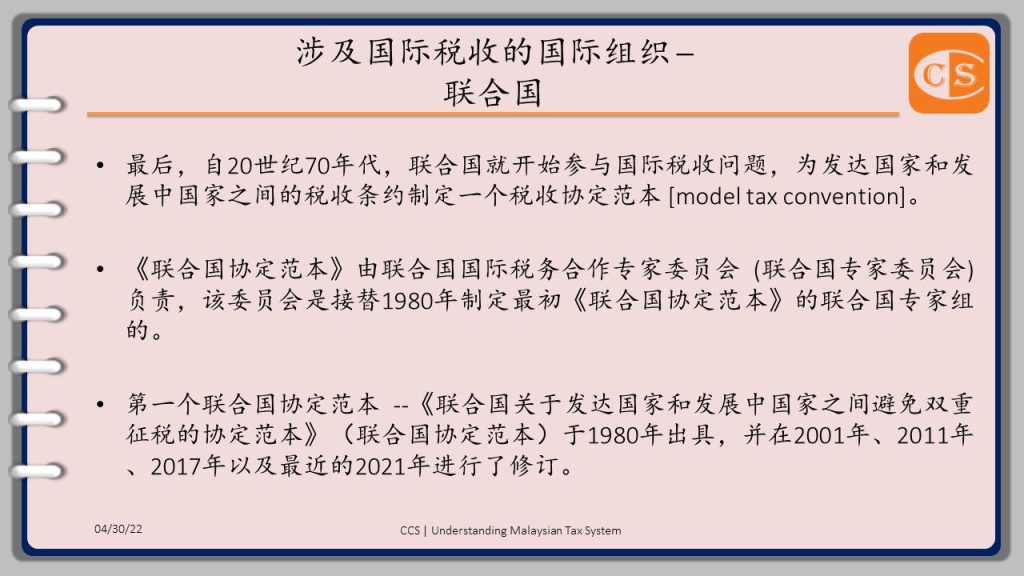
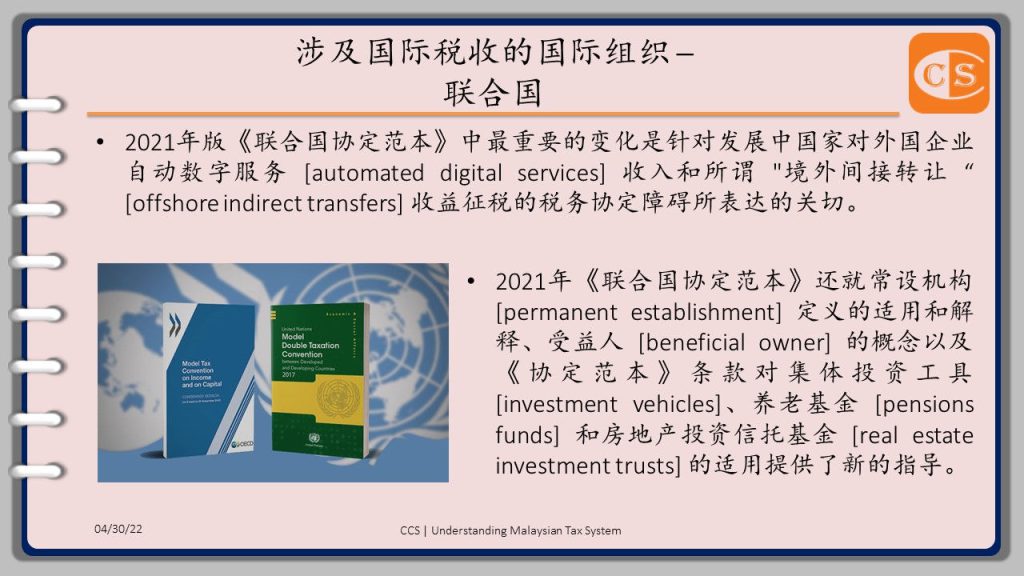
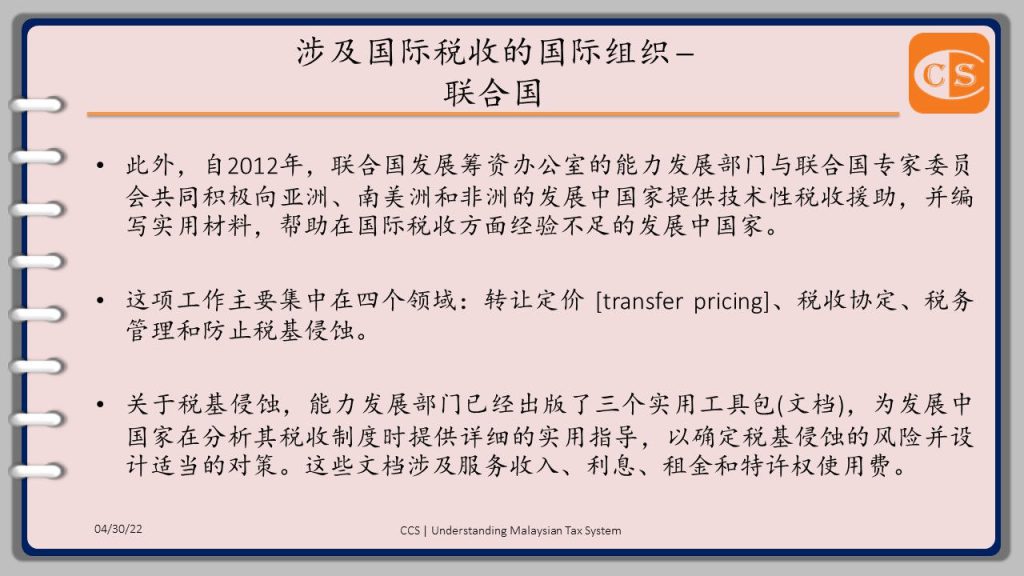
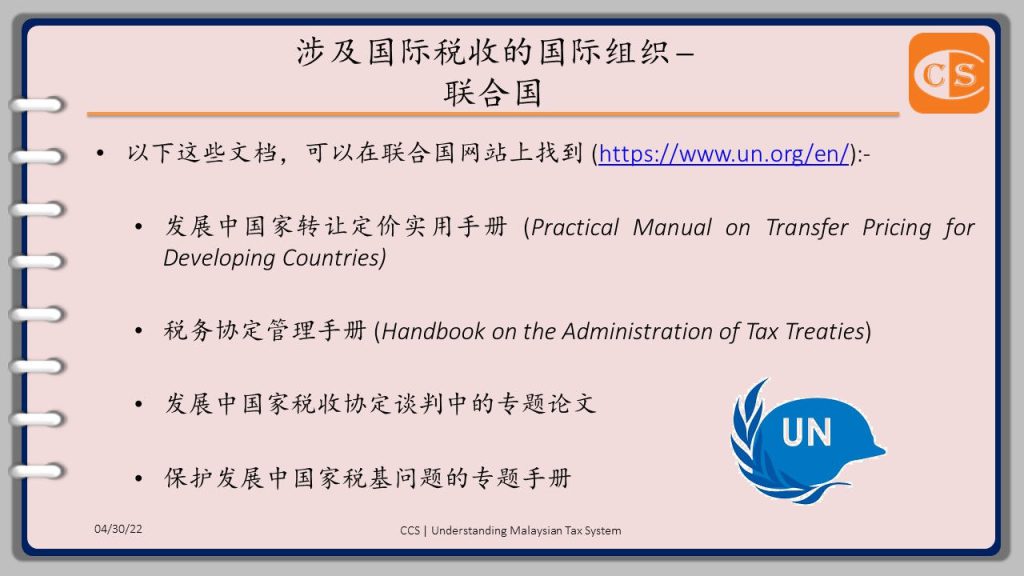
1. Finally, since the 1970s, the UN has been involved in international tax issues by developing a model tax convention for tax treaties between developed and developing countries.
2. The UN Model Convention is the responsibility of the United Nations Committee of Experts on International Cooperation in Tax Matters (the UN Committee of Experts), which succeeded the UN Group of Experts that developed the original UN Model Convention in 1980.
3. The first UN model Convention, the UN Model Double Taxation Convention between Developed and Developing Countries (UN Model Convention), was issued in 1980 and has been revised in 2001, 2011, 2017, and most recently in 2021.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
1. 最后,自20世纪70年代,联合国就开始参与国际税收问题,为发达国家和发展中国家之间的税收条约制定一个税收协定范本 [model tax convention]。
2. 《联合国协定范本》由联合国国际税务合作专家委员会 (联合国专家委员会)负责,该委员会是接替1980年制定最初《联合国协定范本》的联合国专家组的。
3. 第一个联合国协定范本 –《联合国关于发达国家和发展中国家之间避免双重征税的协定范本》(联合国协定范本)于1980年出具,并在2001年、2011年、2017年以及最近的2021年进行了修订。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy
-
No More Exemption on Foreign Sourced Income Remitted to Malaysia
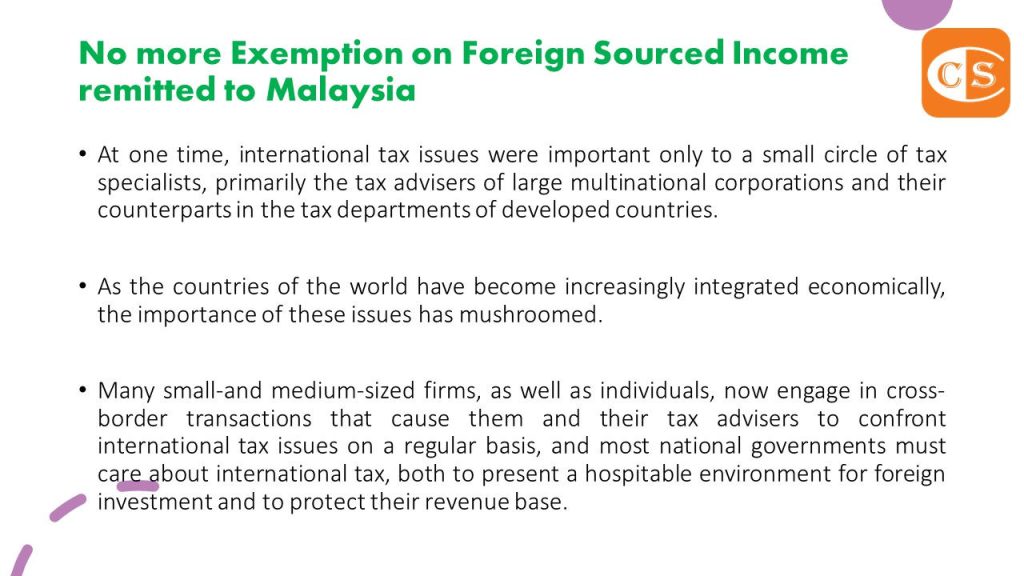
1. No more Exemption on Foreign Sourced Income remitted to Malaysia!
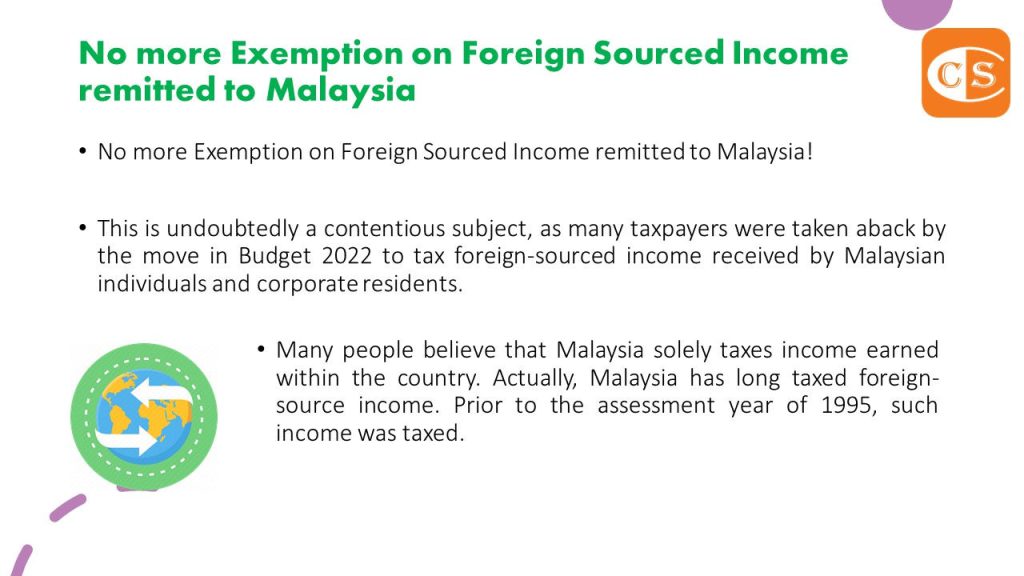
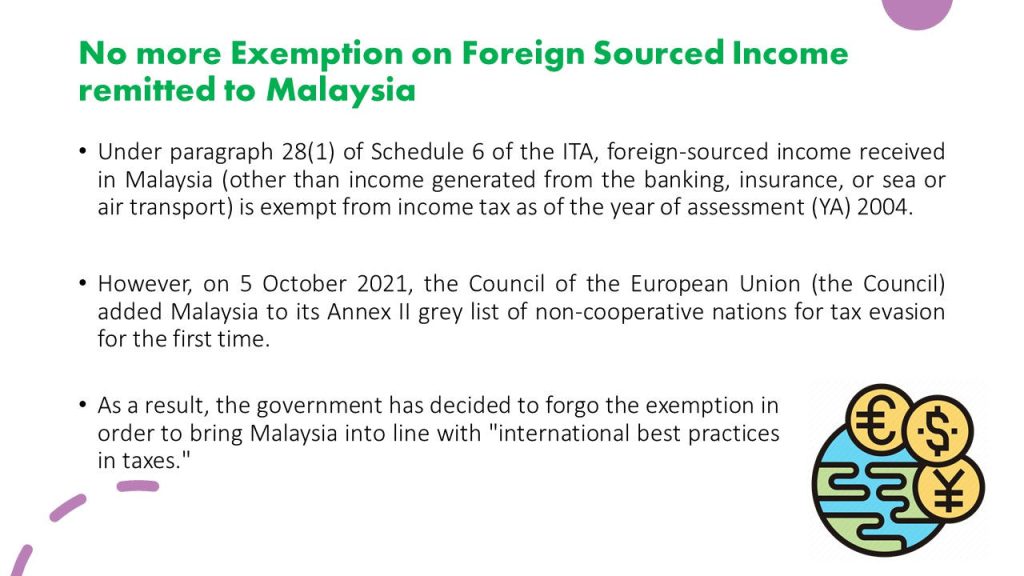
2. This is undoubtedly a contentious subject, as many taxpayers were taken aback by the move in Budget 2022 to tax foreign-sourced income received by Malaysian individuals and corporate residents.
3. Any taxes paid outside of Malaysia on the foreign income remitted can be offset (deducted) against the Malaysian tax on such foreign income.
4. Please note that the bilateral credit, on the other hand, cannot exceed the whole amount of Malaysian tax on foreign income.
🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻
2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免
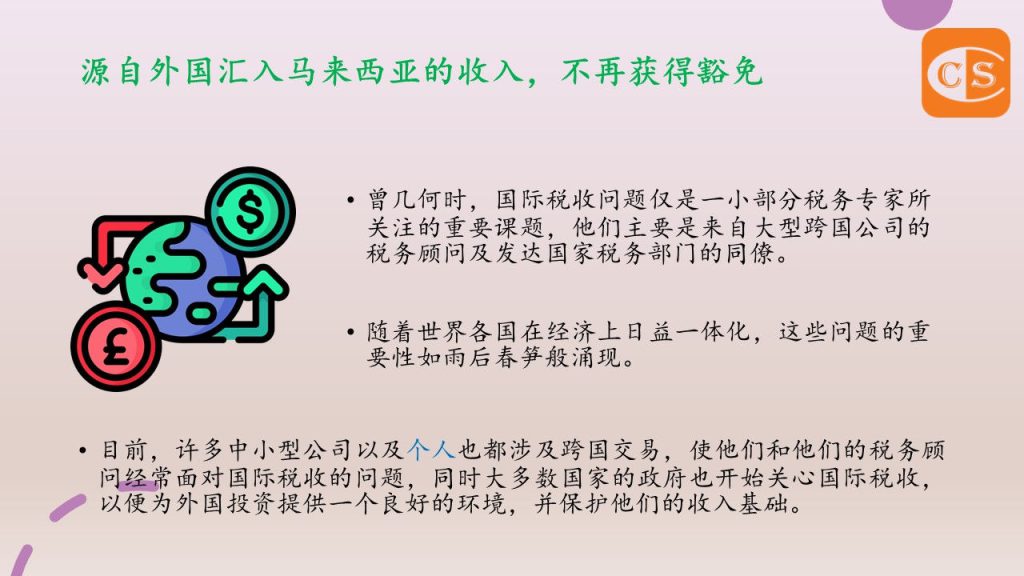
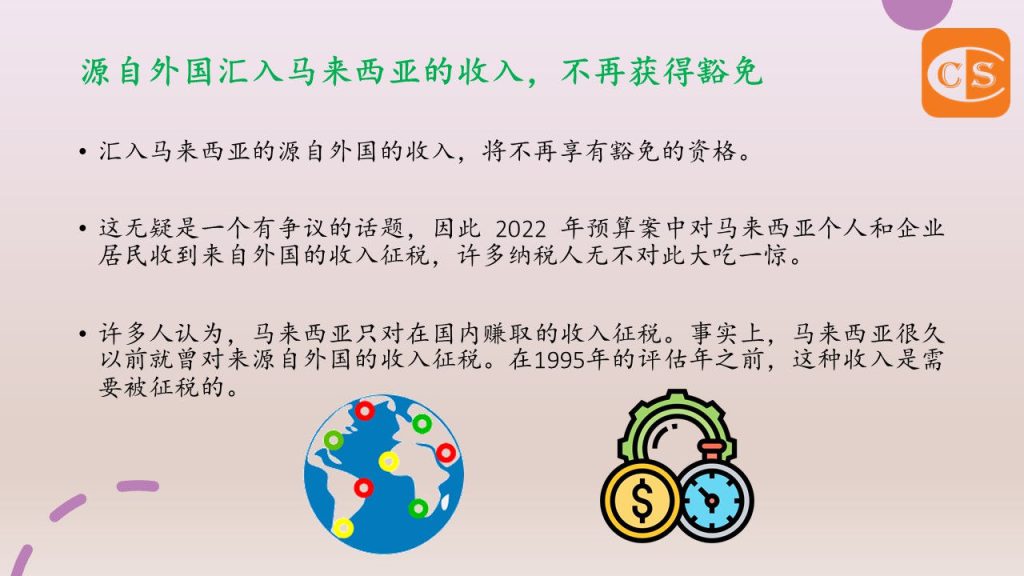
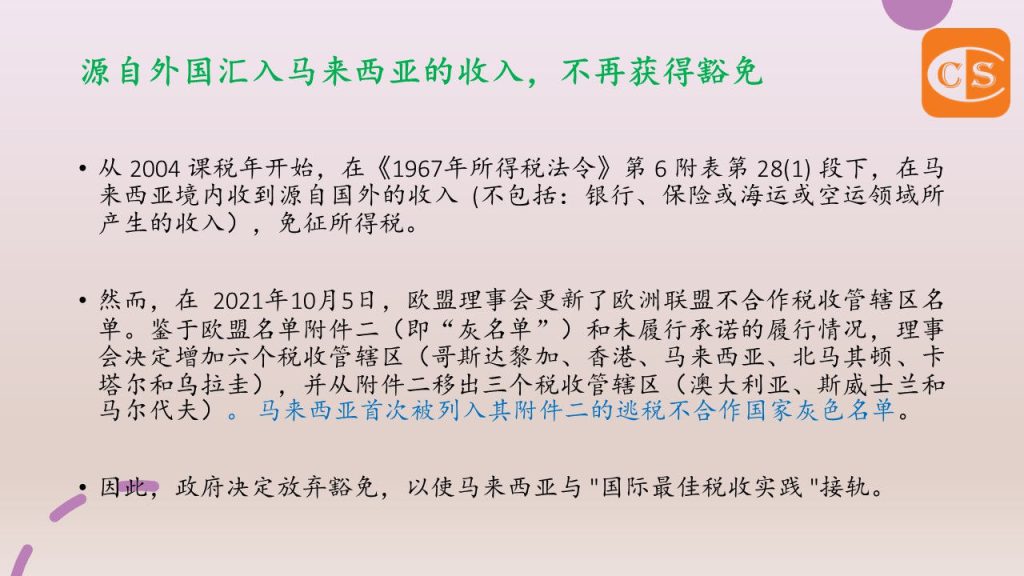
1. 汇入马来西亚的源自外国的收入,将不再享有豁免的资格。
2. 这无疑是一个有争议的话题,因此 2022 年预算案中对马来西亚个人和企业居民收到来自外国的收入征税,许多纳税人无不对此大吃一惊。
#税法之道博大精深,#建议大家深度学习
🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3
2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4
3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S
4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh
5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE
6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2
7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc
8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k
9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN
10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd
11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W
12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK
13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2
14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE
15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3
16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR
17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D
19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH
20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd
21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9
22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq
23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr
24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq
25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda
26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw
27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV
28. What Exactly is Considered a Taxable Remittance: 1 – Introduction
[究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ
29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances
[究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5
30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?
[究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX
31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?
[究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq
32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK
33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm
🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼
#当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:
✅ 查询相关资料是否依然合时、准确和完整;和
✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:
🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and
🅾️ seek your independent professional advice because the scope and extent involved in each case are different.
🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳
👉 Stay in touch with us
1. Website ✍️ https://www.ccs-co.com/
2. Telegram ✍️ http://bit.ly/YourAuditor
3. Instagram ✍ http://tiny.cc/rojzrz
4. Blog ✍ https://lnkd.in/e-Pu8_G
5. Google ✍ https://lnkd.in/ehZE6mxy