Tag: Foreign-Sourced Income

  • 17: An individual’s Tax Residence under s 7(1)(a) ITA 1967

    17: An individual’s Tax Residence under s 7(1)(a) ITA 1967

    An individual’s tax residence under s 7(1)(a) ITA 1967 – PDF
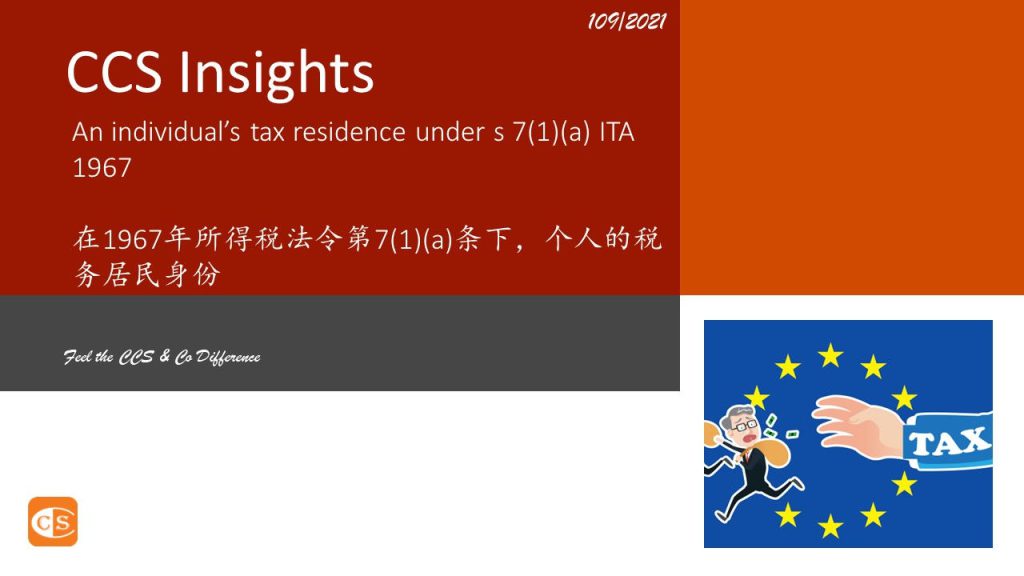
    1. Tax residents are often given preferential treatment over non-residents, therefore determining an individual’s residence for tax purposes is critical.

    2. Tax residents, for example, are entitled to personal tax rebates and reliefs, which do not apply to non-residents, and they pay graduated tax rates of 0–30% based on their chargeable income levels, whilst non-residents pay a flat tax rate of 30%.

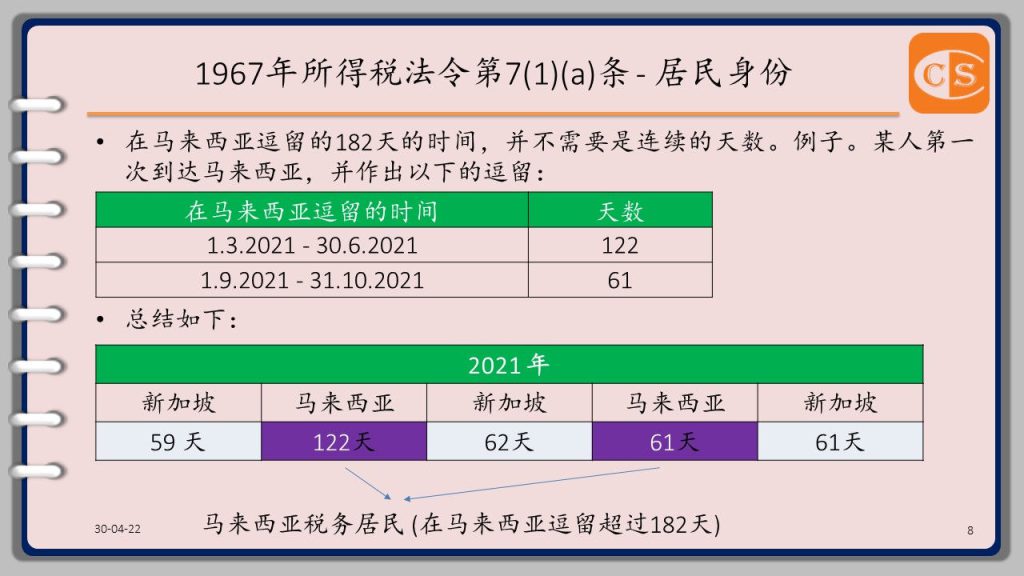
    3. The test of residence under s 7 of the Income Tax Act 1967 (ITA) is purely a quantitative one, based on the number of days an individual is present in Malaysia during a year of assessment.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1.以税收为目的确定一个人的居民身份是至关重要的,因为税务居民通常比非居民享有优惠待遇。

    2. 例如,税务居民有权享受个人退税 [Tax Rebates] 和减免,但这不适用于非居民。同时税务居民的税率是根据其课税收入水平 [chargeable income] 征税 0至30%,至于非居民的税率则统一,一律征税30%。

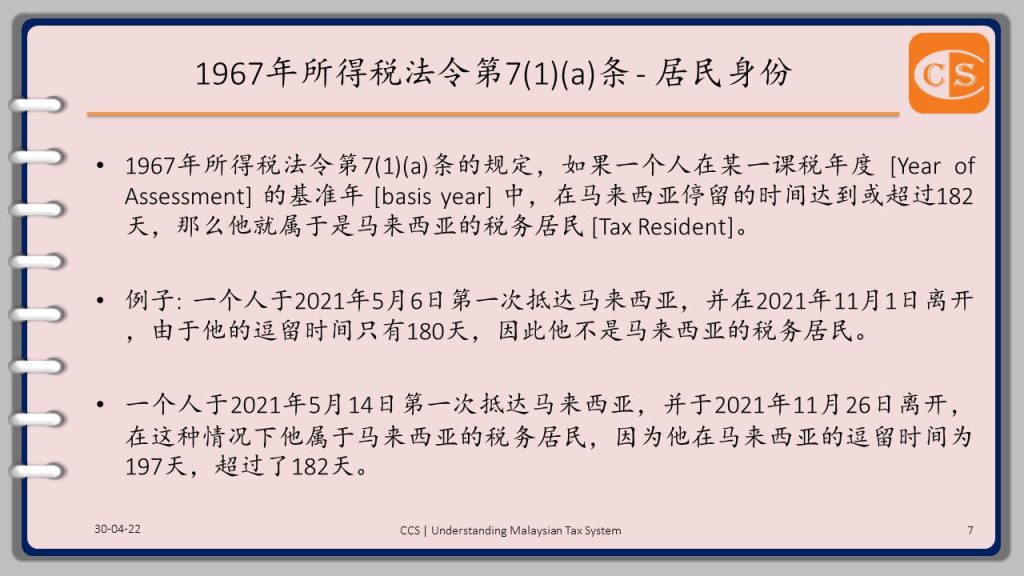
    3. 1967年所得税法令第7条规定的居民身份的鉴定,纯粹以定量为基础,是根据个人在一个课税年度中停留在马来西亚的天数。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    11
  • 9: The principle of Territorial cum Residence Jurisdiction

    9: The principle of Territorial cum Residence Jurisdiction

    The principle of Territorial cum Residence Jurisdiction – PDF

    1. The principle of Territorial cum Residence Jurisdiction refers to the taxation jurisdiction of a country that simultaneously exercises both Territorial [source jurisdiction] Jurisdiction and Residence Jurisdiction.

    2. It can be further divided into:

    👉 Territorial-Citizen Jurisdiction,

    👉 Territorial-Residence Jurisdiction; and

    👉 Territorial-Residence-Citizen Jurisdiction.

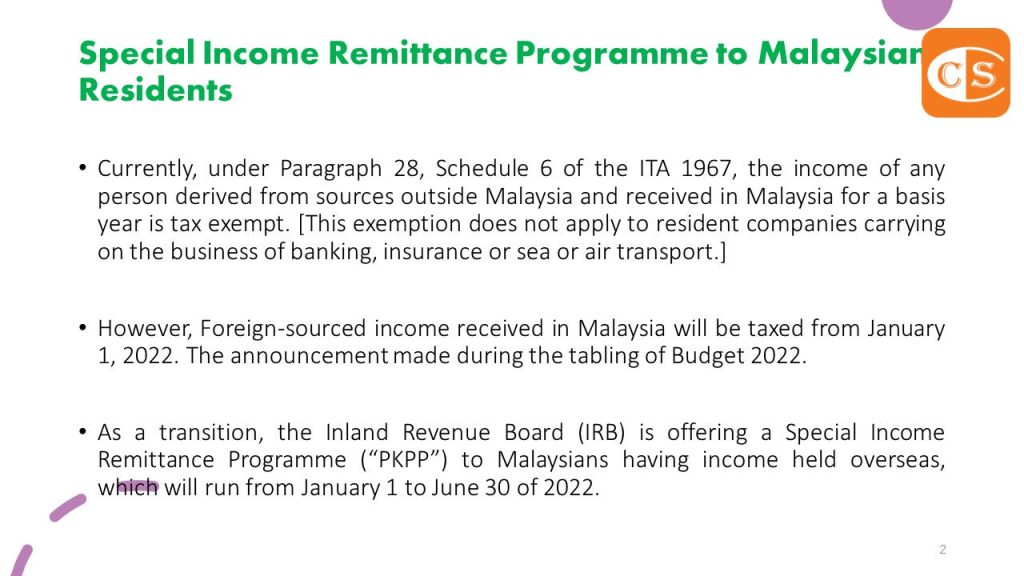
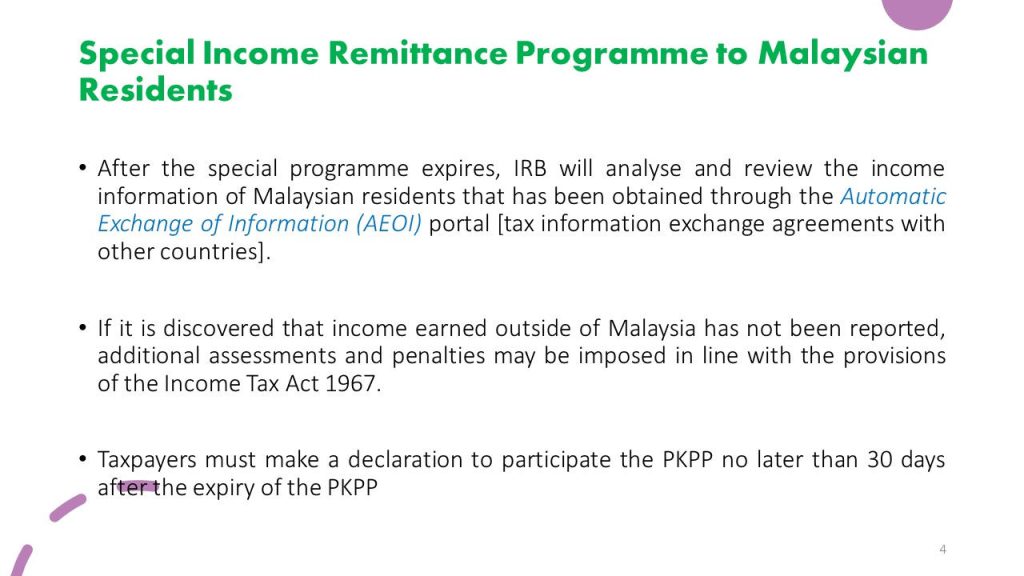
    3. Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement was made during the tabling of Budget 2022

    4. To download – www.ccs-co.com/publications

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 属地兼属人管辖原则,是指一个国家同时行使属地 [来源地管辖权] 管辖权和属人 [居民地管辖权] 管辖权的税收管辖权。

    2. 它又可分为:

    👉 属地兼公民管辖权;

    👉 属地兼居民管辖权;和

    👉 属地兼居民、公民管辖权三类。

    3. 从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    7
  • 11: Double Taxation vs Double Non-taxation

    11: Double Taxation vs Double Non-taxation

    Double Taxation vs Double Nontaxation – PDF

    1. If the conflicting claims for tax revenue based on residency and source are not addressed effectively, it would result in Double Taxation, which will stymie international companies and investment.

    2. While multinational businesses may suffer double taxes, they also have possibilities for international tax avoidance (sometimes referred to as Double Nontaxation).

    3. Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement made during the tabling of Budget 2022

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 对于收入来源的定义有冲突的国家,可能都会要求对相同的收入征税。除非得到令人满意的解决,否则基于居住地和来源地对税收主张的相互冲突将导致纳税人被双重征税,这会阻碍国际商业和投资。

    2. 虽然从事国际业务的人面临着被双重征税的可能性,但他们还是有国际避税的选择(有时也被称为“双重不征税”)。

    3. 从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    9
  • 12: The International Double Taxation – Legal

    12: The International Double Taxation – Legal

    The International Double Taxation – Legal – PDF

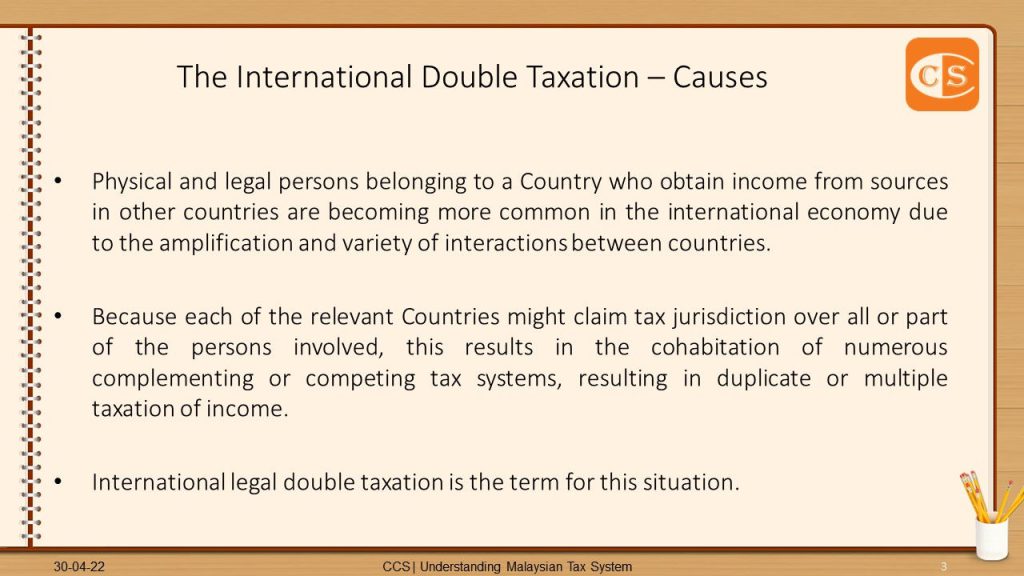
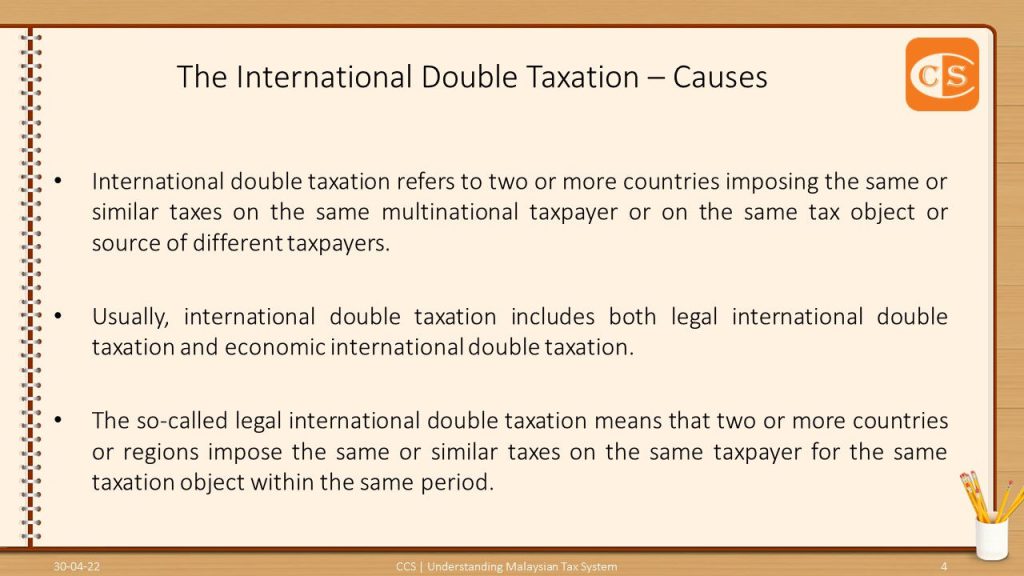
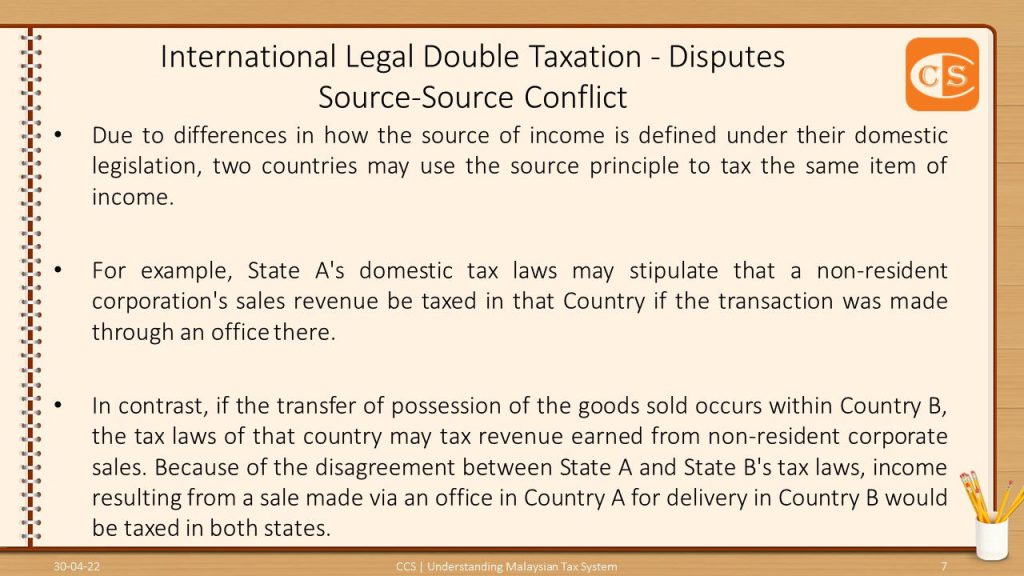
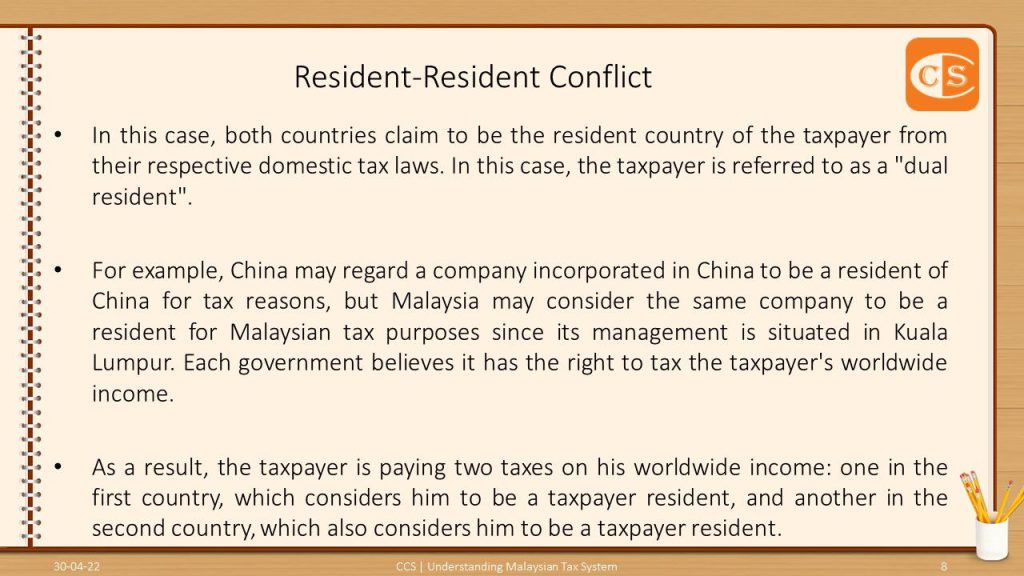
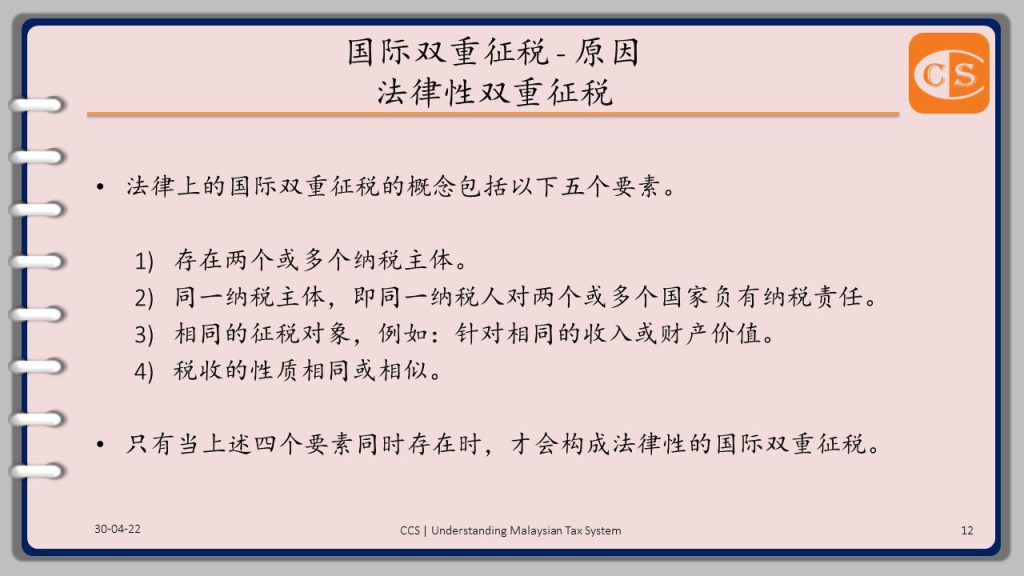
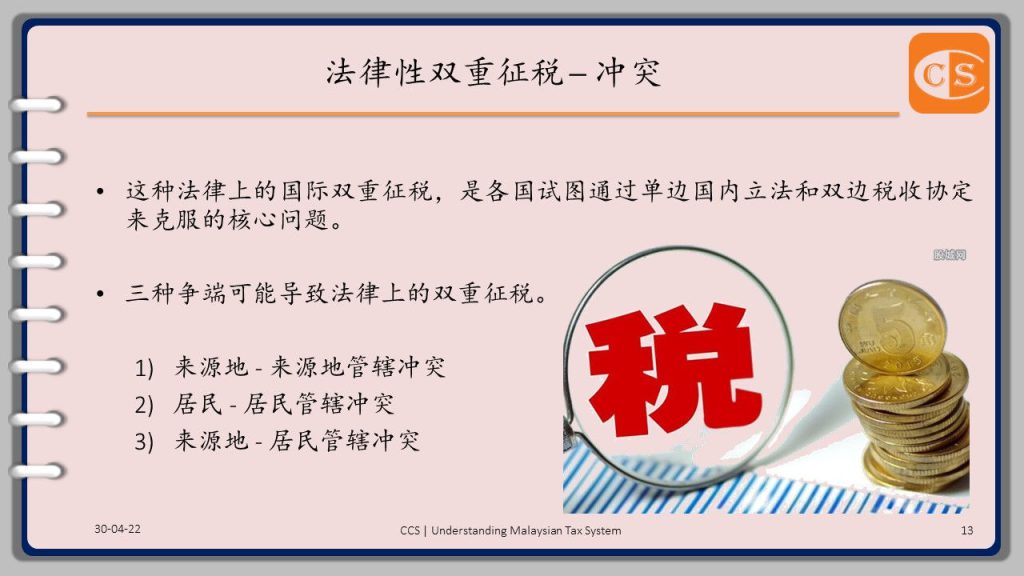
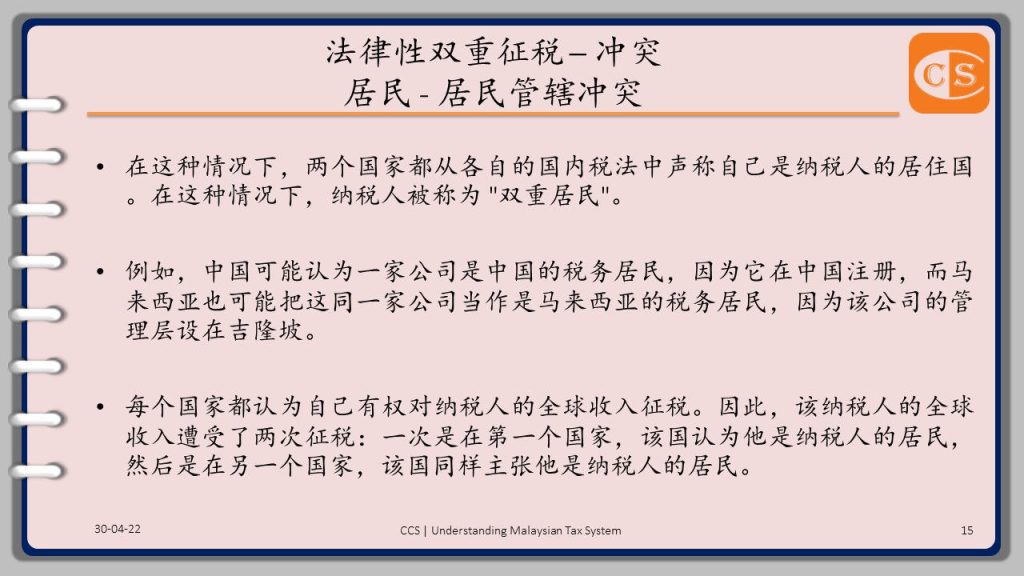
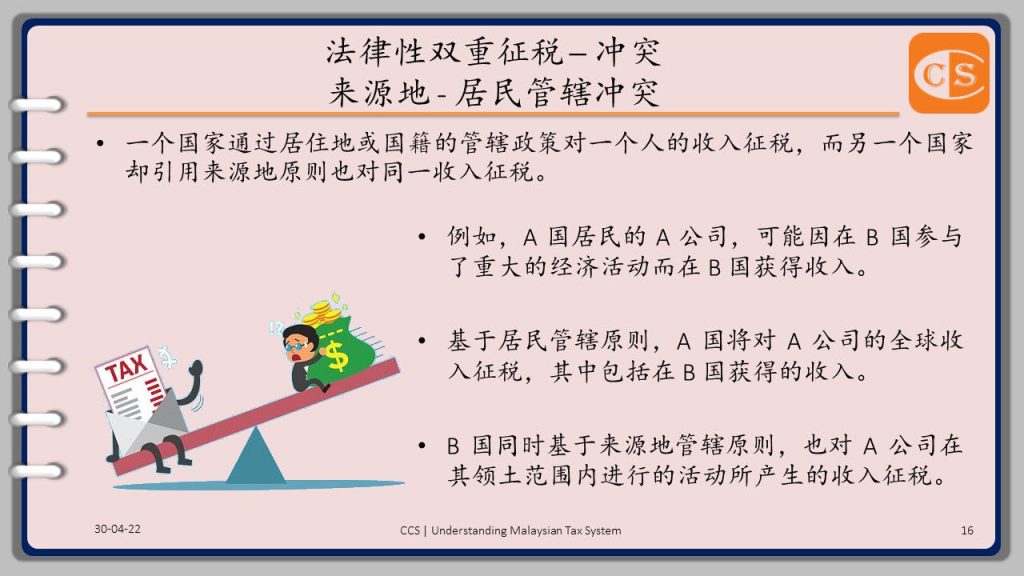
    1. Two basic concepts that are also essential reasons/causes of international juridical double taxation are at the heart of international taxation concerns.

    👉 The terms “source” and “residence” are used to describe these two concepts.

    👉 Both concepts are derived from laws in domestic tax legislation that discriminate between non-residents and residents.

    2. The first type of taxpayers has a limited nexus (relationship) with the country in issue, but the income they receive will have an economic link to the country in question and will originate there.

    👉 This government desires to tax this person, but only on the income that originated there (that has a source in this country)

    👉 this is known as source taxation, and it is also known as restricted tax obligation.

    3. Residents, on the other hand, have a close personal and economic relationship (nexus) with the country in the issue.

    👉 The government generally taxes the worldwide income of this type of taxpayer.

    👉 A practice is known as worldwide taxation, and sometimes known as unrestricted tax obligation.

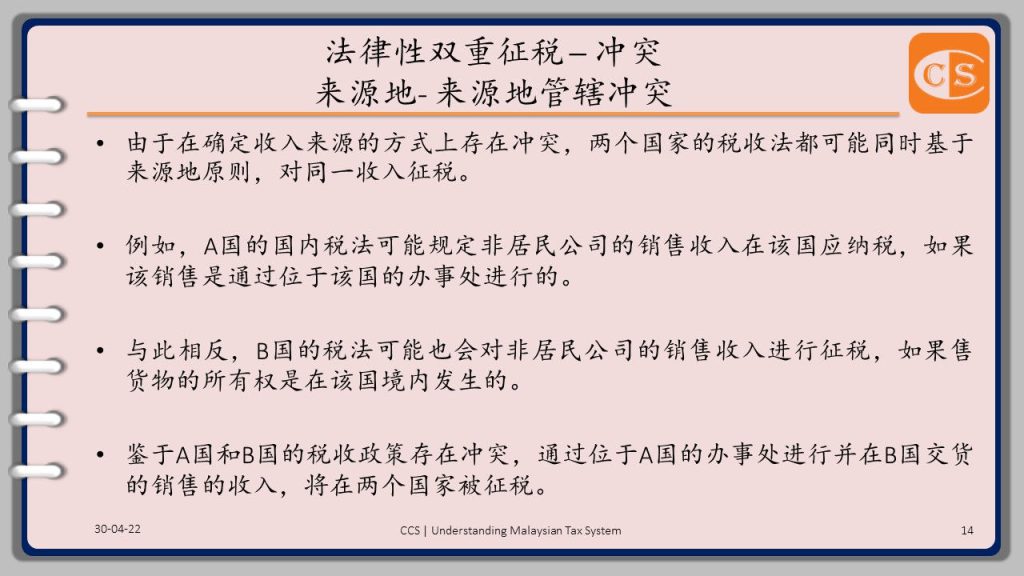
    4. Double taxation can occur in different situations due to the adoption of different tax policies.

    5. Foreign-sourced income received in Malaysia will be taxed from January 1, 2022. The announcement was made during the tabling of Budget 2022

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 两个基本概念,是国际司法双重征税的基本原因,也是国际税收问题的核心所在:

    👉 这两个概念分别被”来源地”和 “居住地”这两个词用以描述。

    👉 这两个概念都是国内税收立法用来对非居民和居民进行区分的法规。

    2. 第一种类型的纳税人与有关国家 [假设 M 国] 的关系有限,但他们获得的收入却与有关国家 [M 国] 有经济联系,并源自那里。

    👉 这个国家的政府 [M 国] 希望对这类型的个人征税,但只对源自该国 [M 国] 的收入(在 M 国有收入来源)征税

    👉 这被称为来源地管辖权,也被称为限制性纳税义务。

    3. 另一方面,“居民” [Residents] 则与有关国家有密切的个人和经济关系(联系)。

    👉 政府一般会对这类型的纳税人的全球收入征税。

    👉 这种做法被称为全球征税,有时也被称为不受限制的纳税义务。

    4. 双重征税可以因为采取不同的税收政策,在不同情况下发生。

    5. 从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。这是在提交2022年预算案时,政府所作出的宣布]

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    10
  • 13: Methods used by Resident Countries to Cope with Double Taxation

    13: Methods used by Resident Countries to Cope with Double Taxation

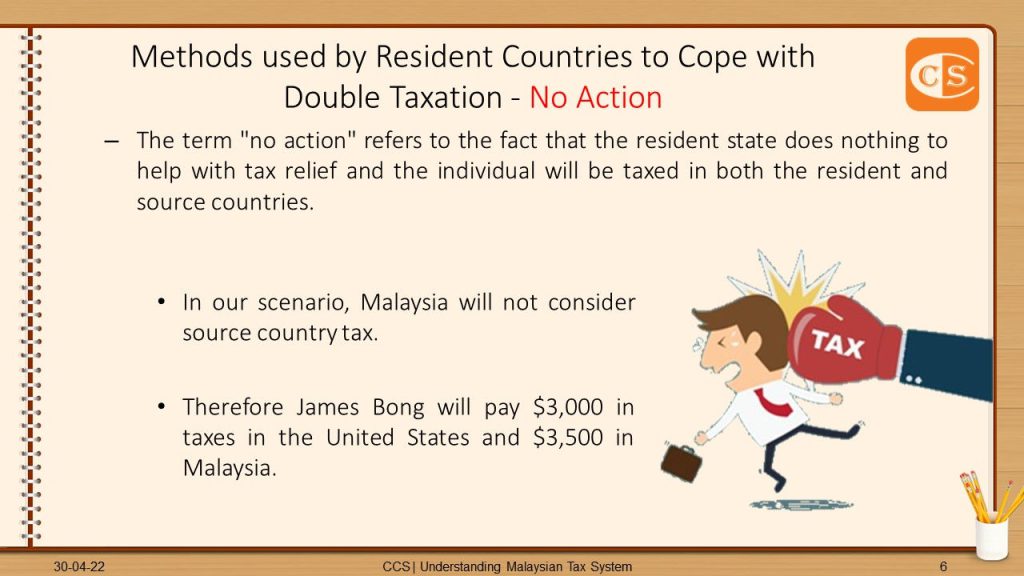
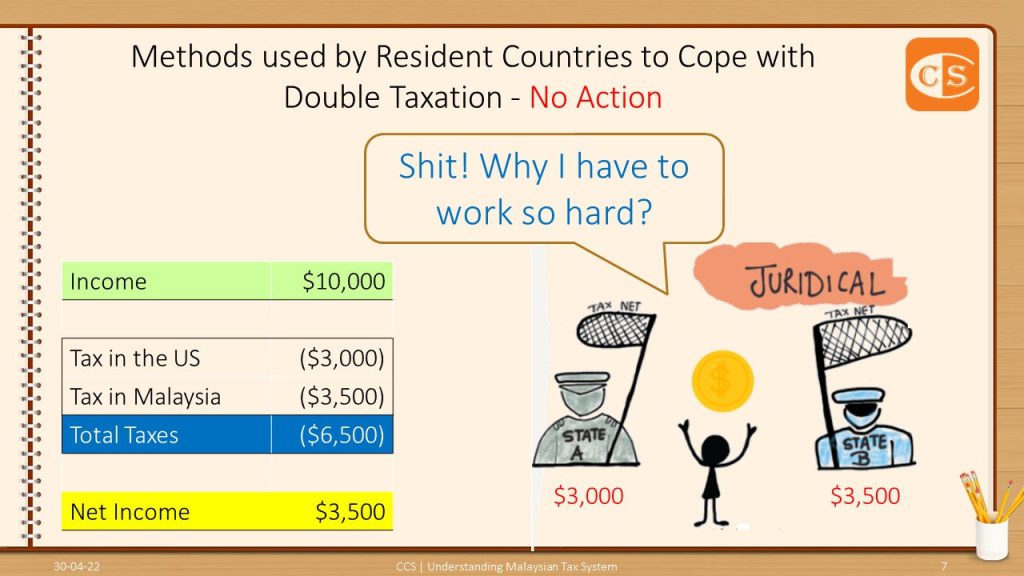
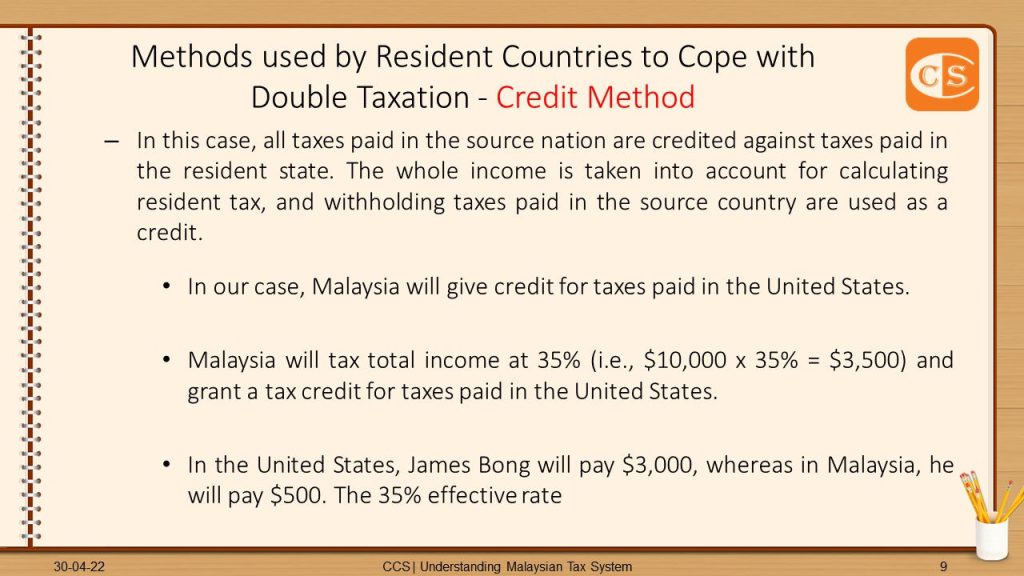
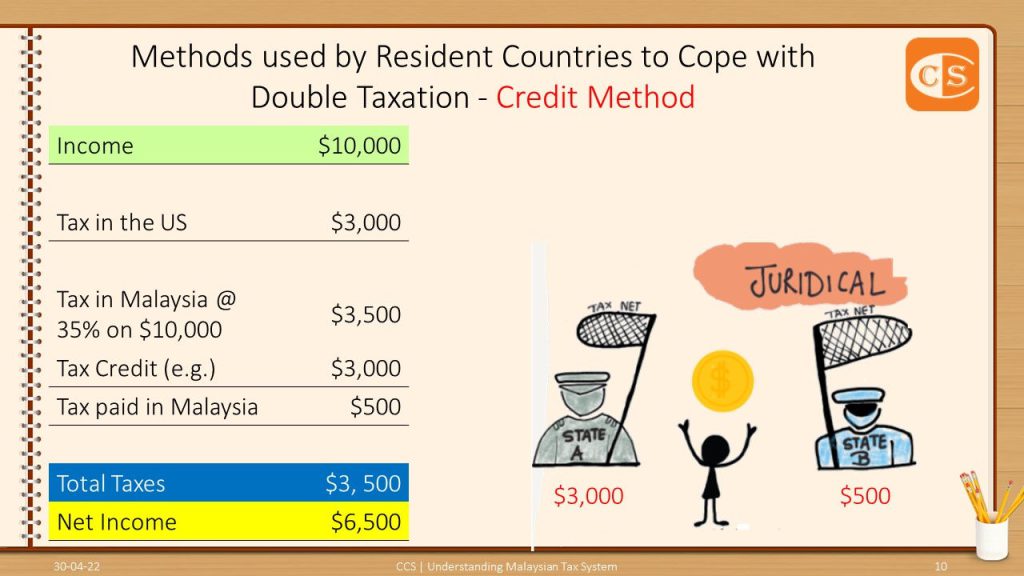
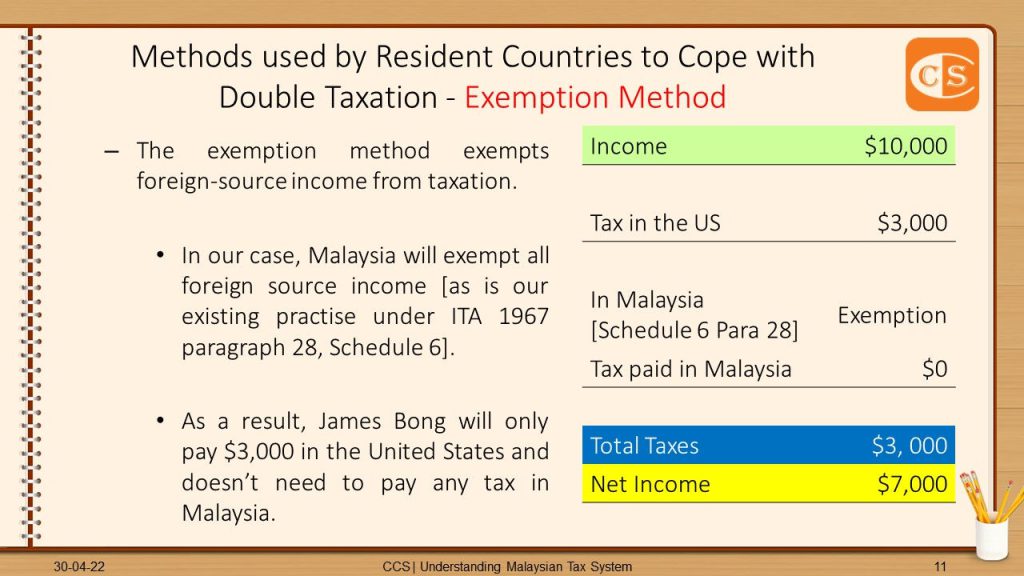
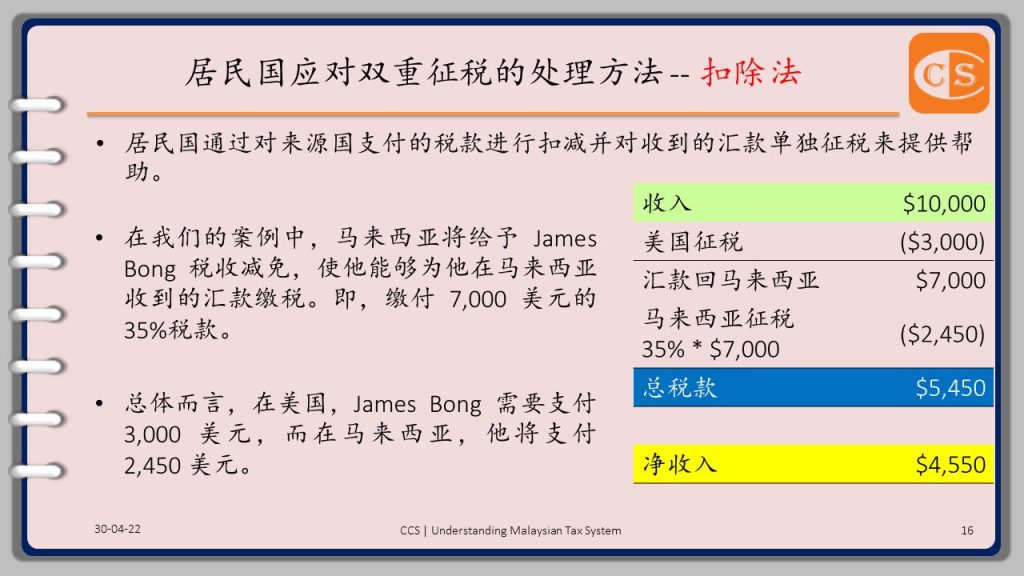
    1. Budget 2022 was tabled in Parliament on 29 October 2021, one of the amendments to the Income Tax Act 1967 is:

    👉 Foreign-sourced income received in Malaysia will be taxed from January 1, 2022.

    2. Then, everyone noticed a lot of relevant news or posts on social media

    3. I’m also keeping track of this news, but I’ve discovered that there aren’t many individuals who grasp this legal change.

    4. Everyone undoubtedly understands that money brought back from other countries will have to be taxed starting next year, but they don’t know how it will work.

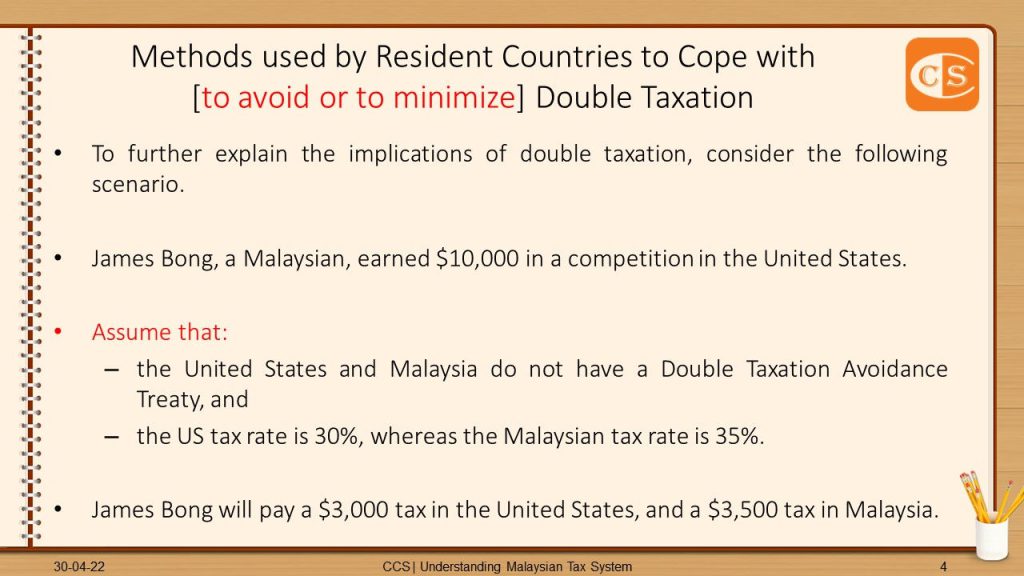
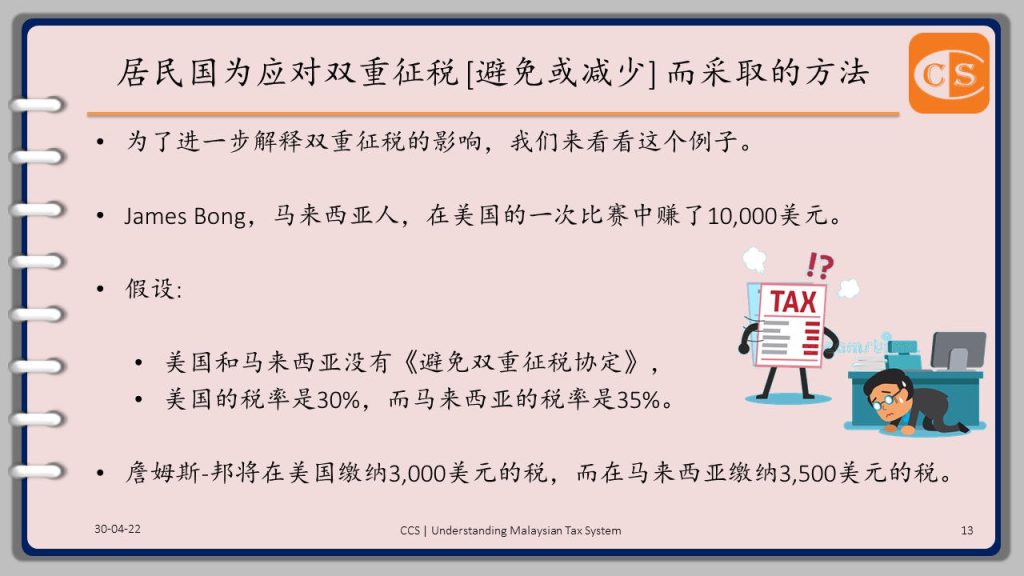
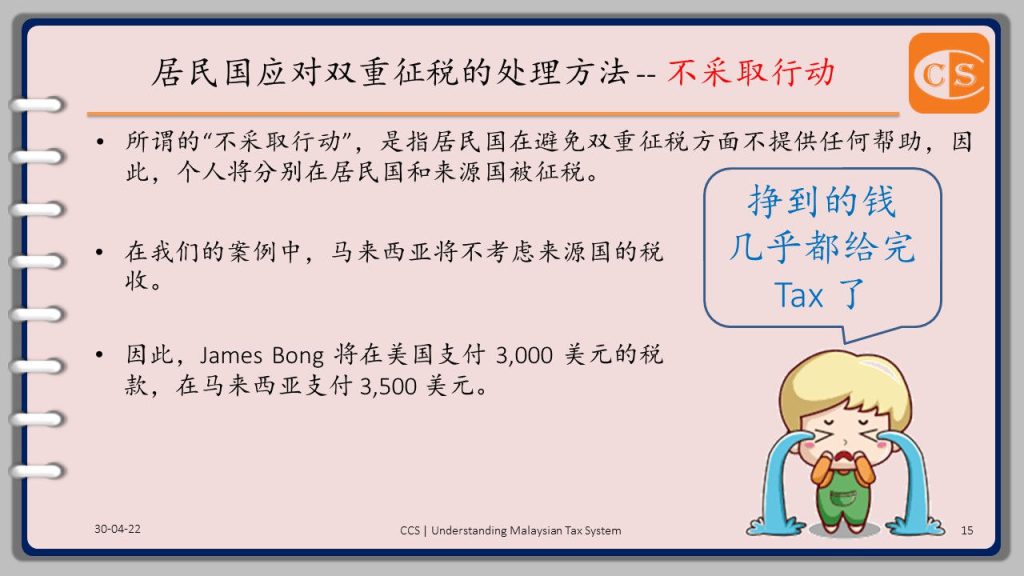
    5. Some individuals are even concerned about being taxed twice.

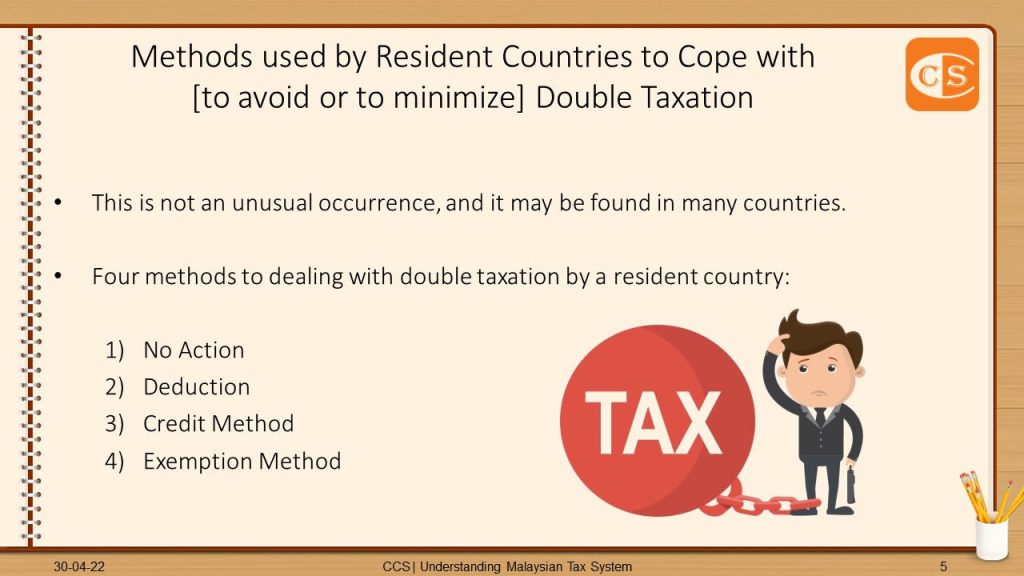
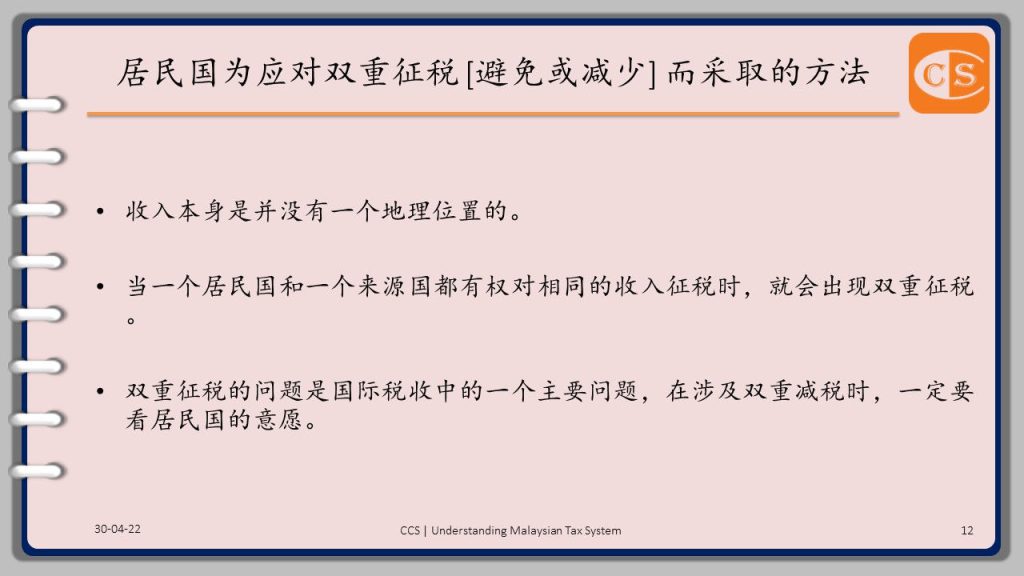
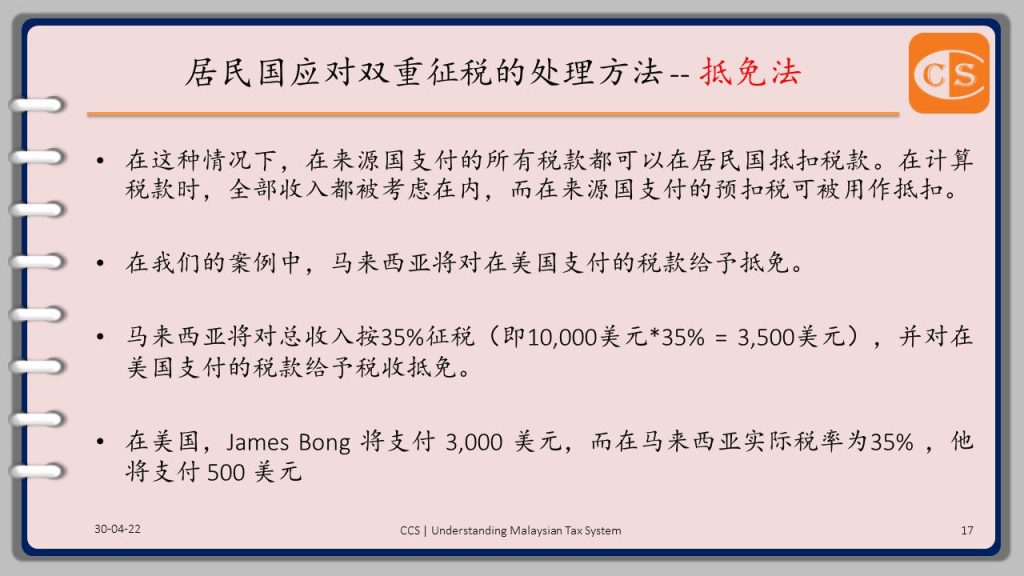
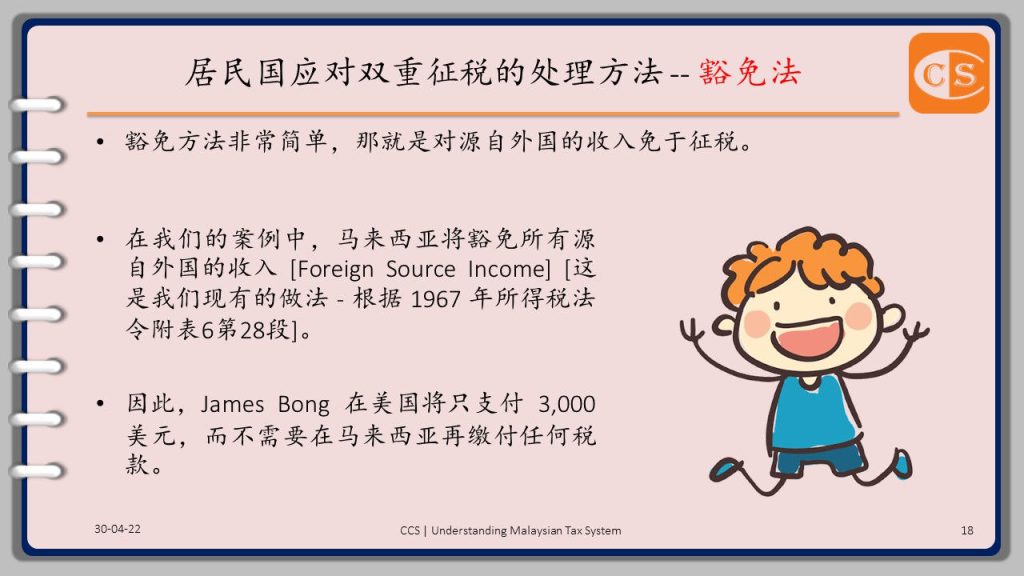
    6. Today, I’ll discuss the methods that a resident country might use to avoid double taxation.

    7. In fact, on this issue, I’ve authored a number of articles:

    👉 If you are thinking to master this subject, I would recommend that you read all of the articles I’ve published thoroughly.

    👉 If you are having trouble digesting and understanding it, I recommend that you contact me or your tax professional for assistance.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 在提交2022年预算案时,政府所作出的宣布 ; 从2022年1月1日起,在马来西亚获得的来源自国外的收入将被征税。

    2. 一时间,大家都在社交媒体上看到许多相关的报导或分享

    3. 我也都有在跟进这些报导,然而我却发现,能够读懂这项法律修订的并不多

    4. 截至目前为止,大家只是大概知道,从明年开始,从外国带回来的钱,需要征税,但是对于实际上的操作并不了解

    5. 甚至也有人在担心,是否会双重被征税

    6. 今天我就来和大家谈谈,一般居民国应对双重征税的态度及方法 7。 针对这个课题,我已经写了相当多的文章:

    👉 如果你想掌握这门知识,我建议你把我所写过的文章细读

    👉 如果你没能读懂,那么我建议你有需要的时候,可以找我或你们的税务顾问咨询

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    11
  • 14: The International Double Taxation – Economic

    14: The International Double Taxation – Economic

    The International Double Taxation – Economic – PDF

    1. Yesterday, George Tan enquired, “How will future dividends received from Singapore be taxed?”

    2. To be honest, this is an interesting question that cannot be answered succinctly in a few lines.

    3. The taxation of dividends has its origins in the classical tax system, which in effect taxed corporate profits twice: 👉 Once at the corporate level, and

    👉 once at the shareholder level, following the distribution of the company’s after-tax profits to shareholders in the form of dividends.

    4. This is referred to as “economic double taxation” in terms of taxation (as opposed to the legal double taxation discussed earlier, see my previous article for more information).

    5. Malaysia moved to a single-tier system in 2008, replacing the imputation system.

    6. The taxes of resident companies is considered as Final Tax under the single-tier system. As a result, dividends received by shareholders are tax-free and do not need to be declared under the single-tier system.

    7. Please be aware that, as proposed in Budget 2022, foreign-sourced income (FSI) received in Malaysia will be subject to taxation beginning January 1, 2022.

    8. Dividends received in Malaysia from overseas sources are not exempt from taxes in this circumstance. This is due to the repeal of the tax exemption in paragraph 28 of Schedule 6 of the Income Tax Act of 1967.

    9. When I get the time, I will slowly explain everything in detail.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 昨天 George Tan 问:日后从新加坡收到的股息,税务上究竟怎样处理?

    2. 这确实是一个好问题,也非三言两语可以清楚地回答

    3. 股息的征税起源于古典税收制度,实际上是对公司利润进行了两次征税:

    👉 一次是在公司层面;

    👉 另一次是在股东层面,即公司税后利润以股息的形式向股东分配之后

    4. 在税收上,这就是所谓的“经济性双重征税”(有别于之前所讨论的法律性双重征税,可以看回我之前的文章,以了解更多)。

    5. 马来西亚在2008年,把原有的估算系统 [imputation system] 以单层系统 [single-tier system] 取代。

    6. 在单层系统 [single-tier system] 制度下,居民公司的税收被视为最终税 [Final Tax]。因此,在单层制度下,股东收到的股息是免税的,并不需要再报税。

    7. 然而请注意,正如2022年预算案所提呈的,从2022年1月1日起在马来西亚收到源自国外的收入 [ foreign-sourced income, FSI] 将会被征税。

    8. 在这种情况下,在马来西亚收入来自国外的股息,不排除需要征税。因为1967年所得税法令第6附表第28段的免征税条款,将被删除

    9. 有机会,我将会慢慢深入讲解

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    12
  • 10: Special Income Remittance Programme to Malaysian Residents

    10: Special Income Remittance Programme to Malaysian Residents

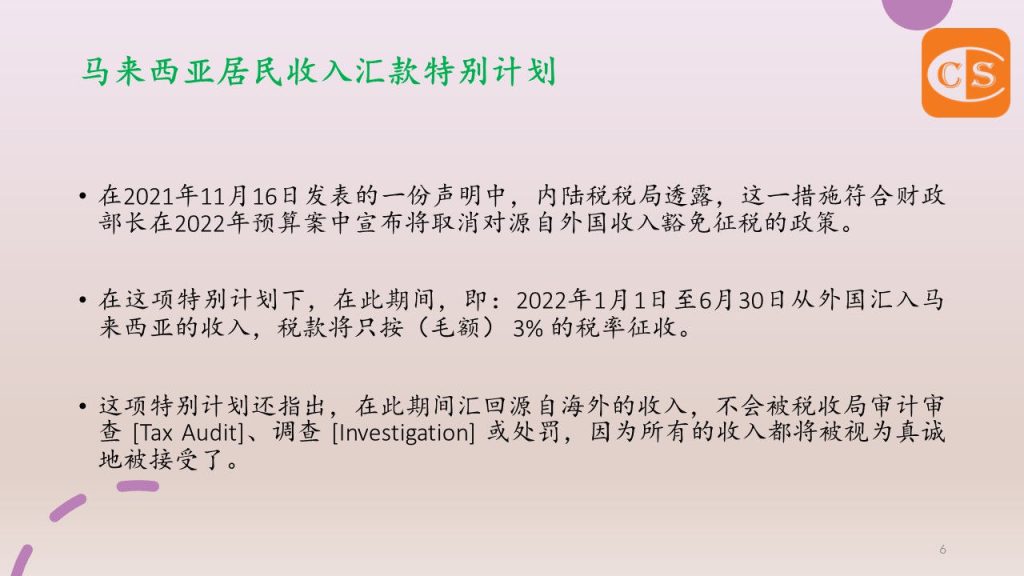
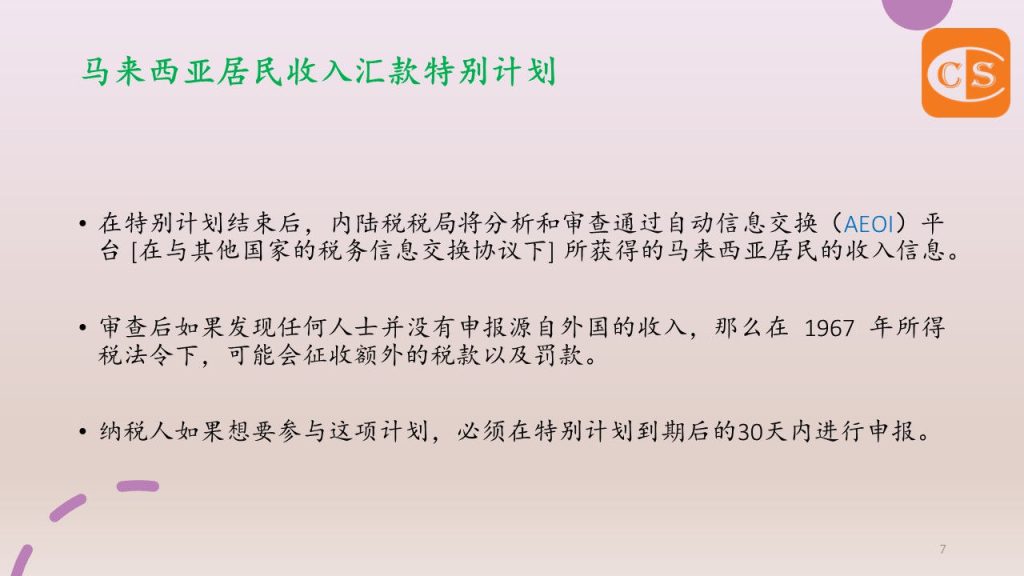
    1. In a statement issued on November 16, 2021, IRB said this Special Income Remittance Programme to Malaysian Residents (“PKPP” was in line with Finance Minister Tengku Datuk Seri Zafrul Tengku Abdul Aziz’s announcement in the Budget 2022 that the tax exemption for foreign sources of income will be removed.

    2. According to the programme, income brought in during the PKPP period [from January 1 to June 30 of 2022] :

    👉 will be taxed at a rate of 3% (gross),

    👉 with no Tax Audit, investigation, or penalty applied on income brought in during that period, since all income will be received in good faith.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 在2021年11月16日发表的一份声明中,内陆税税局透露,这一措施符合财政部长在2022年预算案中宣布将取消对源自外国收入豁免征税的政策。

    2. 在这项特别计划下,在此期间,即:2022年1月1日至6月30日从外国汇入马来西亚的收入,税款将只按(毛额) 3% 的税率征收。

    3. 这项特别计划还指出,在此期间汇回源自海外的收入,不会被税收局审计审查 [Tax Audit]、调查 [Investigation] 或处罚,因为所有的收入都将被视为真诚地被接受了。

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy
    5
  • 1: What Is International Tax?

    1: What Is International Tax?

    What Is International Tax? – PDF

    1. THE Budget 2022 proposed that foreign-sourced income received in Malaysia would be subject to income tax in Malaysia with effect from Jan 1, 2022
    2. For convenience, we use the term “international tax” in our sharing, and “international tax laws” are the laws of a particular country that deal with the international aspect of income tax.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022年预算案提出:

    👉 从2022年1月1日起,

    👉 在马来西亚收到的源自外国的收入

    👉 将在马来西亚缴纳所得税。

    2 . 为了方便起见,我们在分享中使用了 “国际税收”一词,”国际税法”是特定国家应对国际间的所得税法。

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    8
  • 2: International Organizations involved In International Tax – OECD

    2: International Organizations involved In International Tax – OECD

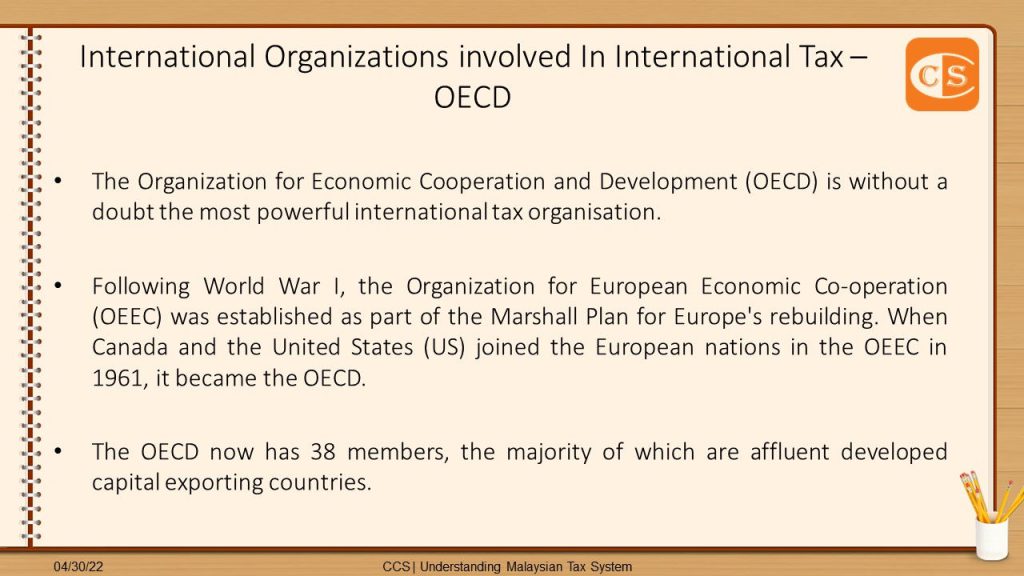
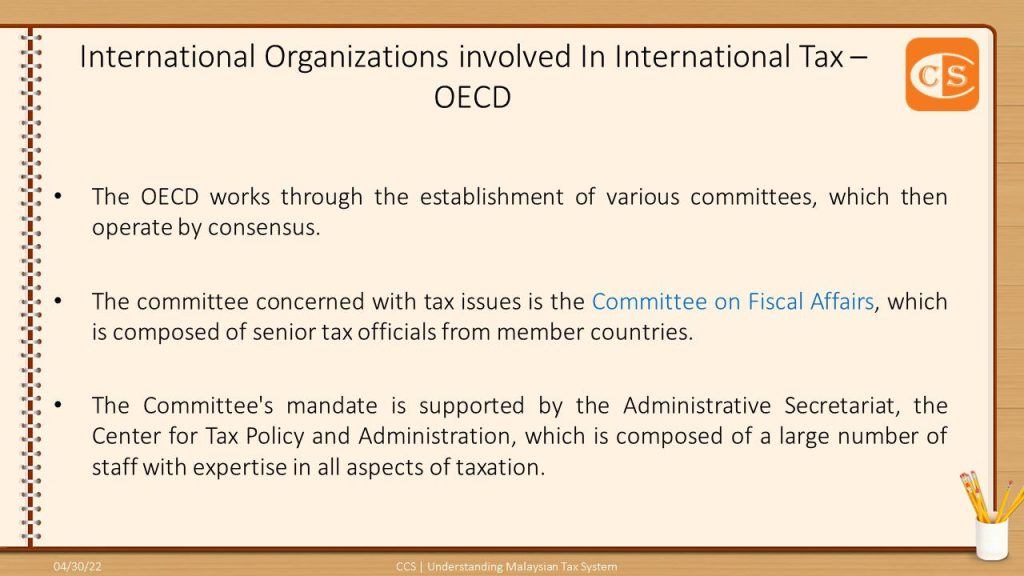
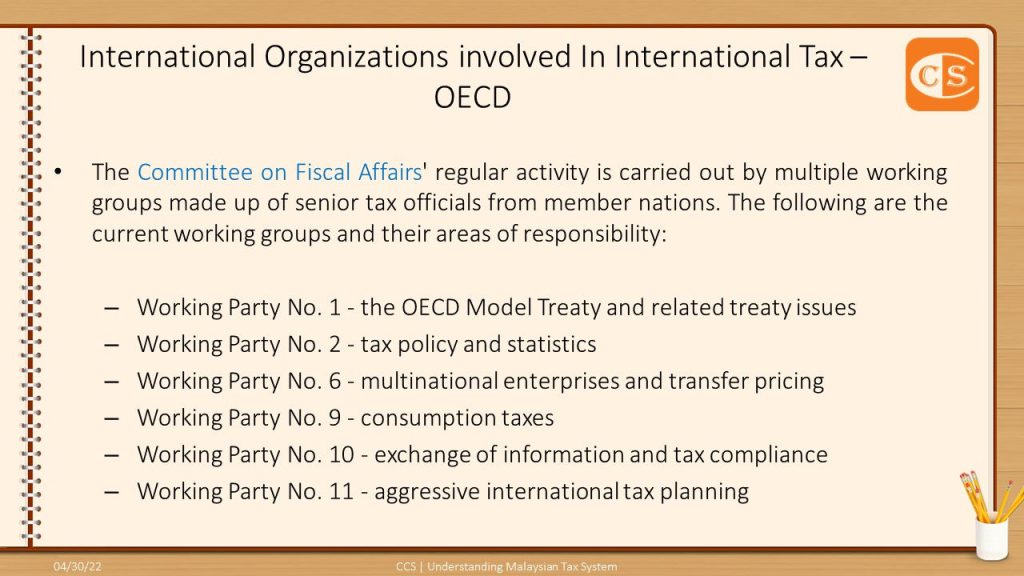
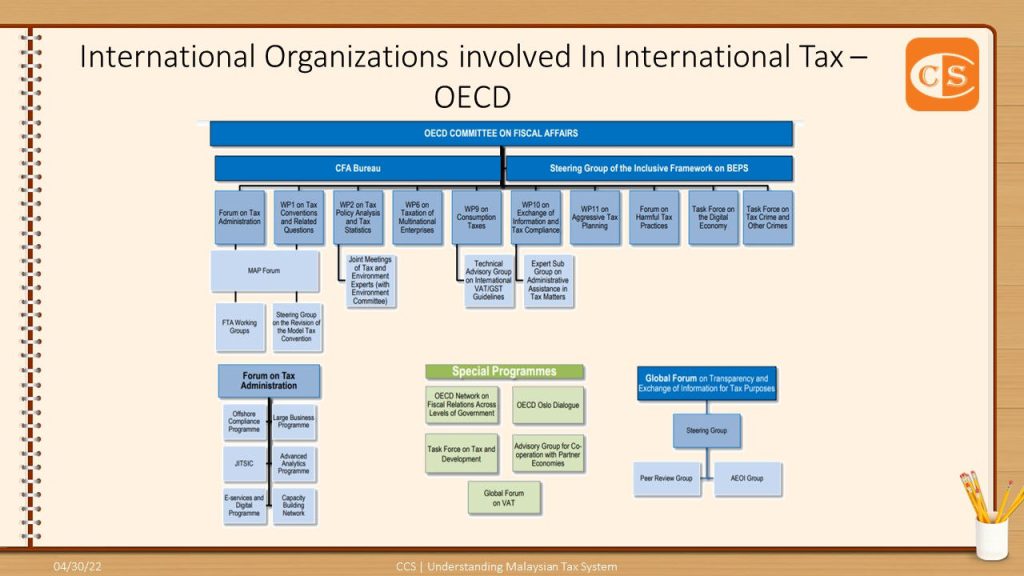
    1. Despite the fact that sovereign nation-states are largely responsible for creating the rules of the international tax system through domestic law and tax treaties, other international organisations play a significant role in international tax.

    2. The OECD, the International Monetary Fund (IMF), the United Nations (UN), and the World Bank Group (WGB) are the four primary international organisations involved in international taxation.

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

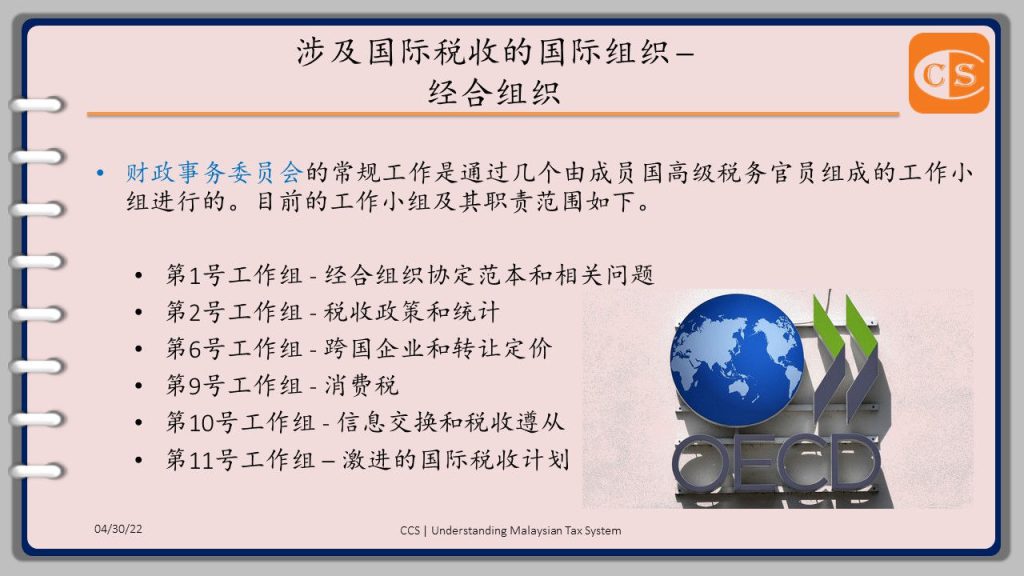
    1. 尽管主权国家在很大程度上负责通过国内法律和税收协定建立国际税收制度的规则,但其他国际组织在国际税收中也发挥着重要作用。

    2. 经合组织 [OECD]、国际货币基金组织 [IMF]、联合国 [UN] 和世界银行集团 [WBG] 是涉及国际税收的四个主要国际组织。

    #税法之道博大精深,#建议大家深度学习

    🌸🌸🌸🌸🌸🌸🌸🌸🌸🌸

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #InternationalTax #国际税收系列

    1. Issue No. 103/2021: Finance Bill 2021 Highlights – No more Exemption on Foreign Sourced Income remitted to Malaysia [2021年财政法案亮点 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/eCS24pA3

    2. What Is International Tax? [什么是国际税收] https://lnkd.in/eiuiC4f4

    3. International Organizations involved In International Tax – OECD [涉及国际税收的国际组织 – 经合组织] https://lnkd.in/e_uDSM-S

    4. International Organizations involved In International Tax – G 20 [涉及国际税收的国际组织 – G 20] https://lnkd.in/ehZnNjwh

    5. International Organizations involved In International Tax – G20/OECD Inclusive Framework, World Bank Group & IMF [涉及国际税收的国际组织] https://lnkd.in/eKdW5UdE

    6. International Organizations involved In International Tax – The UN [涉及国际税收的国际组织] https://lnkd.in/ermXNTq2

    7. Residence Jurisdiction vs. Source Jurisdiction [来源地管辖权 vs. 居民管辖权] https://lnkd.in/eCit6_dc

    8. Jurisdiction to Tax – The logic behind “Source Jurisdiction / Territorial Concept.” [税收管辖区 – “来源地管辖权”背后的逻辑] https://lnkd.in/eyp-SY_k

    9. Jurisdiction to Tax – The logic behind “Residence Jurisdiction.” [税收管辖区 – “居民地管辖权”背后的逻辑] https://lnkd.in/eyzTrxpN

    10. The Principle of Territorial-Residence Jurisdiction [属地兼属人管辖原则] https://lnkd.in/ehXXBXmd

    11. Special Income Remittance Programme to Malaysian Residents – No more Exemption on Foreign Sourced Income remitted to Malaysia [马来西亚居民收入汇款特别计划 – 源自外国汇入马来西亚的收入,不再获得豁免] https://lnkd.in/ez4bpY3W

    12. Double Taxation vs. Double Non-Taxation [双重征税 vs. 双重不征税] https://lnkd.in/etfYgkXK

    13. Legal International Double Taxation [法律性国际双重征税] https://lnkd.in/e8zX9kP2

    14. Methods used by Resident Countries to Cope with Double Taxation [居民国应对双重征税的方法] https://lnkd.in/e77aSCnE

    15. Economic International Double Taxation [经济性国际双重征税] https://lnkd.in/ewWDxjZ3

    16. Income Tax Treatment of Pensions (Provident Fund) [退休金或公积金@所得税处理] https://lnkd.in/eJVNzteR

    17. Defining Residence [居民身份@界定] https://lnkd.in/eHfK49iB 18. An Individual’s Tax Residence under s 7(1)(a) ITA 1967 [1967年所得税法令第7(1)(a)条 @ 居民身份] https://lnkd.in/eJHAdE_D

    19. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 [1967年所得税法令第7(1)(b)条 @ 居民身份] https://lnkd.in/eT5HcfWH

    20. An Individual’s Tax Residence under s 7(1)(b) ITA 1967 -Temporary Absences [1967年所得税法令第7(1)(b)条 @ 居民身份 – – 暂时性不在] https://lnkd.in/erW_Jxwd

    21. Tax Residence under s 7(1)(c) ITA 1967 [1967年所得税法令第7(1)(c)条 @ 居民身份] https://lnkd.in/eMw82gE9

    22. Tax Residence under s 7(1)(d) ITA 1967 [1967年所得税法令第7(1)(d)条 @ 居民身份] https://lnkd.in/eeYZy7Nq

    23. Tax Residence under s 7(1A)ITA 1967 – A ‘day.’ [1967年所得税法令第7(1A)条 @ 居民身份: 一天的定义] https://lnkd.in/eS4JVgCr

    24. Move to tax Foreign-Sourced Income in Malaysia is not a surprise [马来西亚对源自国外的收入征税 的举措并不令人意外] https://lnkd.in/e-kqYmuq

    25. Special Income Remittance Programme to Malaysian Residents [源自外国汇入马来西亚的收入 特别报税方案] https://lnkd.in/eqhVhXda

    26. Work on board, e.g. as a sailor, Subject to Tax? [在船上工作,如水手 中 Tax 吗] https://lnkd.in/ee6bgchw

    27. Work onboard – Deeming Provisions of Employment Income [船员 – 就业收入认定条款 ] https://lnkd.in/eZv55cdV

    28. What Exactly is Considered a Taxable Remittance: 1 – Introduction

    [究竟什么才会被认为是”应税汇款”: 1 – 概述] https://lnkd.in/eKVzZqeQ

    29. What Exactly is Considered a Taxable Remittance: 2 – Definition & Examples of Remittances

    [究竟什么才会被认为是”汇兑”: 2 – “汇兑”的定义及例子] https://lnkd.in/ewmKMjC5

    30. What Exactly is Considered a Taxable Remittance: 3 – How do I know What Income or Gains I Have Remitted?

    [究竟什么才会被认为是”汇兑”: 3 – 我如何知道 我汇兑了哪些收入或收益?] https://lnkd.in/esiM6_ZX

    31. What Exactly is Considered a Taxable Remittance: 4 – Should I Remit or Not?

    [究竟什么才会被认为是”汇兑”: 4 – 我是否应该汇兑?] https://lnkd.in/exSEf5nq

    32. Tax Residents to be exempted from tax on the foreign-sourced income until Dec 31, 2026 [税务居民源自国外的收入将被免征税至2026年12月31日] https://lnkd.in/eAu5rcJK

    33. Termination of Special Income Remittance Program [最新消息 – 源自海外收入特别汇款计划] https://lnkd.in/euW8CJzm

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    #当你以我们的视频及刊物上的内容作为税务事务处理的参考时,你需要:

    ✅ 查询相关资料是否依然合时、准确和完整;和

    ✅ 寻求本身独立的专业意见,因为各别案例所涉及的范围和层面皆不同。 When you apply the content in our videos and publications as a reference, you need to:

    🅾️ check the information contained therein, whether it’s up-to-date, accurate and complete, and

    🅾️ seek your independent professional advice because the scope and extent involved in each case are different.

    🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳🌳

    👉 Stay in touch with us

    1. Website ✍️ https://www.ccs-co.com/

    2. Telegram ✍️ http://bit.ly/YourAuditor

    3. Instagram ✍ http://tiny.cc/rojzrz

    4. Blog ✍ https://lnkd.in/e-Pu8_G

    5. Google ✍ https://lnkd.in/ehZE6mxy

    6