Day: October 16, 2026

  • Budget 2027: Could Higher Preferential Tax Rate Thresholds Benefit MSMEs?

    Budget 2027: Could Higher Preferential Tax Rate Thresholds Benefit MSMEs?

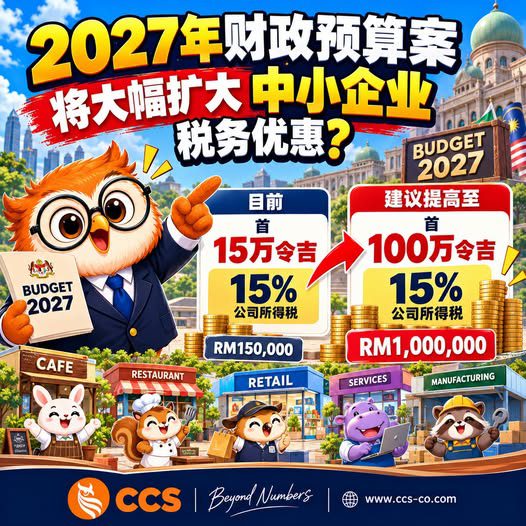
    Could Budget 2027 bring significant tax relief for micro, small and medium-sized enterprises (MSMEs)?

    If the 15% preferential tax rate threshold were increased from the current first RM150,000 of chargeable income to the first RM1 million, the improvement to MSMEs’ cash flow could be substantial.

    However, business owners should not celebrate just yet. The increase to RM1 million is a proposal, not an implemented tax rate. Public information indicates that the Government is collecting and assessing proposals for Budget 2027, and suggestions from industry are not consistent. For example, some have proposed extending the 15% rate to the first RM500,000 rather than RM1 million.

    The Government’s Pre-Budget Statement identifies strengthening MSMEs, easing business pressures and supporting the growth of local businesses as Budget 2027 priorities. The final position should be confirmed by the measures formally announced in the Budget.

    For now, the most accurate summary is: an increase from RM150,000 to RM1 million may be hoped for, but it should not be treated as approved.

    For business owners, the key question is not simply whether the rate will be 15%, but how much chargeable income that rate will apply to.

    Budget 2027:中小企业会迎来大幅减税吗?

    《2027年财政预算案》会否为微型、中小型企业(MSME)带来显著的税务减负?

    如果15%的优惠税率适用门槛,从目前首RM150,000课税收入大幅提高至首RM100万,中小企业的现金流改善可能会相当明显。

    不过,企业负责人暂时还不宜急着庆祝。将门槛提高至RM100万目前仍属建议,并非已经落实的税率。公开资料显示,政府正在收集及评估Budget 2027相关建议,而业界提出的方案也不完全一致。例如,有建议将15%税率的适用范围扩大至首RM500,000,而非RM100万。

    政府的《预算前声明》(Pre-Budget Statement)已将强化MSME、减轻营商压力及支持本地企业成长列为Budget 2027的重点方向。最终安排仍应以预算案正式公布的措施为准。

    现阶段最准确的说法是:RM150,000提高至RM100万可以期待,但不能视为已经通过。

    对企业负责人来说,真正值得关注的不只是税率是否为15%,而是这项税率究竟适用于多少课税收入。
  • Personal Tax Relief: Will the RM9,000 Limit Increase in Budget 2027?

    Personal Tax Relief: Will the RM9,000 Limit Increase in Budget 2027?

    The personal tax relief limit has remained at RM9,000 since 2010. While prices have risen over the years, this limit has stayed unchanged.

    Will Budget 2027 finally bring an increase? Could the limit rise to RM12,000 or RM15,000—or remain at RM9,000?

    个人税务减免:RM9,000上限会在Budget 2027提高吗?

    个人税务减免上限自2010年以来一直维持在RM9,000。多年来物价不断变化,这项上限却始终没有调整。

    《2027年财政预算案》会否终于提高这项减免?上限可能调至RM12,000或RM15,000,还是继续维持RM9,000?

  • Budget 2027: Proposed Minimum Wage Increase to RM2,000 and What It Means for Businesses

    Budget 2027: Proposed Minimum Wage Increase to RM2,000 and What It Means for Businesses

    Budget 2027 proposes increasing the minimum wage from RM1,700 to RM2,000 a month. This would be an increase of RM300 per employee, or approximately 17.6%.

    The proposal also provides an adjustment period for micro and small enterprises (MKS) with sales revenue below RM50 million, which would be exempt from this increase. However, exemption from the proposed increase does not exempt an employer from complying with the existing RM1,700 minimum wage requirement.

    What Could the Increase Mean for Employers?

    For a business with 20 employees currently earning RM1,700 each, increasing their wages to RM2,000 would mean an additional RM300 per employee:

    • Monthly increase: 20 employees × RM300 = RM6,000

    • Annual increase: RM6,000 × 12 = RM72,000

    This calculation does not include any corresponding increase in employer contributions to EPF, SOCSO, EIS or other related employment costs.

    The proposed increase is also a reminder that businesses cannot rely indefinitely on low wages to remain competitive. Employers may need to review their processes, consider investment in automation, provide employee training, and reassess pricing, productivity and their business models.

    The adjustment period is an opportunity for businesses to plan ahead—not simply to delay action. Employees may see an additional RM300 a month, while employers need to consider the increase together with related employment costs. A key question for businesses is how to enable each employee to contribute greater value.

    CCS | Beyond Numbers

    Budget 2027:最低薪金拟提高至RM2,000,企业应如何应对?

    《2027年财政预算案》提出将最低薪金从每月RM1,700提高至RM2,000,每名员工每月增加RM300,涨幅约为17.6%。

    提案同时为销售收入低于RM5,000万的微型及小型企业(MKS)提供调整空间,这类企业可获豁免适用本次调高措施。不过,获豁免于拟议的调薪措施,并不代表雇主可以不遵守现行每月RM1,700的最低薪金规定。

    调高最低薪金对雇主的影响

    假设一家企业有20名员工,目前每人月薪为RM1,700,若全部调整至RM2,000,每名员工每月将增加RM300的薪资成本:

    • 每月增加:20名员工 × RM300 = RM6,000

    • 每年增加:RM6,000 × 12 = RM72,000

    上述计算尚未包括雇主EPF、SOCSO、EIS等相关供款或其他雇佣成本可能产生的增幅。

    拟议的最低薪金调整也提醒企业,不能长期依靠低薪维持竞争力。雇主可能需要改善流程、考虑投资自动化、加强员工培训,并重新检视定价、生产效率及商业模式。

    调整期是企业提前规划的机会,而不只是延后采取行动。员工看到的是每月增加RM300;雇主则需要将薪资增幅与相关雇佣成本一并考虑。企业更应思考的,是如何让每位员工创造更高的价值。

    CCS | Beyond Numbers

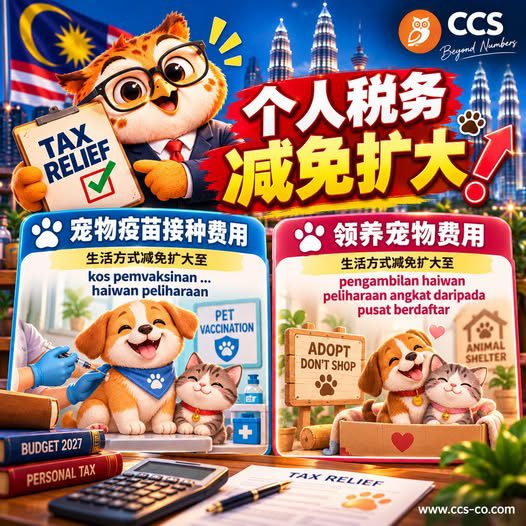
  • Budget 2027: Proposed Lifestyle Tax Relief for Pet Vaccinations and Adoptions

    Budget 2027: Proposed Lifestyle Tax Relief for Pet Vaccinations and Adoptions

    Budget 2027 proposes expanding Lifestyle Tax Relief to include two pet-related expenses:

    • Pet vaccination costs, subject to the final eligibility requirements; and

    • Fees for adopting a pet from a qualifying registered organisation.

    The proposal does not mean that all pet-related expenses, such as food, grooming, boarding or purchases from any pet shop, will qualify. The scope is limited to the specified relief items and will depend on the final rules.

    Tax relief is also not the same as a tax refund. Spending RM500 does not mean that LHDN will refund RM500. Eligible relief reduces chargeable income, while the actual tax saving depends on the individual’s applicable tax rate and the relief limit.

    Pet owners should check the effective Year of Assessment, qualifying expense conditions and receipt requirements once the final details are announced. Keep official receipts and any supporting documents.

    Pet vaccination protects an animal’s health, and adoption can give an animal in need a home. Any tax relief is an added benefit—not a reason on its own to take on the long-term responsibility of caring for a pet.

    CCS | Beyond Numbers

    Budget 2027:宠物疫苗与领养费用拟纳入生活方式税务减免

    《2027年财政预算案》提出扩大生活方式税务减免范围,拟纳入两类宠物相关费用:

    • 宠物疫苗接种费用,须符合最终公布的适用条件;以及

    • 向符合资格的注册机构领养宠物所支付的费用。

    这并不代表宠物食品、美容、寄宿,或向任何宠物店购买宠物的费用都符合减免条件。拟议范围仅限于指定项目,最终仍须以正式规定为准。

    税务减免也不等于退税。花费RM500,并不代表LHDN会退还RM500。符合条件的减免用于减少课税收入,实际节省的税款则取决于个人适用税率及减免上限。

    宠物主人应在正式细节公布后,确认适用课税年度、合资格费用条件及收据要求,并妥善保留正式收据和相关证明文件。

    为宠物接种疫苗,是为了保护它们的健康;领养则能为有需要的生命提供一个家。税务减免只是额外福利,不应成为承担长期宠物照护责任的唯一理由。

    CCS | Beyond Numbers

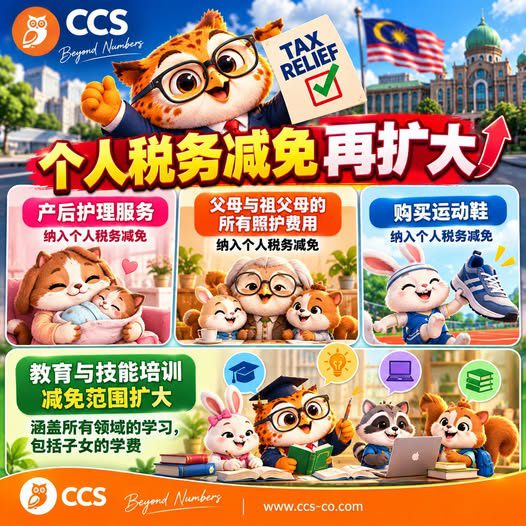
  • Budget 2027: Expanded Personal Tax Relief for Care, Sports Shoes and Education

    Budget 2027: Expanded Personal Tax Relief for Care, Sports Shoes and Education

    Budget 2027 proposes expanding personal tax relief to cover postnatal care services, all care expenses for parents and grandparents, and the purchase of sports shoes.

    Education and skills training tax relief is also set to cover all fields of study, including tuition fees for children.

    Budget 2027:个人税务减免范围拟扩大至护理、运动鞋及教育费用

    《2027年财政预算案》提出扩大个人税务减免范围,涵盖产后护理服务、父母及祖父母的各类照护费用,以及购买运动鞋的费用。

    教育与技能培训税务减免范围也将扩大至所有学科领域,包括子女的学费。

  • Budget 2027: Proposed 1-Percentage-Point Tax Rate Reduction for Eligible SMEs

    Budget 2027: Proposed 1-Percentage-Point Tax Rate Reduction for Eligible SMEs

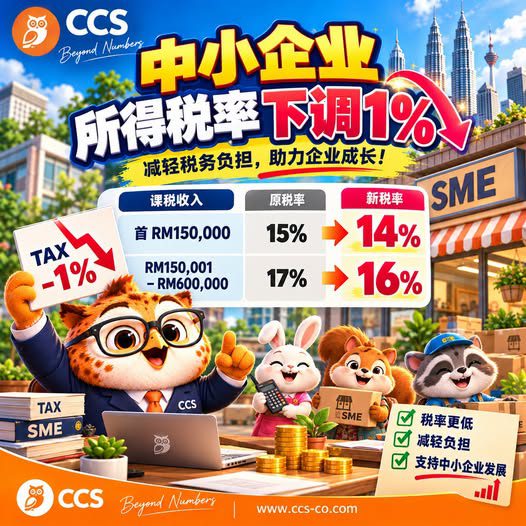
    Budget 2027 brings welcome news for eligible small and medium-sized enterprises (SMEs): the proposed income tax rates for the first two chargeable income bands would each be reduced by one percentage point.

    • First RM150,000 of chargeable income: from 15% to 14%

    • RM150,001 to RM600,000: from 17% to 16%

    The savings can add up. For a company with RM600,000 in chargeable income, the proposed reductions would result in:

    • RM1,500 saved on the first RM150,000; and

    • RM4,500 saved on the next RM450,000.

    That is a total of RM6,000 in tax savings for the year.

    The reduced rates will not automatically apply to every company; the business must meet the relevant SME tax eligibility requirements. Also, the RM600,000 figure refers to chargeable income, not revenue or the balance in the company’s bank account.

    A lower tax bill is certainly worth celebrating. The real opportunity, however, is to put the savings to work and grow the business further.

    Budget 2027:合资格中小企业税率拟下调1个百分点

    《2027年财政预算案》为符合资格的中小企业带来好消息:首两个课税收入区间的所得税率拟各下调1个百分点。

    • 首RM150,000课税收入:由15%下调至14%

    • RM150,001至RM600,000:由17%下调至16%

    税率下调带来的节省金额可能相当可观。假设一家公司的课税收入为RM600,000,按拟议税率计算:

    • 首RM150,000可节省 RM1,500;以及

    • 接下来的RM450,000可节省 RM4,500。

    全年合计可节省 RM6,000税款。

    不过,并非所有公司都会自动适用下调后的税率;企业仍须符合相关中小企业税务资格要求。此外,RM600,000指的是课税收入,不是营业额,也不是公司银行账户里的余额。

    税款减少当然值得开心,但更重要的是善用省下来的资金,进一步推动业务发展。

  • Budget 2027: Higher Capital Allowance Thresholds for Small-Value Assets

    Budget 2027: Higher Capital Allowance Thresholds for Small-Value Assets

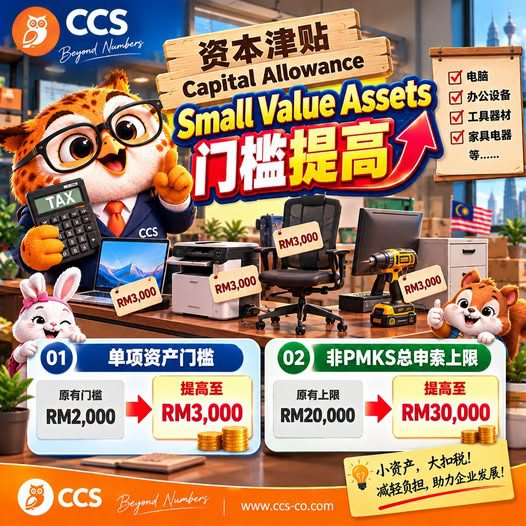
    Budget 2027 proposes increasing the capital allowance thresholds for small-value assets, which may make it easier for businesses to claim deductions for qualifying lower-cost assets.

    Higher Cost Limit Per Asset

    The cost limit for an individual small-value asset is proposed to increase from RM2,000 to RM3,000. Under the special capital allowance rules for small-value assets, qualifying assets costing no more than RM3,000 each may be eligible for a claim.

    Higher Aggregate Claim Limit for Non-PMKS Businesses

    For businesses that are not PMKS, the aggregate claim limit is proposed to increase from RM20,000 to RM30,000. This limit does not necessarily apply in the same way to every business.

    The increase may make it easier for businesses to claim capital allowances on qualifying items such as computers, printers, office chairs or coffee machines. However, an asset must meet the applicable tax requirements and be used for business purposes. Not every purchase will automatically qualify.

    Points to Keep in Mind

    • The RM3,000 threshold applies to the cost of each qualifying asset, not the total amount on an invoice.

    • The RM30,000 aggregate claim limit applies to non-PMKS businesses; other businesses may be subject to different rules.

    • A capital allowance is not a cash refund. A RM30,000 claim does not mean that LHDN will pay the business RM30,000.

    Before purchasing an asset, consider whether it is needed for the business, meets the tax requirements and is a worthwhile investment. Tax planning should support sound business decisions, not drive unnecessary spending.

    CCS | Beyond Numbers

    Budget 2027:拟提高小额资产资本津贴门槛

    《2027年财政预算案》提出提高小额资产的资本津贴门槛,让企业更容易就符合条件的低成本资产申报扣除。

    单项资产成本门槛提高

    单项小额资产的成本门槛拟从RM2,000提高至RM3,000。根据小额资产特别资本津贴规则,每项成本不超过RM3,000的合资格资产可能符合申索条件。

    非PMKS企业的总申索上限提高

    对于非PMKS企业,总申索上限拟从RM20,000提高至RM30,000。不同企业未必适用相同的总申索限制。

    这项调整可能让企业更容易就符合条件的电脑、打印机、办公椅或咖啡机等资产申报资本津贴。不过,资产仍须符合适用税务规定并用于业务,并非所有采购都能自动申报。

    请留意以下事项

    • RM3,000是每项合资格资产的成本门槛,并非每张发票的总额。

    • RM30,000总申索上限适用于非PMKS企业;其他企业可能适用不同规定。

    • 资本津贴不等于现金退款。申报RM30,000,并不代表LHDN会向企业支付RM30,000。

    购买资产前,应先考虑业务是否确实需要、资产是否符合税务条件,以及这项投资是否值得。税务规划应配合稳健的商业决策,而不是促使企业进行不必要的支出。

    CCS | Beyond Numbers

  • Budget 2027: Entertainment Duty Exemption for Eligible Local Films and Theatre Performances in Kuala Lumpur

    Budget 2027: Entertainment Duty Exemption for Eligible Local Films and Theatre Performances in Kuala Lumpur

    Budget 2027 announces a full exemption from Entertainment Duty for eligible local films and theatre performances in Kuala Lumpur. The measure could reduce the tax cost associated with qualifying events and encourage audiences to support Malaysia’s film and performing arts industries.

    The exemption may also benefit nearby businesses, such as restaurants and cafés, when audiences dine or meet before or after a show. Whether ticket prices will fall, however, will depend on how organisers set their prices.

    The exemption does not mean that all cinema tickets or performances are free of charge. Nor does it automatically apply to every concert, foreign film or entertainment event in Kuala Lumpur. The exact scope and eligibility conditions will depend on the formal rules.

    The policy is a welcome step in supporting local cultural activities—but an Entertainment Duty exemption should not be mistaken for a personal tax deduction or a waiver of other spending associated with a night out.

    CCS | Beyond Numbers

    Budget 2027:吉隆坡合资格本地电影及剧场演出豁免娱乐税

    《2027年财政预算案》宣布,吉隆坡符合条件的本地电影及剧场演出可获娱乐税全额豁免。这项措施有望减轻合资格演出的税务负担,并鼓励观众支持马来西亚电影及表演艺术。

    观众在观影或观赏演出前后,也可能带动附近餐厅、咖啡馆等商家的生意。不过,票价会否下调,仍取决于主办方的定价安排。

    娱乐税豁免不代表所有电影票或演出免费,也不代表吉隆坡所有演唱会、外国电影或娱乐活动都会自动获得豁免。具体适用范围及条件,仍须以正式规定为准。

    这项政策有助支持本地文化活动,值得肯定;但娱乐税豁免不应与个人税务扣除混为一谈,也不会免除外出娱乐可能产生的其他开销。

    CCS | Beyond Numbers

  • Budget 2027: Proposed Conditions for Tax Deduction of Salary Expenses

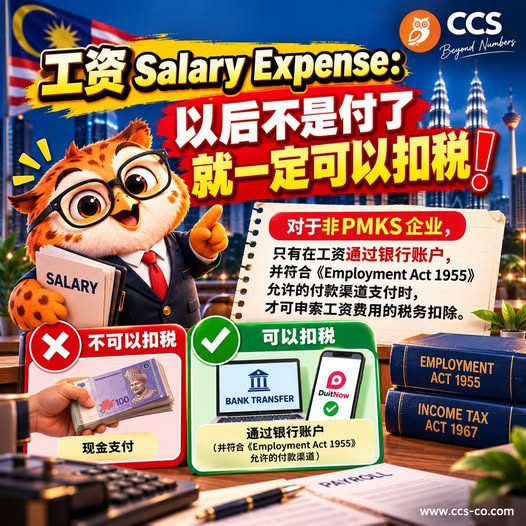
    Budget 2027: Proposed Conditions for Tax Deduction of Salary Expenses

    Under Budget 2027, non-PMKS businesses may claim a tax deduction for salary expenses only if wages are paid through a bank account and via a payment method permitted under the Employment Act 1955.

    The Budget speech also clarifies that this condition does not apply to tax deductions for other expenses. The proposed requirement is specifically directed at salary and wage expenditure.

    This raises an important corporate tax question: could wages that have genuinely been paid nevertheless be disallowed as a tax deduction if the payment method does not meet the prescribed requirements?

    The stated policy objective is to close opportunities for businesses to employ foreign workers without valid permits.

    However, the Budget speech does not provide further details on several important points:

    • whether the definition of PMKS will follow the existing tax definition;

    • whether the measure will apply from YA 2027;

    • whether cash salary payments will necessarily be fully disallowed;

    • whether directors’ remuneration will be covered;

    • whether commissions, allowances, overtime and bonuses will all be treated as “salary expenses”; and

    • whether the Income Tax Act 1967 will be amended, and, if so, which provision will be affected.

    These details will need to be confirmed through the Finance Bill, the Tax Measures Appendix or subsequent legislation.

    Budget 2027:工资支出并非支付后就一定可以扣税

    《2027年财政预算案》明确指出,对于非PMKS企业,只有在工资通过银行账户支付,并采用《1955年雇佣法令》(Employment Act 1955)允许的付款方式时,才可申报工资费用的税务扣除。

    财政预算案也特别说明,其他费用的税务扣除不受这项条件限制。拟议的新规定专门针对工资及薪金支出。

    这带出一个值得关注的企业所得税问题:即使工资确实已经支付,如果付款方式不符合规定,相关支出是否仍可能不获税务扣除?

    预算演词说明,这项政策旨在堵住企业聘用没有合法准证的外国劳工的空间。

    不过,预算演词尚未进一步说明以下事项:

    • PMKS的定义是否直接沿用现行税务定义;

    • 这项措施是否从YA 2027开始实施;

    • 现金支付工资是否必然完全不获扣除;

    • 董事酬金是否属于规定范围;

    • 佣金、津贴、加班费及花红是否都属于“工资支出”;以及

    • 《1967年所得税法令》是否会因此新增或修订条文,以及涉及哪一项规定。

    上述细节仍须等待《财政法案》(Finance Bill)、税务措施附录(Appendix Tax Measures)或后续立法文件进一步确认。

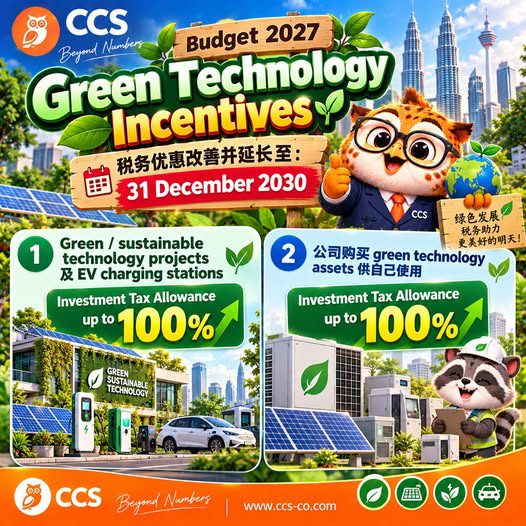
  • Budget 2027: Green Technology Tax Incentives Extended to 2030

    Budget 2027: Green Technology Tax Incentives Extended to 2030

    Budget 2027 announces improvements to green technology tax incentives and extends them until 31 December 2030. For qualifying investments, the Investment Tax Allowance (ITA) may be as high as 100%.

    The incentives cover two main areas:

    1. Green and Sustainable Technology Projects

    Eligible projects include qualifying green and sustainable technology projects, as well as electric vehicle (EV) charging stations. The ITA may be up to 100%, subject to the relevant requirements.

    2. Green Technology Assets for a Company’s Own Use

    Companies may also qualify when purchasing eligible green technology assets for use in their own businesses. The ITA may likewise be up to 100%.

    However, not every product labelled “green” automatically qualifies. Eligibility depends on the asset category, certification, application requirements and other applicable conditions.

    What Does a 100% ITA Mean?

    A 100% ITA is not a 100% cash refund. For example, if a company invests RM100,000 in qualifying green technology assets and is granted a 100% ITA, it may receive an allowance of RM100,000. This does not mean that LHDN will deposit RM100,000 into the company’s bank account.

    The amount that can be set off against statutory income depends on the applicable offset limits, conditions and rules.

    Before investing, businesses should consider whether the project can genuinely reduce energy use and operating costs, whether it meets the tax incentive requirements, and whether the expected return on investment and tax benefit justify the expenditure.

    Green technology should be considered a long-term investment, with tax incentives serving as an added benefit—not the sole reason to spend. The aim is to make investments that are commercially sound as well as more sustainable.

    CCS | Beyond Numbers

    Budget 2027:绿色科技税务优惠延长至2030年,投资税务津贴最高可达100%

    《2027年财政预算案》宣布改善绿色科技税务优惠,并将优惠期限延长至2030年12月31日。符合条件的投资,投资税务津贴(Investment Tax Allowance,ITA)最高可达100%。

    这项优惠主要涵盖两个领域:

    1. 绿色及可持续科技项目

    符合条件的绿色及可持续科技项目,以及电动车(EV)充电站,均可能适用相关优惠。投资税务津贴最高可达100%,具体须符合适用要求。

    2. 公司自用的绿色科技资产

    公司购买合资格绿色科技资产并用于自身业务,也可能符合相关优惠。投资税务津贴同样最高可达100%。

    不过,并非所有贴有“绿色”标签的产品都会自动符合资格。是否合格,取决于资产类别、认证、申请条件及其他适用规定。

    100% ITA代表什么?

    100%的投资税务津贴不等于100%现金退款。例如,公司投资RM100,000购买合资格的绿色科技资产,并获批100% ITA,代表可能获得RM100,000的投资税务津贴,并不表示LHDN会将RM100,000直接汇入公司的银行账户。

    实际可用于抵扣法定收入的金额,仍须视适用的抵扣比例、条件及相关规定而定。

    投资前,企业应考虑项目是否确实能够降低能源消耗与营运成本、是否符合税务优惠资格,以及预期投资回报与税务节省是否足以支持这项支出。

    绿色科技应被视为长期投资,税务优惠则是额外奖励,而不应成为投资的唯一理由。理想的投资既要具备商业效益,也应有助于企业走向更可持续的发展。

    CCS | Beyond Numbers