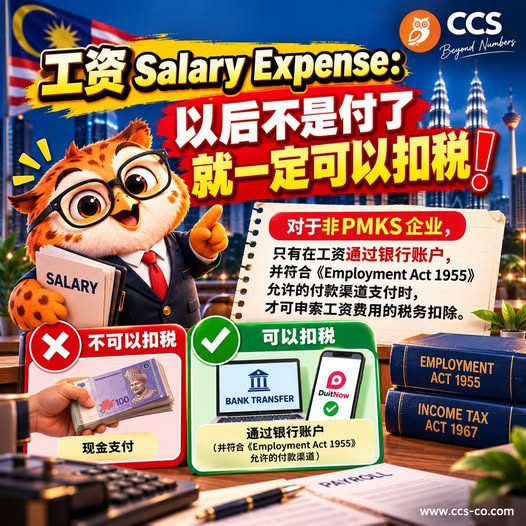
Under Budget 2027, non-PMKS businesses may claim a tax deduction for salary expenses only if wages are paid through a bank account and via a payment method permitted under the Employment Act 1955.
The Budget speech also clarifies that this condition does not apply to tax deductions for other expenses. The proposed requirement is specifically directed at salary and wage expenditure.
This raises an important corporate tax question: could wages that have genuinely been paid nevertheless be disallowed as a tax deduction if the payment method does not meet the prescribed requirements?
The stated policy objective is to close opportunities for businesses to employ foreign workers without valid permits.
However, the Budget speech does not provide further details on several important points:
- whether the definition of PMKS will follow the existing tax definition;
- whether the measure will apply from YA 2027;
- whether cash salary payments will necessarily be fully disallowed;
- whether directors’ remuneration will be covered;
- whether commissions, allowances, overtime and bonuses will all be treated as “salary expenses”; and
- whether the Income Tax Act 1967 will be amended, and, if so, which provision will be affected.
These details will need to be confirmed through the Finance Bill, the Tax Measures Appendix or subsequent legislation.
Budget 2027:工资支出并非支付后就一定可以扣税
《2027年财政预算案》明确指出,对于非PMKS企业,只有在工资通过银行账户支付,并采用《1955年雇佣法令》(Employment Act 1955)允许的付款方式时,才可申报工资费用的税务扣除。
财政预算案也特别说明,其他费用的税务扣除不受这项条件限制。拟议的新规定专门针对工资及薪金支出。
这带出一个值得关注的企业所得税问题:即使工资确实已经支付,如果付款方式不符合规定,相关支出是否仍可能不获税务扣除?
预算演词说明,这项政策旨在堵住企业聘用没有合法准证的外国劳工的空间。
不过,预算演词尚未进一步说明以下事项:
- PMKS的定义是否直接沿用现行税务定义;
- 这项措施是否从YA 2027开始实施;
- 现金支付工资是否必然完全不获扣除;
- 董事酬金是否属于规定范围;
- 佣金、津贴、加班费及花红是否都属于“工资支出”;以及
- 《1967年所得税法令》是否会因此新增或修订条文,以及涉及哪一项规定。
上述细节仍须等待《财政法案》(Finance Bill)、税务措施附录(Appendix Tax Measures)或后续立法文件进一步确认。