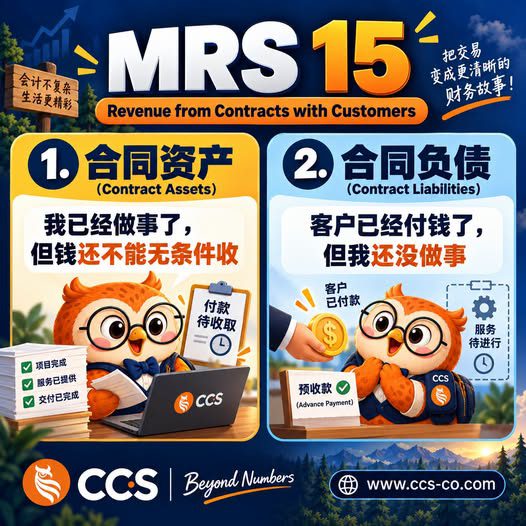
One of the most commonly misunderstood areas of MFRS 15 Revenue from Contracts with Customers is the distinction between contract assets, trade receivables and contract liabilities.
A Contract Asset Is Not the Same as a Trade Receivable
A trade receivable generally means that the business already has an unconditional right to receive payment. The business only needs to wait until the payment becomes due.
A contract asset, on the other hand, means that the business has already performed its obligations but must still satisfy a future condition before obtaining an unconditional right to receive payment.
This can be understood as follows:
- Trade receivable: The customer already owes me money; payment has simply not yet been made.
- Contract asset: The customer is likely to owe me money, but I must first obtain approval, achieve a milestone or satisfy another condition.
A Contract Liability Is Not “Money Earned”
Although the money has already been received and deposited into the bank, the business cannot immediately recognise the entire amount as revenue if it has not yet completed the corresponding service.
Consider a restaurant deposit as an example. The money has been received, but the meal has not yet been prepared. It would therefore be incorrect to say that the entire meal has already been sold.
A Simple Way to Remember the Key Questions
Has the business already performed its obligations?
- Performance completed but payment remains conditional → Contract asset
Has the business already received the customer’s payment?
- Payment received but performance has not yet been completed → Contract liability
Who owes whom?
- Contract asset: The customer may need to pay the business in the future.
- Contract liability: The business owes the customer goods or services in the future.
In one sentence:
A contract asset means “the work has been performed, but payment is still subject to a condition”; a contract liability means “payment has been received, but the work has not yet been completed.”
根据 MFRS 15 理解合同资产、应收账款与合同负债的关键区别
**MFRS 15《客户合同收入》**中最容易混淆的地方之一,就是合同资产、应收账款和合同负债之间的区别。
合同资产不是普通应收账款
**应收账款(Trade Receivable)**通常表示企业已经拥有无条件的收款权,只需要等待付款到期。
**合同资产(Contract Asset)**则表示企业虽然已经履约,但仍需满足某个未来条件,才能取得无条件的收款权。
可以这样理解:
- **应收账款:**客户已经欠我钱,只是还没有付款。
- **合同资产:**客户大概率会欠我钱,但我还需要先通过验收、达到里程碑或满足其他条件。
合同负债不是“赚到的钱”
虽然钱已经进入银行账户,但如果企业还没有完成相应的服务,就不能因为“收到钱”而马上将全部金额确认为收入。
可以把它想成餐厅收到的订金:钱已经收到了,但饭还没有煮好,因此不能说整桌菜已经全部卖出。
最终记忆法:先问三个关键问题
企业是否已经履约?
- 已经履约,但收款仍附带条件 → 合同资产
企业是否已经收到客户的钱?
- 已经收款,但尚未完成履约 → 合同负债
谁欠谁?
- **合同资产:**客户未来可能需要向企业付款。
- **合同负债:**企业未来欠客户商品或服务。
一句话总结:
Contract Asset 是“活做了,钱还要等条件”;Contract Liability 是“钱收了,活还没做完”。