Tag: Special Tax Deduction

  • Special Tax Deduction for Expenditure on Malaysian-Made Handicraft by Hotel Industry

    Special Tax Deduction for Expenditure on Malaysian-Made Handicraft by Hotel Industry

    Updated on 15 July 2023 - Dialogue between MOF,LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    The hotel industry has the opportunity to advertise itself as an enabler and assist in promoting the use of local handicraft products within the premises.

    Some examples of these products include songket decorations, ceramic, and wood-based products.

    Under normal circumstances, Capital Allowance is granted under Schedule 3 of the Income Tax Act 1967 when an eligible asset (if qualified as a “plant”) is purchased.

    Assets with a life span of less than two years are deductible on a replacement basis; subsequent purchases to replace an asset with a value of less than RM2,000 are eligible for a tax deduction under Section 33 of the Income Tax Act 1967.

    Proposal

    It is proposed that a special tax deduction be given for expenditures on qualified Malaysian-made handicrafts purchased from handicraft entrepreneurs certified by Perbadanan Kemajuan Kraftangan Malaysia incurred by hoteliers.

    The amount of this deduction would be capped at RM150,000.

    The purpose of this proposal is to support the recovery of Malaysian-made handicraft.

    Effective Date

    For eligible expenditure on handicraft products incurred from 1 January 2023 until 31 December 2025

    Dialogue between MOF, LHDNM and CTIM [21/6/2023]

    As mentioned under the current position, the purchase for replacement of assets with a value of less than RM2,000 qualifies for outright deduction under S.33 of the ITA 1967.

    CTIM was seeking confirmation on whether this is a concession given by the IRB and where it is legislated.

    LHDNM’s Feedback:

    • It is not a concession.
    • For asset categories valued at RM2,000 and below, claims can be made through:
      • Special allowance claims under paragraph 19A of Schedule 3 of the ITA 1967; or
      • Capital allowance claims under paragraphs 10 and 15 of Schedule 3 of the ITA 1967.
    • For assets with a useful life not exceeding two years, claims can be allowed on a replacement basis under Section 33 of the ITA 1967.

    Are taxpayers given an option whether to choose a special tax deduction claim on the items or to claim capital allowance / outright tax deduction under S33 if, let’s say, this item is potentially a long-lasting item that is capital in nature?

    LHDNM’s Feedback:

    Companies are allowed to choose to claim eligible capital expenditure as:

    • special tax deduction for Malaysian handicraft products; or
    • deduction under subsection 33(1) of the ITA 1967; or
    • capital allowance under Schedule 3 of the ITA 1967.

    The tax treatment option, once decided, is final and cannot be amended.

    CTIM sought clarification on what are the “ceramic and wood-based products in hotel premise” in the context illustrated.

    MOF’s Feedback: The product details will be discussed with the Malaysian Handicraft Development Corporation (PKKM) and will be informed accordingly through guidelines.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    21
  • Special Deduction for Reduction of Rental to a Small and Medium Enterprise

    Special Deduction for Reduction of Rental to a Small and Medium Enterprise

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) (Amendment) Rules 2021 [P.U. (A) 479].

    2. These Rules come into operation on 1 January 2022 to amend Rule 2 of The Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021 [P.U. (A) 353/2021].

    3. With this amendment, the “months eligible for the special deduction for rent” are from April 2020 to June 2022, whereas under P.U. (A) 353/2021, the “eligible months” are from April 2020 to December 2021 December 2020.

    4. As a result, the Government has extended the period by six months. 5. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使 1967年所得税法令 [法案53] 第154(1)(b) 段和第33(1)(d)段所赋予的权力,在宪报上颁布了 2021年所得税(中小型企业租金特别扣税)(修正案) 细则 [P.U. (A) 479]。

    2. 此细则从2022年1月1日起实施,主要是为了修订2021年所得税 (中小型企业租金特别扣税) 细则 [P.U. (A) 353/2021] 的第2条例。

    3. 在此修订后,”符合租金特别扣税条件的月份”是指从2020年4月至2022年6月,而在 P.U. (A) 353/2021 下,“符合条件的月份 ”是指2020年4月至2021年12月。

    4.因此,政府延长了6个月的期限。

    5. 加入我们的 Telegram: http://bit.ly/YourAuditor 🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    9
  • Income Tax (Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium

    Income Tax (Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium Enterprise) (Amendment) Rules 2021 [P.U. (A) 480].

    2. These Rules come into operation on 1 January 2022 to amend Rule 2 of The Income Tax (Special Deduction for Reduction of Rental to a Tenant other than a Small and Medium Enterprise) Rules 2021 [P.U. (A) 354/2021].

    3. With this amendment, the “months eligible for the special deduction for rent” are from January 2021 to June 2022, whereas under P.U. (A) 354/2021, the “eligible months” are from January 2021 to December 2021 December 2020.

    4. As a result, the Government has extended the period by six months.

    5. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使 1967年所得税法令 [法案53] 第154(1)(b) 段和第33(1)(d)段所赋予的权力,在宪报上颁布了 2021年所得税(非中小型企业租户租金特别扣税)(修正案) 细则 [P.U. (A) 480]。

    2. 此细则从2022年1月1日起实施,主要是为了修订2021年所得税 (非中小型企业租户租金特别扣税) 细则 [P.U. (A) 354/2021] 的第2条例。

    3. 在此修订后,“符合租金特别扣税条件的月份”是指从2021年1月至2022年6月,而在之前 P.U. (A) 354/2021 下,“符合条件的月份 ”是指2021年1月至2021年12月。

    4. 因此,政府延长了6个月的期限。

    5. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11
  • SME Status Certificate issued by SME Corp. Malaysia: Special Tax Deduction

    SME Status Certificate issued by SME Corp. Malaysia: Special Tax Deduction

    1. On September 8, 2021, the Malaysian government gazetted the following rules:

    👉 Income Tax (Special Deduction for Rental Reduction to a Small and Medium Enterprise) Rules 2021 [P.U.(A) 353/2021]; and

    👉 Income Tax (Special Deduction for Reduction of Rental to a Tenant Other Than a Small and Medium Enterprise) Rules 2021 [P.U.(A) 354/2021]

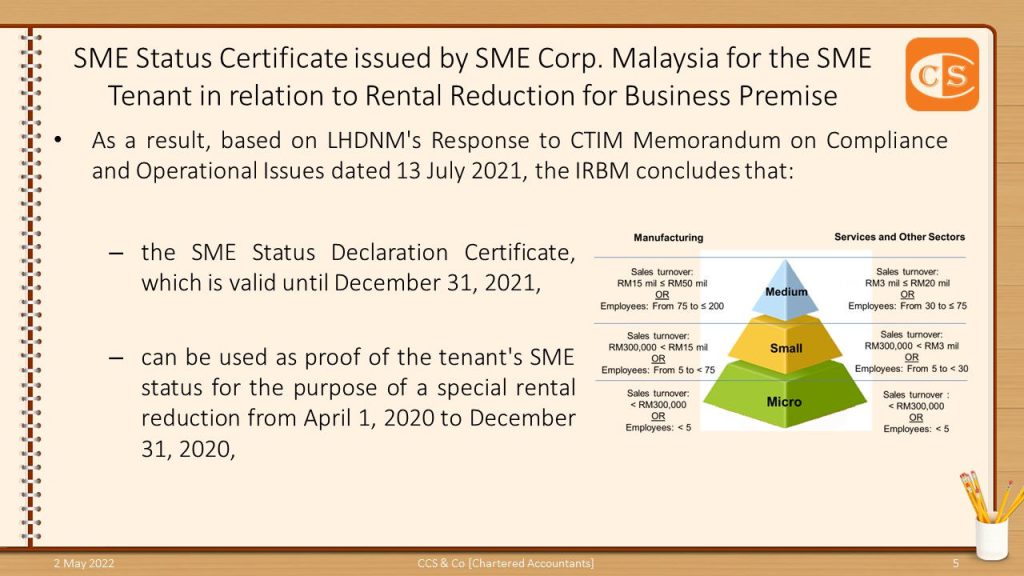
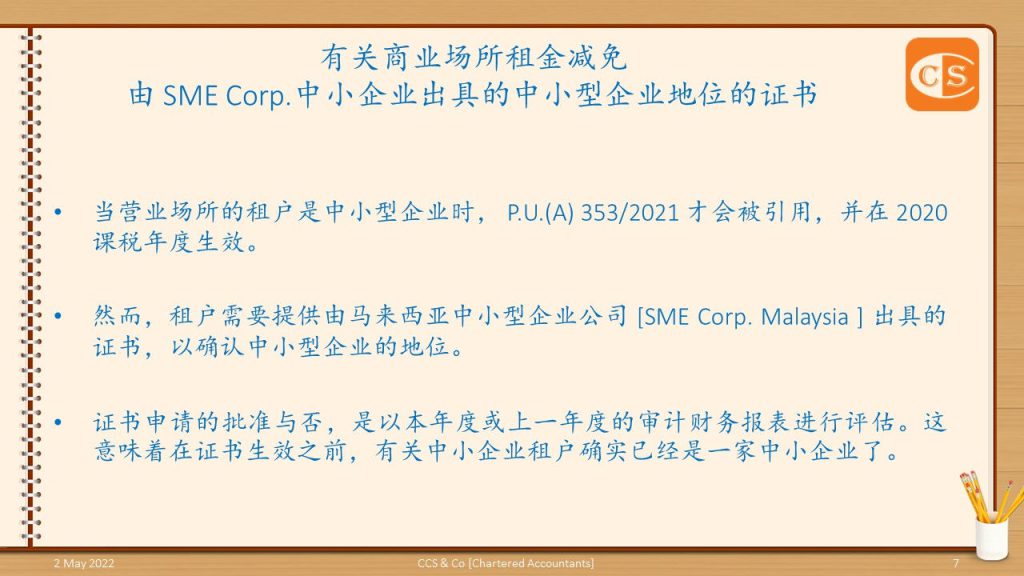
    2. P.U.(A) 353/2021 applies where a business premise’s tenant is a small and medium enterprise (“SME”) and is assumed to have taken effect in the assessment year 2020.

    3. However, a certificate by the SME Corp. Malaysia confirming the status of the small and medium enterprise as a supporting document is required.

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 2021年9月8日,马来西亚政府在宪报中颁布了以下两个细则 [Rules]:

    👉 2021年所得税 (中小型企业的租金减免特别扣除) 细则 [Income Tax (Special Deduction for Rental Reduction to a Small and Medium Enterprise) Rules 2021, P.U.(A) 353/2021];和

    👉 2021年所得税 (非中小型企业租户的租金减免特别扣除) 细则 [Income Tax (Special Deduction for Reduction of Rental to a Tenant Other Than a Small and Medium Enterprise) Rules 2021, P.U.(A) 354/2021]。

    2. P.U.(A) 353/2021 是在营业场所的租户是中小型企业的情况被引用,并在 2020课税年度生效。 3. 然而,租户需要提供由马来西亚中小型企业公司 [SME Corp. Malaysia ] 出具的证书,以确认中小型企业的地位。

    10
  • Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021

    Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021

    Special Deduction for Reduction of Rental to a Small and Medium Enterprise

    P.U. (A) 353 (2021)- Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021 – 8 September 2021

    1. 根据这项细则 [Income Tax (Special Deduction for Reduction of Rental to a Small and Medium Enterprise) Rules 2021]: 👉 2020年4月起至2021年12月这段期间;

    👉 产业业者根据现有租约 [Tenancy Agreement],提供不少于30%的租金回扣给中小企业,

    👉 将享有特别扣税 [Special Deduction] 2. 在根据该法第4(a)或(d)款确定房东在一个评估年度的基础期的租金收入调整后的收入时,应允许扣除相当于根据现有租赁协议减少的租金总额,即不低于月租金率的30%。 3. 产业业者 [Landlord] 需保留以下文件或资料: ✅ 一份根据1949年《印花税法令》盖章的租赁协议 [Tenancy Agreement];

    ✅ 针对符合资格的月份,另外一份单独的租金收入报表;

    ✅ 确认书 [confirmation letter]:

    🅰️ 产业业者 [Landlord] 出具的确认书,确认减免租金的数额;以及

    🅱️ 中小型企业出具的确认书,去确认收到租金减免;以及

    ✅ 中小企业公司的资格证明 – 由马来西亚中小型企业公司 [SME Corp. Malaysia ] 所发出的中小型企业地位的确认证件。

    7