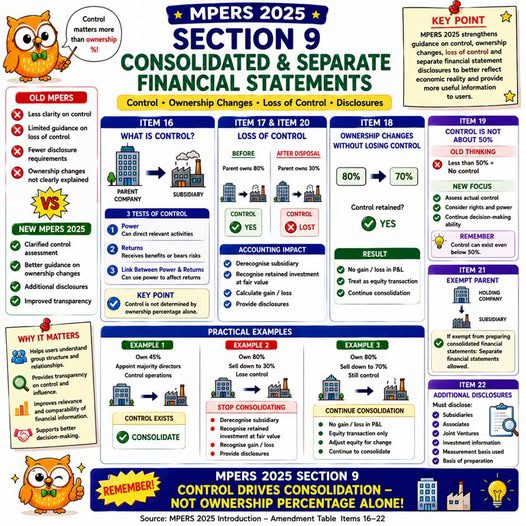
Many people assume that control exists only when an investor owns more than 50% of an entity’s shares.
However, under MPERS 2025 Section 9, control is determined by more than shareholding percentage alone.
An entity must assess whether it has:
- Power over the investee;
- Exposure to variable returns from its involvement with the investee; and
- The ability to use its power to influence those returns.
Shareholding may be an important indicator, but it is not the only factor. The assessment should focus on the underlying economic substance of the relationship.
When a parent loses control of a subsidiary, significant accounting consequences arise. These may include:
- Derecognition of the subsidiary’s assets and liabilities from the consolidated financial statements;
- Fair value measurement of any retained interest; and
- Additional disclosure requirements.
Understanding the concept of control helps users see the economic substance behind group structures and consolidated financial statements.
Control is not determined by ownership percentage alone. It is determined by who has the power and ability to influence the returns.
CCS | Beyond Numbers
MPERS 2025 第 9 节:控制权不只是超过 50% 的持股
很多人以为,只有当投资者拥有超过 50% 的股权时,才算拥有控制权。
然而,根据 MPERS 2025 第 9 节,控制权的判断远不止于持股比例。
企业必须评估是否具备以下条件:
- 对被投资方拥有权力(Power);
- 因参与被投资方而享有或承担可变回报(Variable Returns);以及
- 有能力运用该权力影响这些回报。
持股比例可能是重要的判断因素,但并不是唯一依据。企业应当关注双方关系背后的经济实质。
当母公司失去对子公司的控制权时,会产生重大的会计影响,包括:
- 在合并财务报表中终止确认该子公司的资产和负债;
- 按公允价值计量保留的投资权益;以及
- 履行额外的披露要求。
理解控制权的概念,有助于使用者看清集团架构及合并财务报表背后的经济实质。
控制权并不只是看持有多少股权,而是看谁拥有权力,以及谁能够运用该权力影响所获得的回报。
CCS | Beyond Numbers