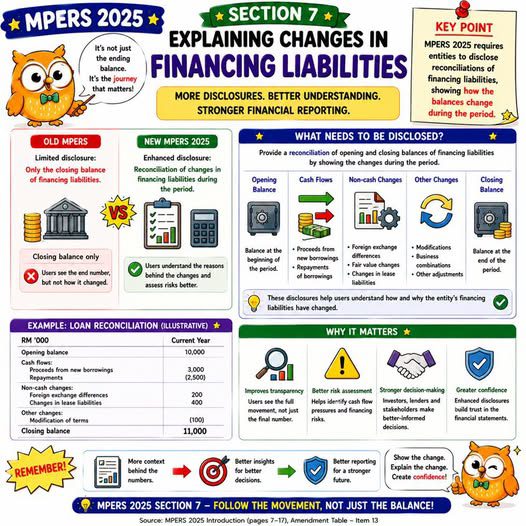
A loan balance at year end shows where the company ended, but it does not explain how the company arrived there.
MPERS 2025 Section 7 requires better disclosure of changes in financing liabilities. Entities should reconcile:
- Opening balances;
- Cash-flow movements;
- Non-cash changes; and
- Closing balances.
This helps users understand the effects of:
- New borrowings;
- Repayments;
- Foreign exchange movements;
- Changes in lease liabilities; and
- Other financing activities.
Clear movement analysis provides more than a year-end balance. It helps users assess how the company’s financing position has changed, improves transparency and supports more informed risk assessment.
A closing balance shows the destination. Movement analysis explains the journey.
CCS | Beyond Numbers
MPERS 2025 第 7 节:了解融资负债的变动过程
年末贷款余额,只告诉我们公司最后停在哪里,却未必说明公司是如何走到这个余额的。
MPERS 2025 第 7 节要求企业加强融资负债变动的披露,并通过调节表说明:
- 期初余额;
- 现金流变动;
- 非现金变动;以及
- 期末余额。
这有助于财务报表使用者了解以下因素所带来的影响:
- 新增借款;
- 偿还贷款;
- 外汇变动;
- 租赁负债变动;以及
- 其他融资活动。
清楚披露融资负债的变化过程,不只是呈现一个年末余额,也能帮助使用者评估企业融资状况的变化,提升透明度,并作出更有依据的风险评估。
期末余额显示的是终点,变动分析解释的则是整个过程。
CCS | Beyond Numbers