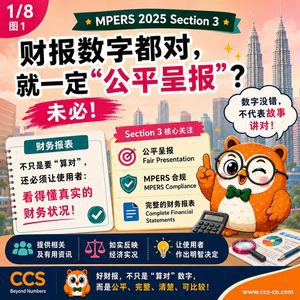
Does getting every figure right mean that the financial statements have been prepared correctly?
Not necessarily.
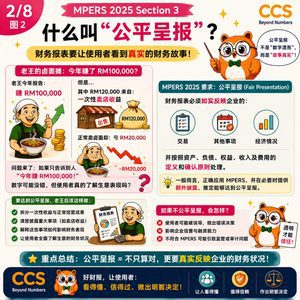
Under MPERS 2025 Section 3, financial statements are not merely about inserting accurate figures into the accounts. They must also provide a fair presentation of the entity’s financial position, financial performance and cash flows.
More Than Accurate Calculations
A proper set of financial statements should be:
- Fairly presented;
- Complete;
- Clear; and
- Comparable.
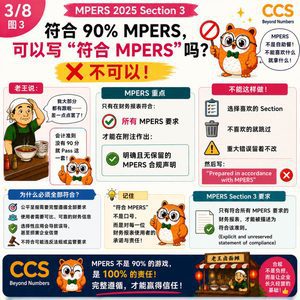
An entity must apply MPERS in its entirety. It cannot select only the Sections it prefers and ignore the rest.
MPERS is not a buffet where an entity can choose only the accounting requirements it likes.
Assessing Going Concern
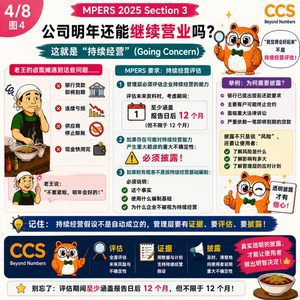
Management must also carefully assess whether the entity can continue as a going concern.
If there are material uncertainties that may cast significant doubt on the entity’s ability to continue operating, those uncertainties should be appropriately disclosed in the financial statements.
Consistent Presentation and Comparative Information
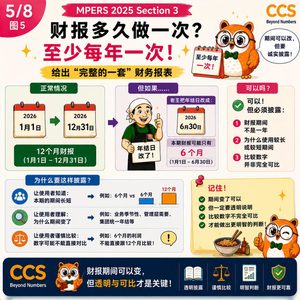
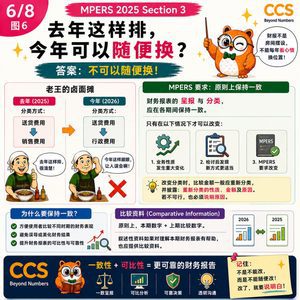
The presentation and classification of items in the financial statements should generally remain consistent from one period to the next, unless a change is justified by the applicable requirements or results in more relevant and reliable information.
Financial statements should also include comparative information so that users can assess changes in the entity’s financial position and performance over time.
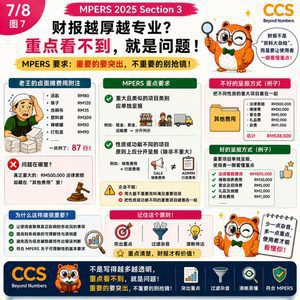
Material items should be presented clearly and given appropriate prominence. Important information should not be buried under a large volume of irrelevant or insignificant details.
A Complete Set of Financial Statements
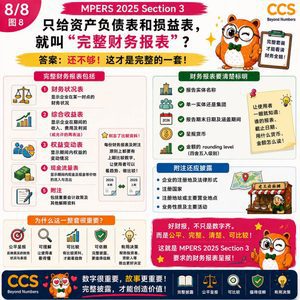
A balance sheet and an income statement alone do not constitute a complete set of financial statements.
A complete set should include all statements and notes required by the applicable financial reporting framework.
In simple terms:
Good financial statements are not merely complete in numbers. They should also be understandable, trustworthy and useful for making informed decisions.
CCS | Beyond Numbers
MPERS 2025 第 3 节:数字全部正确,不代表财报就做对了
财务报表里的数字全部算对,就代表财报一定做对了吗?
不一定。
根据 MPERS 2025 Section 3,财务报表不只是把准确的数字放进账簿,更重要的是要对企业的财务状况、财务表现及现金流量作出公允呈报(Fair Presentation)。
不只是数字正确
一套合格的财务报表应当做到:
- 公允呈报;
- 内容完整;
- 表达清楚;以及
- 具有可比性。
企业必须完整遵循 MPERS,不能只选择自己喜欢的 Section 来采用,而忽略其他适用要求。
MPERS 不是自助餐,不能只挑自己喜欢的会计要求来执行。
持续经营能力的评估
管理层也必须认真评估企业是否有能力继续经营。
如果存在可能对企业持续经营能力产生重大疑虑的重大不确定性,就应当在财务报表中作出适当披露。
一致的呈报方式与比较资料
财务报表中项目的呈报及分类,一般应在不同期间保持一致,除非相关改变是适用要求所规定,或能够提供更相关及可靠的信息。
财务报表也应提供比较资料,让使用者能够了解企业财务状况及财务表现随时间的变化。
重大项目应当清楚呈现并获得适当突出,不能让大量不重要或无关紧要的资料淹没重点。
完整的一套财务报表
只有资产负债表和损益表,并不构成完整的一套财务报表。
完整的财务报表应包括适用财务报告框架所要求的全部报表及附注。
简单来说:
一份好的财务报表,不只是数字齐全,也要让使用者看得懂、信得过,并能够作出明智的决定。
CCS | Beyond Numbers