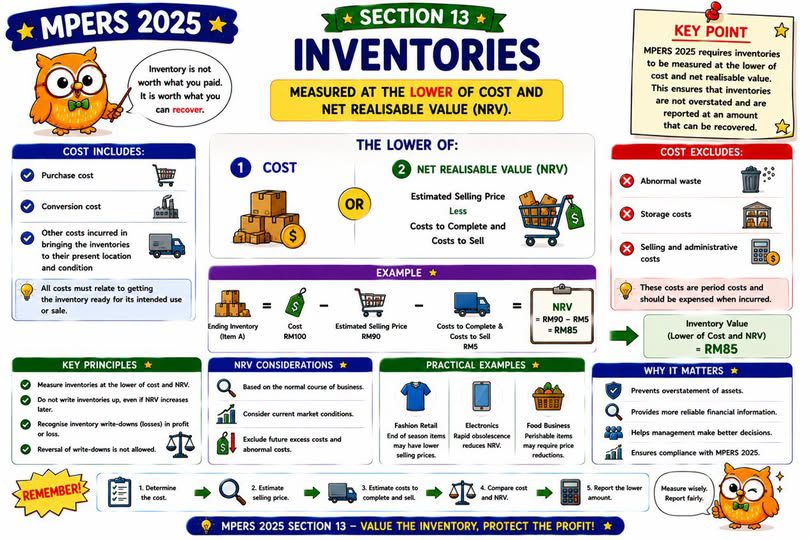
Many business owners believe that inventory should always be carried at its purchase cost.
However, MPERS 2025 Section 13 requires inventories to be measured at the lower of cost and net realisable value (NRV).
When products become obsolete, damaged or slow-moving, or when market selling prices decline, the carrying amount of the inventory may need to be reduced.
This prevents assets and profits from being overstated.
Proper inventory valuation provides a more realistic view of a company’s financial position and helps management make better business decisions.
Ultimately, the value of inventory is not determined only by how much it originally cost. It also depends on how much the business can realistically recover from selling it today.
CCS | Beyond Numbers
MPERS 2025 第 13 节:存货按成本与可变现净值孰低计量
许多企业主认为,存货应该一直按照购买成本入账。
然而,MPERS 2025 第 13 节规定,存货必须按照成本与可变现净值(Net Realisable Value,NRV)两者中的较低者计量。
当产品出现过时、损坏、滞销,或市场售价下降时,企业可能需要调低存货的账面金额。
这样可以避免资产及利润被高估。
正确的存货估值,能够更真实地反映企业的财务状况,并协助管理层作出更准确的经营决策。
归根结底,存货的价值不只是当初购买时花了多少钱,也取决于企业今天实际能够通过出售存货收回多少钱。
CCS | Beyond Numbers