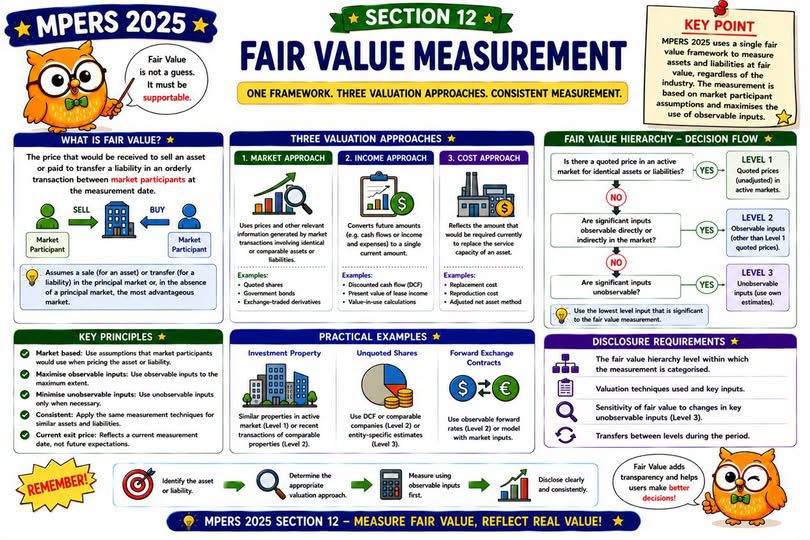
Fair value measurement aims to reflect the price that would be received to sell an asset or paid to transfer a liability in an orderly market transaction.
MPERS 2025 Section 12 provides a consistent framework for measuring fair value using three principal valuation approaches:
- Market approach;
- Income approach; and
- Cost approach.
The standard also emphasises maximising the use of observable inputs and minimising reliance on unobservable assumptions.
Whether the item being valued is an investment property, unquoted shares or a foreign exchange contract, fair value should be based on available evidence rather than unsupported estimates.
Reliable valuation contributes to more transparent, comparable and meaningful financial reporting.
CCS | Beyond Numbers
MPERS 2025 第 12 节:公允价值不只是一个数字
公允价值计量的目标,是反映在有序市场交易中出售一项资产所能取得的价格,或转移一项负债所需支付的价格。
MPERS 2025 第 12 节建立了一套一致的公允价值计量框架,主要涵盖三种估值方法:
- 市场法;
- 收益法;以及
- 成本法。
准则也强调,企业应尽可能使用可观察的市场数据,并尽量减少对不可观察假设的依赖。
无论估值对象是投资性房地产、非上市公司股份,还是外汇合约,公允价值都应建立在可取得的客观证据之上,而不是没有依据的主观估计。
可靠的估值,有助于提升财务报告的透明度、可比性及决策有用性。
CCS | Beyond Numbers