Accounting standard updates involve more than changes in wording. They may affect how businesses apply accounting requirements and present financial information.
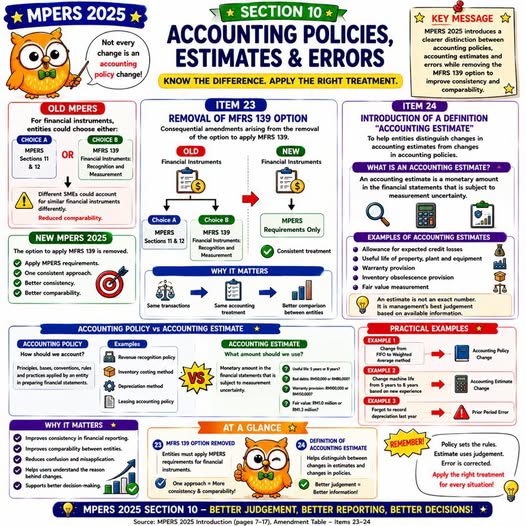
One important change in MPERS 2025 Section 10 is the removal of the option to apply MFRS 139. This promotes a more consistent approach to accounting for financial instruments across eligible entities.
The revised standard also introduces a formal definition of Accounting Estimate. This helps businesses distinguish between:
- Changes in accounting policies;
- Changes in accounting estimates; and
- Corrections of prior period errors.
Understanding the differences between these three categories helps reduce the risk of misstatement and supports more consistent accounting treatment.
It also improves the transparency and comparability of financial statements, helping users make better-informed decisions.
CCS | Beyond Numbers
MPERS 2025 第 10 节:了解会计政策、会计估计与前期错误的变更
会计准则的更新,并不只是文字上的修改,也可能影响企业应用会计要求及呈报财务资料的方式。
MPERS 2025 第 10 节其中一项重要变化,是取消采用 MFRS 139 的选择权,让符合资格的企业采用更一致的金融工具会计处理方式。
修订后的准则也正式引入了**会计估计(Accounting Estimate)**的定义,帮助企业区分:
- 会计政策变更;
- 会计估计变更;以及
- 前期错误更正。
理解这三者之间的差异,有助于减少错报风险,并确保企业采用更一致的会计处理方式。
这也能够提升财务报表的透明度及可比性,帮助使用者作出更有依据的决策。
CCS | Beyond Numbers