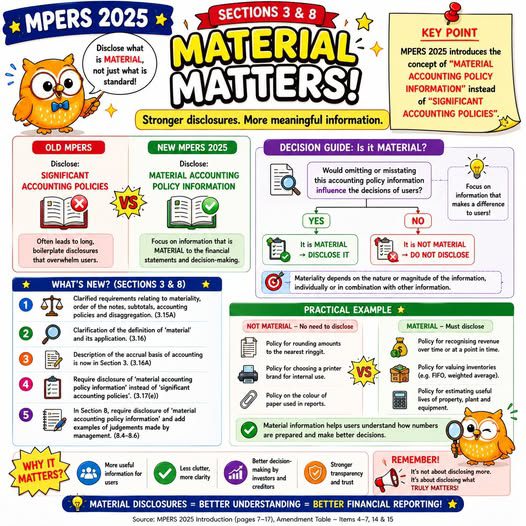
MPERS 2025 shifts the focus from disclosing “significant accounting policies” to disclosing material accounting policy information.
The objective is not to provide more disclosures, but to provide disclosures that are more relevant and useful.
Information is material if its omission, misstatement or obscurity could influence the decisions of users of the financial statements.
This change encourages:
- Clearer and more entity-specific reporting;
- Fewer unnecessary boilerplate disclosures; and
- Greater focus on the accounting information that truly matters.
Investors, creditors and other stakeholders should be able to understand the accounting policies that have a meaningful impact on a company’s financial position and performance.
Effective disclosure is not about saying more. It is about making important information clear.
CCS | Beyond Numbers
MPERS 2025:重要的不只是披露,而是披露真正重要的事项
MPERS 2025 将披露重点从“重大会计政策(Significant Accounting Policies)”,转向披露重要会计政策信息(Material Accounting Policy Information)。
这项修订的目的,并不是增加披露内容,而是提高披露内容的相关性与实用价值。
如果某项信息的遗漏、错误陈述或模糊表达,可能影响财务报表使用者的决策,该信息便属于重要信息(Material Information)。
这项改变有助于:
- 提升财务报告的清晰度;
- 减少不必要的模板式披露;以及
- 让投资者、债权人及其他利益相关者,更容易掌握真正重要的财务信息。
使用者应能够了解那些对企业财务状况及经营表现产生实质影响的会计政策。
有效的披露,不是说得更多,而是让重要信息变得清楚。
CCS | Beyond Numbers