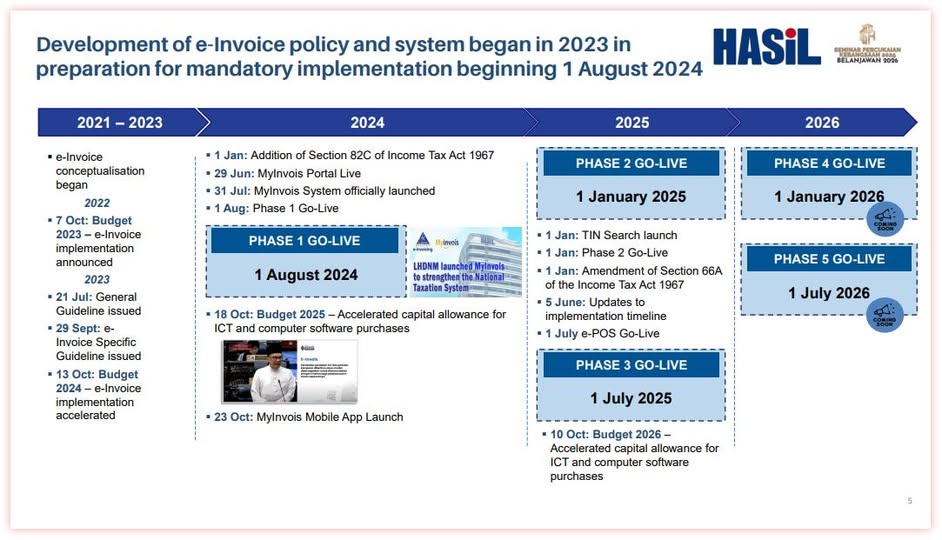
Malaysia’s e-Invoice system was introduced in stages, giving businesses time to prepare for changes to the way transactions are recorded and reported. Since the initial announcements, the implementation schedule and exemption threshold have been revised.
From announcement to implementation
The Government announced the e-Invoice initiative in Budget 2023, presented in October 2022, with implementation planned in stages. The following year, Budget 2024 brought forward the rollout, setting 1 August 2024 as the start date for taxpayers with annual turnover or revenue exceeding RM100 million.
Section 82C of the Income Tax Act 1967 provides the statutory framework for e-Invoice requirements. HASiL’s guidelines and FAQs set out how the requirements apply to different taxpayers and transaction types.
Implementation dates
HASiL’s current timeline sets out four implementation dates, based on annual turnover or revenue:
- More than RM100 million: 1 August 2024.
- More than RM25 million and up to RM100 million: 1 January 2025.
- More than RM5 million and up to RM25 million: 1 July 2025.
- Up to RM5 million: 1 January 2026, subject to the applicable exemption.
The schedule was designed to extend e-Invoice implementation to more taxpayers over time. However, the final date does not mean that every business with annual turnover or revenue of up to RM5 million must implement e-Invoice.
The RM3 million exemption
Effective 1 September 2026, the Government raised the exemption threshold from RM1 million to RM3 million. Taxpayers with annual turnover or revenue below RM3 million are exempt from implementation if they meet the applicable exemption criteria.
HASiL’s updated FAQs also clarify that eligible taxpayers who had begun issuing e-Invoices may discontinue doing so without a separate application or prior approval. Businesses should check the criteria in the guidelines, including the rules concerning related companies, before relying on the exemption.
What businesses should consider
For businesses required to implement e-Invoice, preparation involves more than selecting a software system. They should review how sales, purchases, employee claims and other transactions are documented, and determine how the requirements fit into their existing processes.
Where buyers do not request individual e-Invoices, suppliers may generally issue consolidated e-Invoices for eligible transactions. These must be submitted within seven calendar days after the end of the month, subject to the applicable exclusions.
The implementation journey has moved from an initial policy announcement to a phased rollout, followed by a revised exemption threshold. Businesses should refer to HASiL’s current implementation timeline and latest guidance when assessing their obligations.
马来西亚电子发票推行历程:重要里程碑与现行要求
马来西亚电子发票采取分阶段推行,让企业有时间为交易记录与申报方式的变化做好准备。自最初公布以来,实施时间表与豁免门槛均经过调整。
从政策公布到正式实施
政府在2022年10月提呈的2023年财政预算案中宣布推行电子发票,并计划分阶段实施。翌年,2024年财政预算案提前了推行时间,并规定年营业额或收入超过 RM100 million 的纳税人须自2024年8月1日起实施。
《1967年所得税法令》第82C条构成电子发票要求的法定框架。HASiL 发布的指南与常见问题则说明这些要求如何适用于不同纳税人及交易类型。
实施日期
HASiL 现行时间表根据年营业额或收入列出四个实施日期:
- 超过 RM100 million:2024年8月1日。
- 超过 RM25 million 且不超过 RM100 million:2025年1月1日。
- 超过 RM5 million 且不超过 RM25 million:2025年7月1日。
- 不超过 RM5 million:2026年1月1日,但须考虑适用的豁免规定。
该时间表旨在逐步扩大电子发票的实施范围。不过,最后一个实施日期并不代表年营业额或收入不超过 RM5 million 的所有企业都必须实施电子发票。
RM3 million 豁免门槛
自2026年9月1日起,政府将豁免门槛从 RM1 million 提高至 RM3 million。年营业额或收入低于 RM3 million 的纳税人,如符合适用的豁免条件,可获豁免实施电子发票。
HASiL 更新后的常见问题也说明,符合资格且已经开始开具电子发票的纳税人,无须另行申请或事先取得批准,即可停止开具。企业在依据豁免安排前,应先核对指南所列条件,包括有关关联公司的规定。
企业应留意的事项
对于须实施电子发票的企业,准备工作不只是选择软件系统。企业还应检视销售、采购、员工报销及其他交易的记录方式,并确认相关要求如何融入现有流程。
若买方没有要求开具个别电子发票,供应商一般可为符合条件的交易开具合并电子发票。这类电子发票须在月末后的七个日历日内提交,并须遵守适用的例外规定。
电子发票从最初的政策公告发展至分阶段推行,之后豁免门槛也有所调整。企业评估自身义务时,应参阅 HASiL 的现行实施时间表及最新指南。