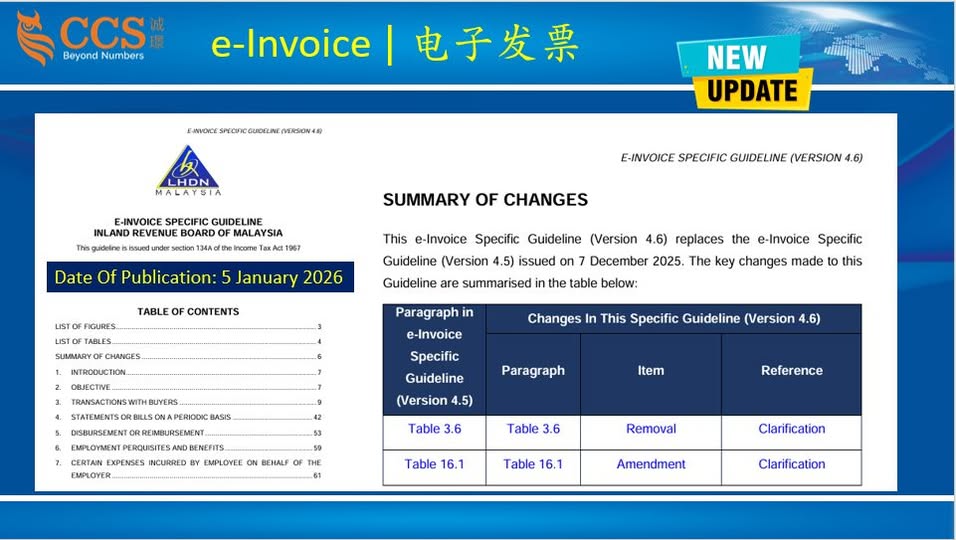
Version 4.6 of the e-Invoice Specific Guideline differs from Version 4.5 in two areas:
- Table 3.6 has been removed.
- Table 16.1 has been amended.
Businesses should review the revised guideline and compare the relevant sections with the previous version to understand any implications for their transactions and compliance processes, particularly in relation to consolidated e-Invoices and the interim relaxation period. The effect of each change should be assessed against the wording of the guideline rather than assumed from the table changes alone.
e-Invoice 专项指南的主要变更:版本4.5与版本4.6对比
《e-Invoice Specific Guideline》版本4.6相较于版本4.5,有两项主要变更:
- 表3.6已删除。
- 表16.1已修订。
企业应仔细阅读修订后的指南,并将相关内容与前一版本进行对比,以了解这些变更对交易处理及合规流程可能产生的影响,尤其是合并电子发票和临时宽限期的相关安排。企业应依据指南的实际条文评估各项变更,不应仅凭表格的删除或修订推断其具体影响。