Gifted by Father, Sold by Uncle: How Is RPGT Calculated When A Eventually Sells the Entire Property?
When a property is jointly held by family members, the Real Property Gains Tax (RPGT) should not be allocated based simply on family relationships or ownership proportions.
There are three key points in this case:
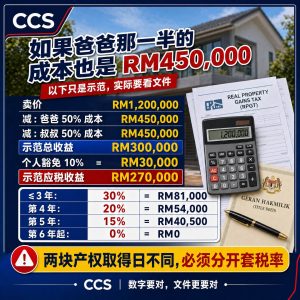
- First, the 50% interest gifted by the father and the 50% interest sold by the uncle must be calculated separately.
- Second, the acquisition dates of the two interests are different. As a result, the holding period for each interest may also be different.
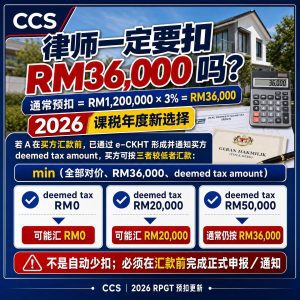
- Third, the final RPGT payable is not the same as the amount withheld by the lawyer during the transaction.
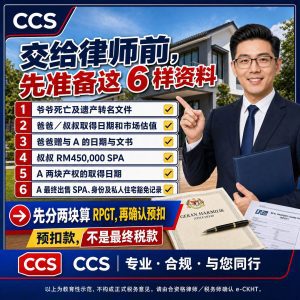
Therefore, although a property may be divided or jointly held among family members, the RPGT calculation must still be carried out separately for each interest based on its method of acquisition, acquisition date, disposal details and relevant documents.
The above is provided for educational purposes only. The actual amount payable and the relevant filing requirements should be confirmed by a qualified lawyer or tax adviser based on the actual documents and e-CKHT.
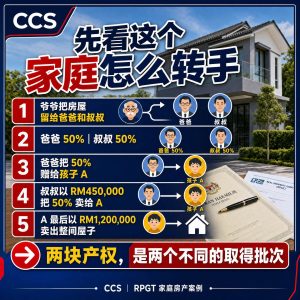
爸爸赠与、叔叔出售:A 最终出售整间房屋时,RPGT 如何计算?
在家庭成员共同持有房屋的情况下,房产交易涉及的 RPGT(房地产盈利税)计算不能简单地按家庭关系或产权比例凭感觉划分。
本案例的重点有三个:
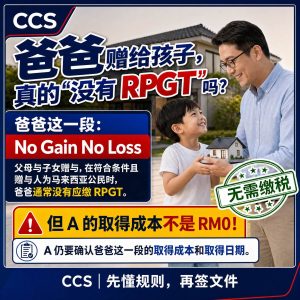
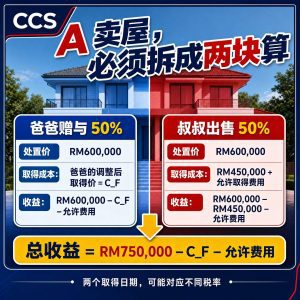
- 第一,爸爸赠与的 50% 产权与叔叔出售的 50% 产权,必须分开计算。
- 第二,两部分产权的取得日期不同,因此各自的持有年数也可能不同。
- 第三,最终应缴付的 RPGT,与律师在交易过程中预扣的款项,并不是同一回事。
因此,虽然房屋可以由一家人共同分配或持有,但 RPGT 的计算仍须根据每一部分产权的取得方式、取得日期、出售资料及相关文件分别处理。
以上内容仅作为教育性示范。正式应缴金额及相关申报事项,须由合资格律师或税务师根据实际文件及 e-CKHT 确认。