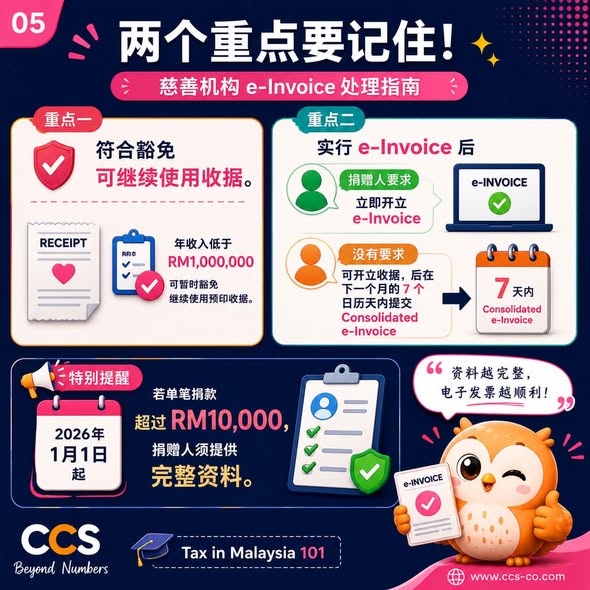
Charitable institutions approved under Section 44(6) of the Income Tax Act 1967 may follow different e-Invoice procedures depending on whether they are exempt and whether a donor requests an e-Invoice.
Institutions with Annual Income Below RM1 Million
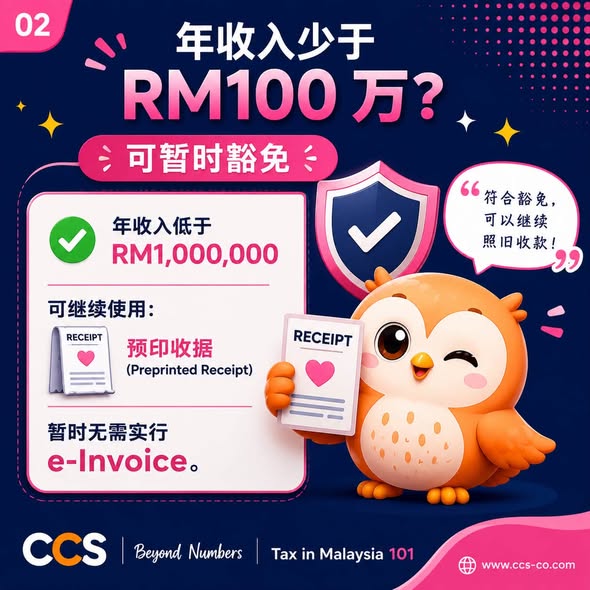
Institutions with annual income below RM1 million may be temporarily exempt from implementing e-Invoice. During the exemption period, they may continue issuing pre-printed receipts and are not required to implement e-Invoice.
Institutions That Have Implemented e-Invoice
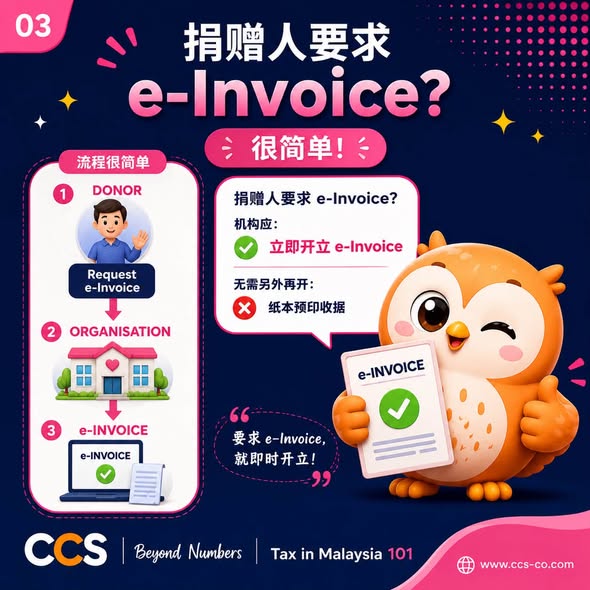
If a donor requests an e-Invoice, the institution should issue one immediately. A separate pre-printed paper receipt is not required.
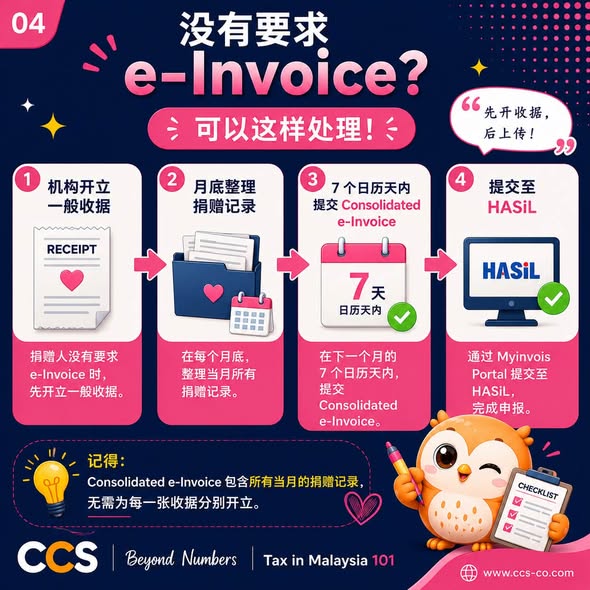
If the donor does not request an e-Invoice, the institution may issue a normal receipt and submit a Consolidated e-Invoice within seven calendar days of the following month.
Important Reminder
From 1 January 2026, after the Relaxation Period has ended, if a single donation exceeds RM10,000, the donor must provide complete information.
In summary: An institution that qualifies for the exemption may continue using receipts. Once it implements e-Invoice, it should issue an individual e-Invoice when requested by the donor and consolidate transactions when no e-Invoice is requested.
《1967年所得税法令》第44(6)条下获批准的慈善机构:e-Invoice处理方式
根据《1967年所得税法令》第44(6)条获批准的慈善机构,须根据自身是否符合豁免条件,以及捐赠人是否要求开具 e-Invoice,采用相应的处理方式。
年收入低于RM100万的机构
年收入低于RM100万的机构可暂时豁免实施 e-Invoice。在豁免期间,机构可继续使用预印收据,无需实施 e-Invoice。
已实施 e-Invoice 的机构
如果捐赠人要求开具 e-Invoice,机构应立即开具,无需另外开具纸本预印收据。
如果捐赠人没有要求 e-Invoice,机构仍可开具一般收据,并于次月七个日历日内提交合并电子发票(Consolidated e-Invoice)。
重要提醒
自2026年1月1日起,宽限期(Relaxation Period)结束后,如果单笔捐款超过RM10,000,捐赠人须提供完整资料。
简单来说:符合豁免条件的机构可继续使用收据。机构实施 e-Invoice 后,捐赠人提出要求时应开具个别电子发票;未提出要求时,则可汇总交易后提交合并电子发票。