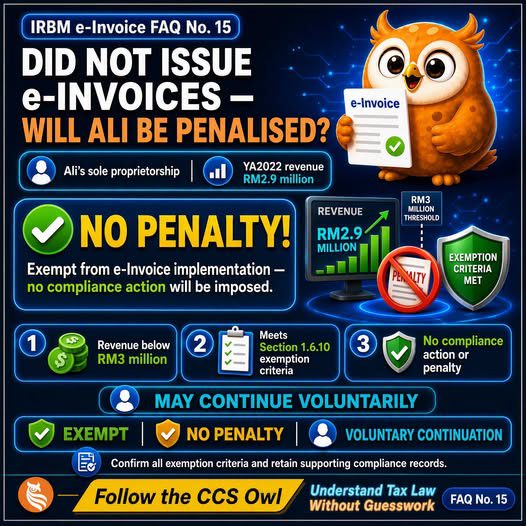
FAQ No. 15 considers Ali, who operates a sole proprietorship. His turnover was RM2.9 million in YA 2022 and did not exceed RM3 million in subsequent Years of Assessment.
If Ali’s turnover remains below RM3 million and he meets the e-Invoice exemption criteria in Section 1.6.10, he is exempt from implementing e-Invoice.
Accordingly, even if Ali does not issue e-Invoices from 1 January 2026, he will not face e-Invoice compliance action or penalties, provided he qualifies for the exemption.
An exempt business may still choose to issue e-Invoices voluntarily in support of the Government’s digitalisation initiative.
e-Invoice常见问题第15条:营业额低于RM300万的独资企业豁免
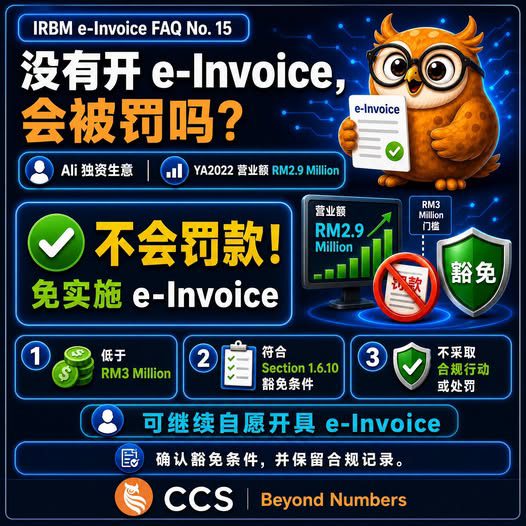
常见问题第15条以Ali为例。Ali经营独资生意,YA 2022的营业额为RM290万,之后各课税年度的营业额均未超过RM300万。
只要Ali的营业额低于RM300万,并符合第1.6.10节所列的 e-Invoice 豁免条件,即可豁免实施 e-Invoice。
因此,只要符合豁免资格,即使Ali从2026年1月1日起没有开具 e-Invoice,也不会因此面临 e-Invoice 合规行动或处罚。
获豁免的企业仍可选择自愿开具 e-Invoice,以支持政府的数码化计划。