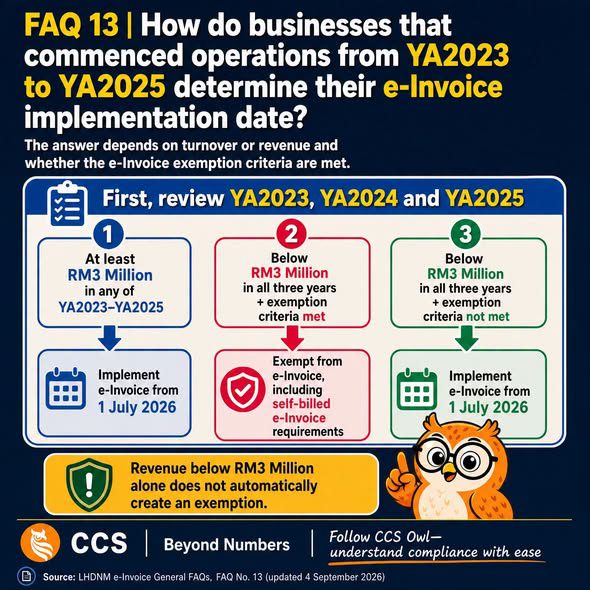
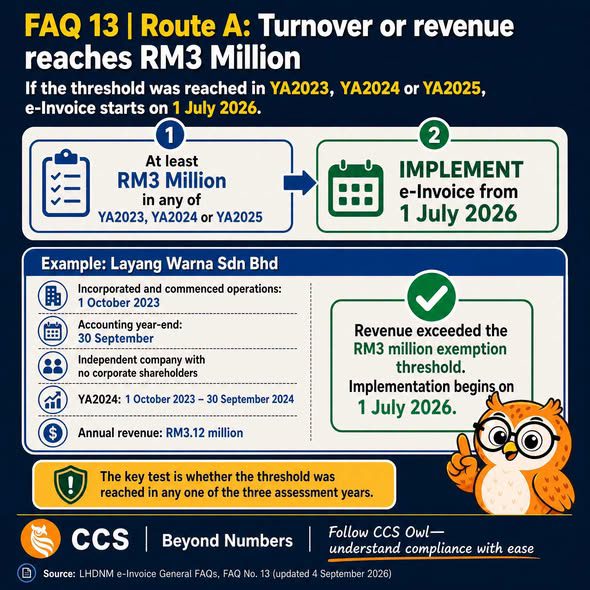
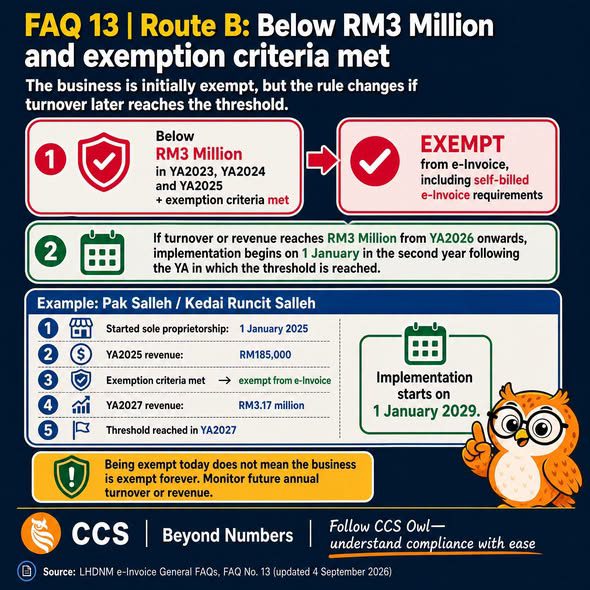
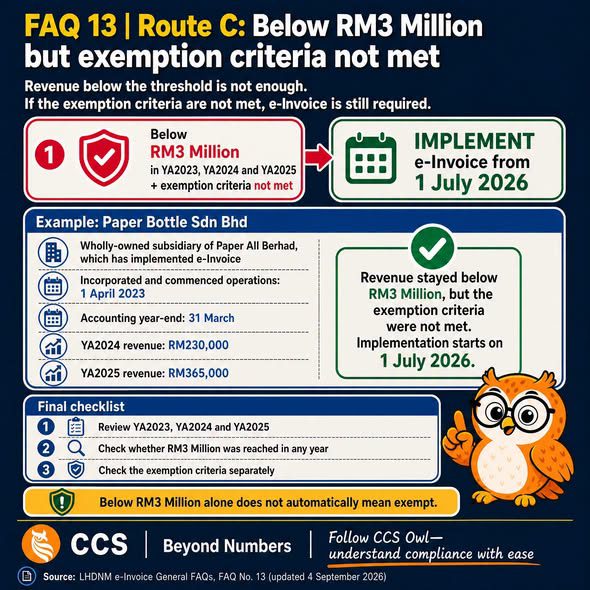
FAQ No. 13 sets out three outcomes based on a business’s revenue and whether it meets the e-Invoice exemption criteria:
- Revenue of RM3 million or more in any of YA 2023, YA 2024 or YA 2025: Implement e-Invoice from 1 July 2026.
- Revenue below RM3 million in all three years, and exemption criteria met: The business is exempt. The requirement will apply if the business reaches the RM3 million threshold in a future year.
- Revenue below RM3 million in all three years, but exemption criteria not met: Implement e-Invoice from 1 July 2026.
In short: Check both the revenue threshold and the exemption criteria to determine the applicable implementation date.
e-Invoice常见问题第13条:根据YA 2023至YA 2025收入确定实施时间
常见问题第13条根据企业的收入及其是否符合 e-Invoice 豁免条件,列出三种情况:
- YA 2023、YA 2024或YA 2025任何一个年度的收入达到或超过RM300万:从2026年7月1日起实施 e-Invoice。
- 三个年度的收入均低于RM300万,且符合豁免条件:企业可获豁免。若企业未来达到RM300万门槛,相关要求将重新适用。
- 三个年度的收入均低于RM300万,但不符合豁免条件:从2026年7月1日起实施 e-Invoice。
简单来说:企业应同时检查收入门槛及豁免条件,以确定适用的实施日期。