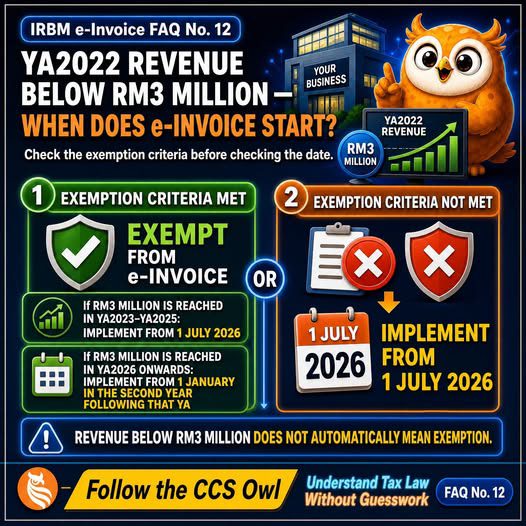
FAQ No. 12 explains how the e-Invoice implementation date is determined by reference to a business’s turnover and whether it meets the exemption criteria.
If the Business Meets the Exemption Criteria
If turnover for YA 2022 was below RM3 million, the business is generally exempt. However:
- If turnover reached RM3 million in YA 2023, YA 2024 or YA 2025, the e-Invoice requirement takes effect from 1 July 2026.
- If the RM3 million threshold is reached only in YA 2026 or a later year, implementation begins on 1 January of the second year following the YA in which the threshold was reached.
If the Business Does Not Meet the Exemption Criteria
Even if turnover for YA 2022 was below RM3 million, the business must begin implementing e-Invoice from 1 July 2026 if it does not meet the exemption criteria.
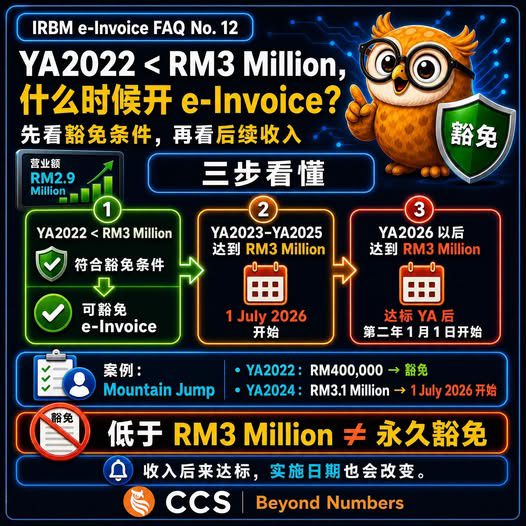
e-Invoice常见问题第12条:根据YA 2022至YA 2025营业额确定实施日期
常见问题第12条说明,e-Invoice的实施日期取决于企业的营业额,以及企业是否符合豁免条件。
符合豁免条件的企业
如果企业在YA 2022的营业额低于RM300万,原则上可获豁免。不过:
- 如果企业在YA 2023、YA 2024或YA 2025达到RM300万门槛,e-Invoice要求将从2026年7月1日起生效。
- 如果企业直到YA 2026或之后才达到RM300万门槛,则从达到门槛所在YA之后第二年的1月1日开始实施。
不符合豁免条件的企业
即使企业在YA 2022的营业额低于RM300万,只要不符合豁免条件,仍须从2026年7月1日起开始实施 e-Invoice。