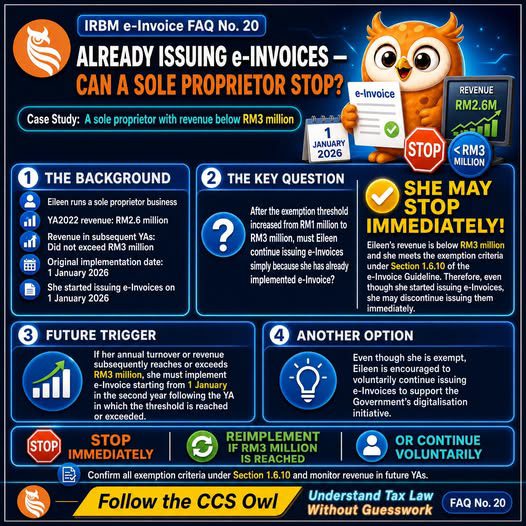
Eileen operates a sole proprietorship. Her turnover was RM2.6 million in YA 2022, and it did not exceed RM3 million in subsequent Years of Assessment. She also meets the exemption criteria in Section 1.6.10.
Accordingly, even though Eileen has been issuing e-Invoices since 1 January 2026, she may stop immediately.
If her turnover reaches or exceeds RM3 million in a future year, she must resume issuing e-Invoices from 1 January of the second Year of Assessment following the YA in which the threshold is reached.
Even while exempt, Eileen may choose to continue issuing e-Invoices voluntarily in support of the Government’s digitalisation initiatives.
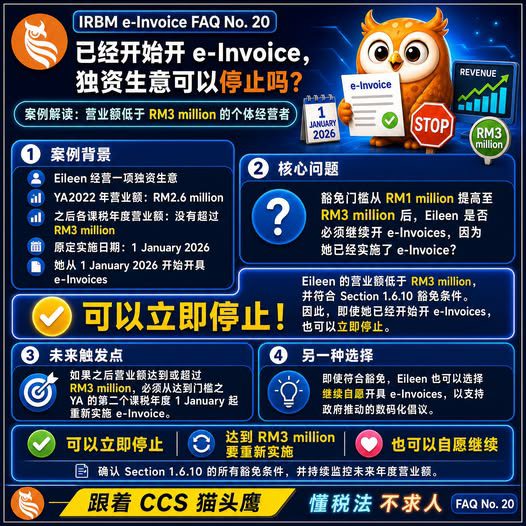
e-Invoice豁免:Eileen可立即停止开具 e-Invoice
Eileen经营独资生意。她在YA 2022的营业额为RM260万,之后各课税年度的营业额均未超过RM300万,并符合第1.6.10节所列的豁免条件。
因此,即使Eileen已从2026年1月1日起开具 e-Invoice,也可以立即停止。
如果她未来的营业额达到或超过RM300万,就必须从达到门槛所在课税年度之后第二个课税年度的1月1日起,重新开始开具 e-Invoice。
即使符合豁免条件,Eileen仍可选择继续自愿开具 e-Invoice,以支持政府推动的数码化计划。