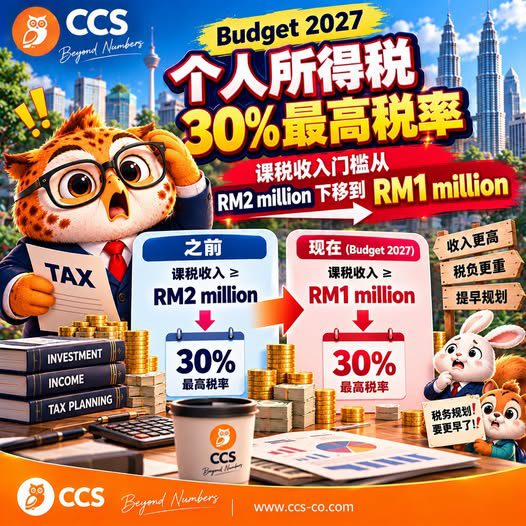
Budget 2027 proposes retaining Malaysia’s highest personal income tax rate at 30%, while lowering the chargeable income threshold at which it applies.
Previously, the 30% rate applied to the portion of chargeable income exceeding RM2 million. Under the proposed change, it would apply to the portion exceeding RM1 million.
Malaysia uses a progressive tax system. The 30% rate would not apply to a taxpayer’s entire income, but only to the portion that falls within the highest tax band. Income in the lower bands would continue to be taxed at their respective rates.
Example
Suppose a Malaysian tax resident has annual chargeable income of RM1.5 million. Under the proposed change, the portion above RM1 million would be RM500,000:
RM500,000 × 30% = RM150,000
This RM150,000 is the tax on the portion in the highest band, not the taxpayer’s total income tax payable. The remaining income would be taxed at the applicable rates for the lower bands.
The proposed change is worth noting for higher-income individuals, particularly those with substantial salaries, bonuses, directors’ fees or other taxable income. Reviewing one’s tax position in advance can help with planning and budgeting.
A higher tax band is not a reason to deliberately earn less. The focus should be on proper tax planning and accurate reporting.
Budget 2027:个人所得税30%最高税率拟适用于超过RM100万的部分
《2027年财政预算案》提出维持马来西亚个人所得税30%的最高税率,同时下调适用该税率的课税收入门槛。
过去,超过RM200万的课税收入部分适用30%税率。根据拟议调整,超过RM100万的部分将适用30%税率。
马来西亚采用累进税率制度。30%税率并非适用于纳税人的全部收入,而只适用于落入最高税阶的部分;较低收入区间仍按各自适用税率计算。
举例说明
假设一名马来西亚税务居民的年度课税收入为RM150万。根据拟议调整,超过RM100万的部分为RM500,000:
RM500,000 × 30% = RM150,000
这RM150,000是最高税阶部分的税额,并非该纳税人的全年所得税总额。其余收入仍按较低税阶的适用税率计算。
对于高收入人士而言,这项拟议调整值得关注,尤其是有高额薪资、奖金、董事酬金或其他应课税收入的人士。提前检视个人税务状况,有助于做好规划与预算。
税阶提高并不是刻意减少收入的理由。重点应是妥善进行税务规划,并准确申报收入。