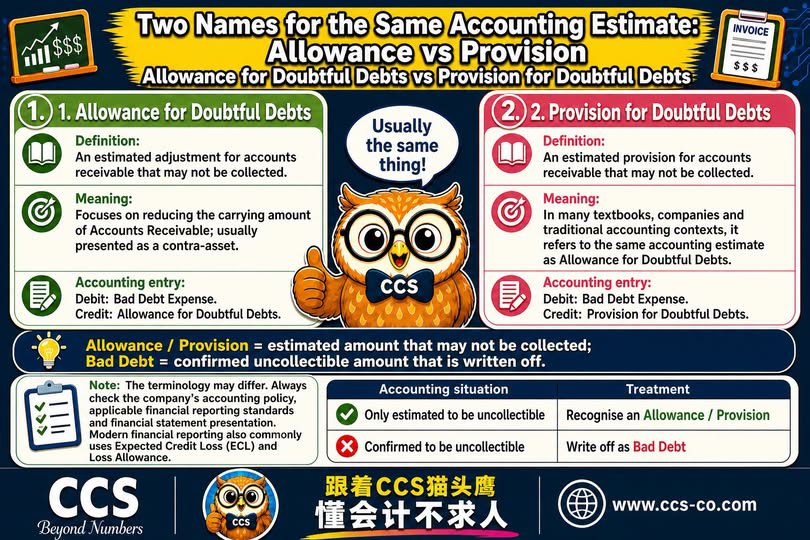
Many business owners and accountants see the terms Allowance for Doubtful Debts and Provision for Doubtful Debts and wonder whether they represent different accounting treatments.
In many textbooks, businesses and traditional accounting contexts, the two terms generally refer to a similar accounting estimate: an amount recognised for trade receivables that may not be collected.
A Simple Example
A customer’s balance becomes overdue, and the business estimates that part of the amount may not be recoverable.
The balance should not immediately be written off as a confirmed bad debt because the loss has not yet been fully established.
The business may use either of the following terms in its accounting records:
- Allowance for Doubtful Debts; or
- Provision for Doubtful Debts.
Both are generally presented as a contra-asset against Accounts Receivable. This helps present the receivables at a more prudent estimated recoverable amount.
Allowance, Provision and Bad Debt
Allowance or Provision
An allowance or provision is recognised when an amount is estimated to be potentially uncollectible.
This does not necessarily mean that the customer has definitely refused to pay. It represents an estimate of the amount that may not ultimately be recovered.
Bad Debt
A bad debt arises when the amount is confirmed to be uncollectible and is written off.
The key distinction is:
An estimated loss is not the same as a confirmed loss.
Typical Accounting Entries
When recognising an allowance or provision:
Dr Bad Debt Expense
Cr Allowance/Provision for Doubtful Debts
When the balance is subsequently confirmed to be uncollectible and written off:
Dr Allowance for Doubtful Debts or Bad Debt Expense
Cr Accounts Receivable
If the allowance is insufficient to cover the amount written off, the difference may be recognised as an additional bad debt expense, subject to the applicable accounting requirements.
Key Reminders
- In many accounting contexts, “Allowance” and “Provision” are different terms used to describe a similar accounting estimate. However, the company’s accounting policy and the applicable financial reporting standards should always be checked.
- Neither term necessarily means that the customer has definitely refused to pay.
- Once the amount is confirmed to be uncollectible, it moves to the bad debt write-off stage.
- Modern financial reporting commonly uses terms such as Expected Credit Loss (ECL) and Loss Allowance.
- Before year end, review the Accounts Receivable Ageing Analysis, customer payment history and available recovery evidence to avoid overstating receivables.
In simple terms:
An allowance or provision reflects an estimated potential loss. A bad debt write-off reflects a confirmed loss.
CCS | Beyond Numbers
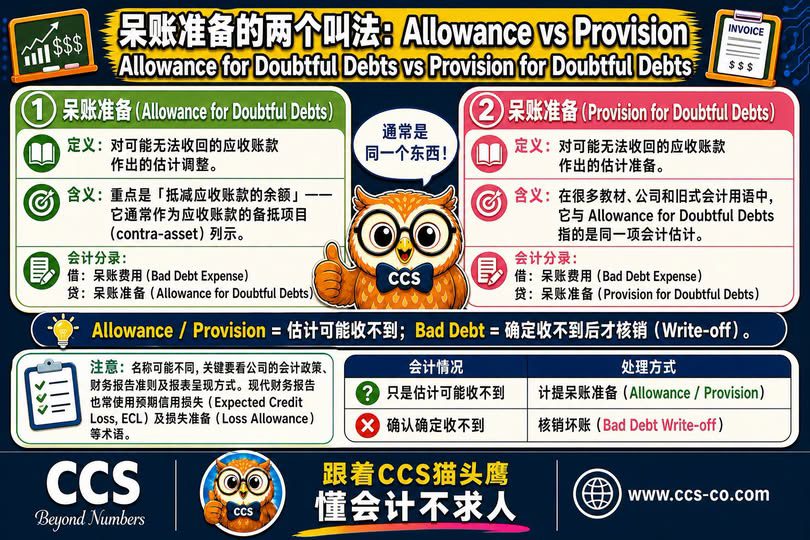
Allowance 和 Provision,到底是不是同一个东西?
很多老板和会计看到 Allowance for Doubtful Debts 与 Provision for Doubtful Debts 时,都会问:
这两个名称是不是代表不同的会计处理?
在许多教材、企业及传统会计语境中,这两个词通常都是指类似的会计估计,也就是针对可能无法收回的应收账款,先确认一项呆账准备。
一个简单例子
客户账款出现逾期,企业估计其中一部分可能无法收回。
这时,企业还不能直接把它当作已经确定的坏账进行核销,因为损失尚未完全确认。
企业可以在会计记录中使用以下其中一个名称:
- Allowance for Doubtful Debts;或
- Provision for Doubtful Debts。
这两者一般都会作为**应收账款的备抵项目(Contra-asset)**列示,用来较为谨慎地反映应收账款的预计可收回金额。
Allowance、Provision 和 Bad Debt 有什么分别?
Allowance 或 Provision
当企业估计某笔应收款项可能无法收回时,就可以确认 Allowance 或 Provision。
这并不代表客户已经确定拒绝还钱,而是表示企业估计其中一部分金额最终可能无法收回。
Bad Debt
当企业已经确认某笔款项无法收回,并将其正式核销时,才属于 Bad Debt。
关键区别是:
估计可能发生的损失,不等于已经确定发生的损失。
常见会计分录
确认呆账准备时:
借:呆账费用(Bad Debt Expense)
贷:呆账准备(Allowance/Provision for Doubtful Debts)
当款项之后确定无法收回,并进行坏账核销时:
借:呆账准备或坏账费用
贷:应收账款(Accounts Receivable)
如果原本确认的呆账准备不足以覆盖实际核销金额,差额可能需要进一步确认为坏账费用,但仍须按照适用的会计要求处理。
企业需要记住的重点
- 在许多会计语境中,Allowance 与 Provision 是两个不同的名称,但通常指类似的会计估计。企业仍应以本身的会计政策及适用的财务报告准则为准。
- 这两个词都不一定代表客户已经确定不还钱。
- 当款项确定无法收回后,才进入 Bad Debt Write-off(坏账核销)阶段。
- 现代财务报告也常使用 **Expected Credit Loss(预期信用损失,ECL)**及 **Loss Allowance(损失准备)**等术语。
- 年结前应检查应收账款账龄(Ageing Analysis)、客户付款记录及现有的追讨证据,以避免财报高估应收账款。
简单来说:
Allowance 或 Provision 代表估计的潜在损失;Bad Debt Write-off 代表已经确认的损失。
CCS | Beyond Numbers