Day: October 15, 2026

  • e-Invoice Treatment of Surplus Monies from Pawned-Goods Auctions

    e-Invoice Treatment of Surplus Monies from Pawned-Goods Auctions

    Q: Does a pawnbroker need to issue an e-Invoice for surplus monies from an auction?

    A: No.

    If the proceeds from auctioning pawned goods exceed the amount recoverable by the pawnbroker, the excess is known as Surplus Monies.

    Scenario 1: The Pawnbroker Holds the Surplus Monies

    The surplus belongs to the pawner. If the pawnbroker holds the amount on trust, no e-Invoice is required.

    Scenario 2: The Surplus Monies Are Returned to the Pawner

    If the surplus is subsequently returned to the pawner, no e-Invoice is required for the repayment.

    In short: An auction that generates surplus proceeds does not, by itself, mean that a taxable transaction has taken place. Surplus Monies belonging to the pawner do not require an e-Invoice.

    CCS Cat Owl | Beyond Numbers

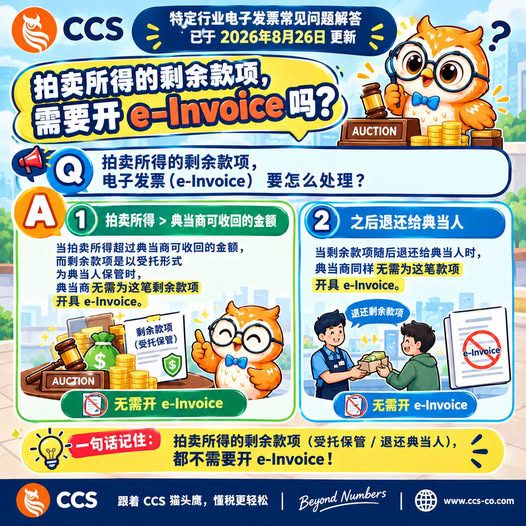
    典当物拍卖产生剩余款,需要开具 e-Invoice 吗?

    问:典当物拍卖后产生剩余款(Surplus Monies),需要开具 e-Invoice 吗?

    答:不需要。

    如果典当物拍卖所得超过典当商可收回的金额,超出的部分就是剩余款(Surplus Monies)。

    情况一:剩余款由典当商代为保管

    剩余款属于典当人。如果典当商以信托方式代为持有该款项,则无需开具 e-Invoice。

    情况二:剩余款退还给典当人

    如果之后将剩余款退还给典当人,该退款同样无需开具 e-Invoice。

    简单来说:拍卖产生剩余款,并不代表因此发生了一笔应税交易。属于典当人的剩余款无需开具 e-Invoice。

    CCS Cat Owl|Beyond Numbers
    1
  • e-Invoice Treatment of Unclaimed Surplus Monies Transferred to AGD

    e-Invoice Treatment of Unclaimed Surplus Monies Transferred to AGD

    Q: Does a pawnbroker need to issue an e-Invoice when unclaimed surplus monies from an auction are transferred to the Accountant General’s Department of Malaysia (AGD)?

    A: No.

    If surplus monies from the auction of pawned goods remain unclaimed by the pawner and are subsequently transferred by the pawnbroker to AGD, neither an e-Invoice nor a self-billed e-Invoice is required.

    In short: Unclaimed surplus monies transferred to AGD do not require an e-Invoice or a self-billed e-Invoice.

    CCS Cat Owl | Beyond Numbers

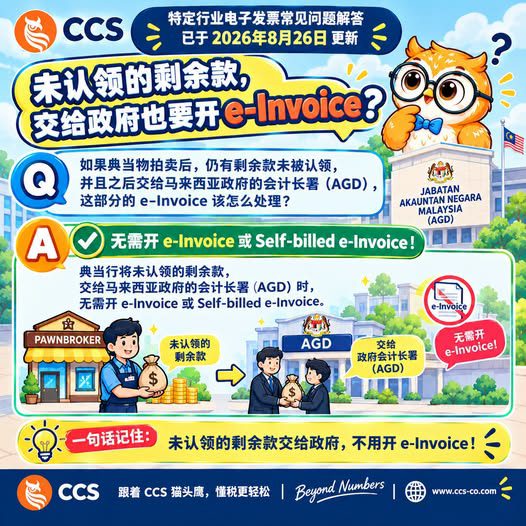
    无人认领的剩余款交给AGD,需要开具 e-Invoice 吗?

    问:典当物拍卖后产生的剩余款(Surplus Monies)一直无人认领,典当商之后将款项交给马来西亚会计总署(Accountant General’s Department of Malaysia,AGD),需要开具 e-Invoice 吗?

    答:不需要。

    如果典当物拍卖后产生的剩余款一直未由典当人领取,之后由典当商交给AGD,则无需开具 e-Invoice,也无需开具自开 e-Invoice(Self-Billed e-Invoice)。

    简单来说:无人认领的剩余款交给AGD,不需要开具 e-Invoice 或自开 e-Invoice。

    CCS Cat Owl|Beyond Numbers
  • Proposed 2027 e-Invoice Rules for E-Commerce Platforms: Cross-Border Transactions

    Proposed 2027 e-Invoice Rules for E-Commerce Platforms: Cross-Border Transactions

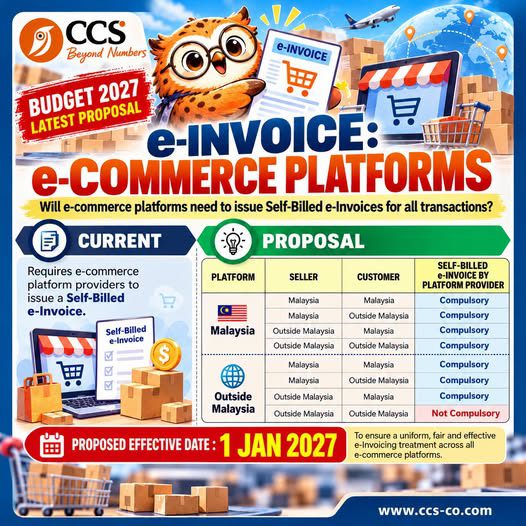
    The 2027 Budget proposes standardising how e-commerce platforms handle self-billed e-Invoices, with clearer requirements for domestic and international transactions. The proposed effective date is 1 January 2027.

    Under the proposal, platform providers would generally be required to issue self-billed e-Invoices across seven of eight transaction combinations, regardless of whether the platform is based in Malaysia or overseas.

    The scenarios specifically highlighted include:

    • Malaysian seller to Malaysian buyer;

    • Malaysian seller to overseas buyer;

    • overseas seller to Malaysian buyer; and

    • overseas seller to overseas buyer, where the platform is based in Malaysia.

    The only combination stated as outside the requirement is an overseas platform serving an overseas seller and an overseas buyer.

    The Proposal Is Not Yet Final

    This is a policy proposal under the 2027 Budget. The detailed implementation will remain subject to the guidelines and enforcement rules that the Inland Revenue Board of Malaysia (LHDN) is expected to issue.

    What Does This Mean for Sellers?

    Having a platform issue a self-billed e-Invoice may make part of the invoicing process more convenient. However, it does not necessarily mean sellers can leave all tax matters to the platform. Responsibility for issuing an invoice should not be confused with responsibility for a seller’s wider tax obligations.

    As e-commerce platforms and sellers prepare for the proposed changes, an important question remains: will the new rules make cross-border e-commerce more convenient, or increase platforms’ compliance costs?

    CCS | Beyond Numbers

    2027年拟议电商平台 e-Invoice 规则:或涵盖跨境交易

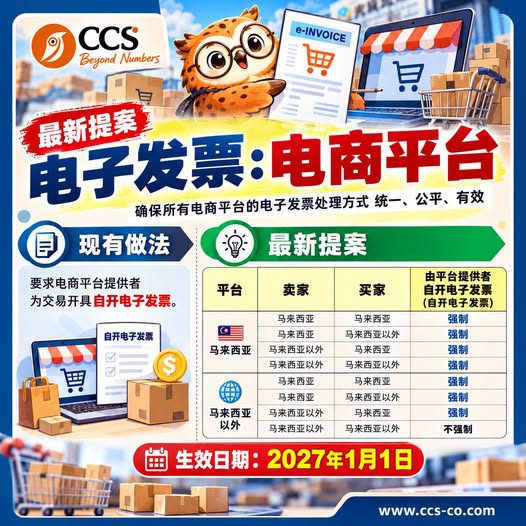
    《2027年财政预算案》提出统一电商平台处理自开电子发票(Self-Billed e-Invoice)的方式,并进一步明确国内及国际交易的相关要求。建议生效日期为2027年1月1日。

    根据这项提案,无论电商平台设在马来西亚还是海外,平台提供者原则上都须在八种交易组合中的七种情况下开具自开电子发票。

    提案特别列出的情形包括:

    • 马来西亚卖家向马来西亚买家销售;

    • 马来西亚卖家向海外买家销售;

    • 海外卖家向马来西亚买家销售;以及

    • 海外卖家向海外买家销售,而平台设在马来西亚。

    提案列明的唯一豁免组合是:海外平台、海外卖家与海外买家。

    提案尚待落实细则

    这仍是《2027年财政预算案》中的政策提案。具体实施方式仍须遵循马来西亚内陆税收局(LHDN)之后发布的指南及执行规定。

    对卖家意味着什么?

    由平台开具自开电子发票,或许能让部分开票流程更方便,但这并不代表卖家可以把所有税务事项都交由平台处理。开票责任与卖家整体税务责任并不能混为一谈。

    随着电商平台和卖家为拟议的新规作准备,一个重要问题仍值得关注:新规定会让跨境电商更便利,还是会增加平台的合规成本?

    CCS | Beyond Numbers

  • Malaysia’s e-Invoice Process Gets Easier with TIN Search and QR Code Features

    Malaysia’s e-Invoice Process Gets Easier with TIN Search and QR Code Features

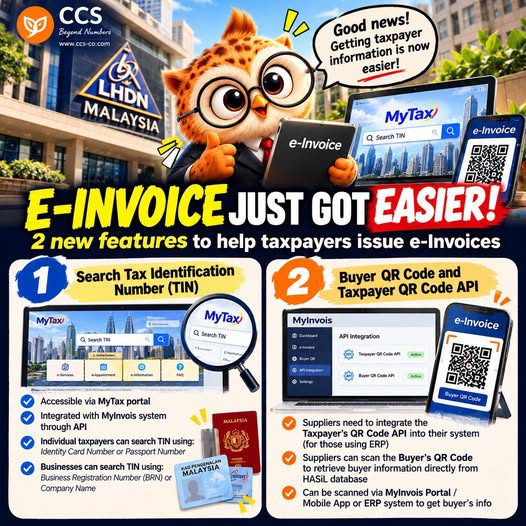
    Malaysia’s Inland Revenue Board (LHDN) has introduced two features to make e-Invoice issuance more convenient, reducing the need to repeatedly ask customers for their Tax Identification Number (TIN) and other details.

    1. Tax Identification Number Search

    TINs can be searched through the MyTax portal using:

    • an individual’s identity card or passport number; or

    • a business’s Business Registration Number (BRN) or company name.

    The search function can also be integrated with MyInvois through an API.

    2. Buyer QR Code and Taxpayer QR Code API

    Suppliers can scan a buyer’s QR code to retrieve the relevant information. This feature is available through the MyInvois Portal, the mobile app or ERP systems. Businesses using an ERP system will need the relevant API integration.

    Previously, suppliers might have had to ask customers for their TIN and company details—and perhaps a little patience. Now, they can search or scan to make the process easier.

    Convenience does not replace verification. Always check that the buyer’s information is accurate before issuing an e-Invoice.

    CCS | Beyond Numbers

    马来西亚 e-Invoice 流程更便利:新增TIN查询与二维码功能

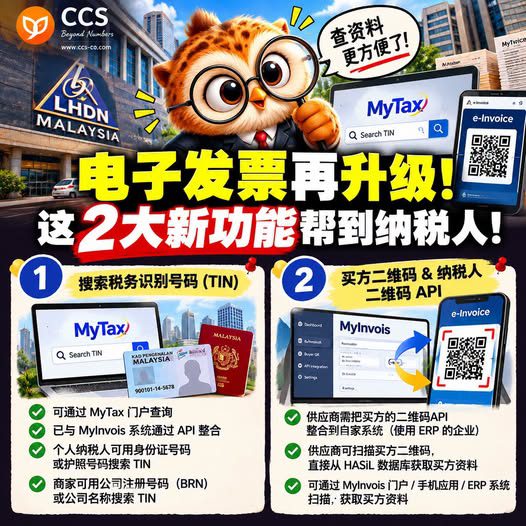
    马来西亚内陆税收局(LHDN)推出两项便利功能,让 e-Invoice 的开具流程更顺畅,也减少供应商反复向客户索取税务识别号码(TIN)及其他资料的情况。

    1. 税务识别号码(TIN)查询

    可通过 MyTax 门户查询TIN:

    • 个人:使用身份证号码或护照号码;

    • 企业:使用商业注册号码(BRN)或公司名称。

    查询功能也可通过API与MyInvois整合。

    2. 买方二维码与纳税人二维码API

    供应商可扫描买方提供的二维码,以获取相关资料。此功能可通过MyInvois门户、手机应用程序或ERP系统使用。使用ERP系统的企业需要进行相关API整合。

    以前,供应商可能需要向客户索取TIN和公司资料,还得多一点耐心。现在可以通过查询或扫码,让流程更方便。

    不过,方便并不代表可以免于核实。开具 e-Invoice 前,仍须确认买方资料准确无误。

    CCS | Beyond Numbers