Why might a manufacturer qualify for a sales tax exemption when importing eligible machinery directly or buying it from a locally registered manufacturer, but not when purchasing the same type of goods through a local trader?
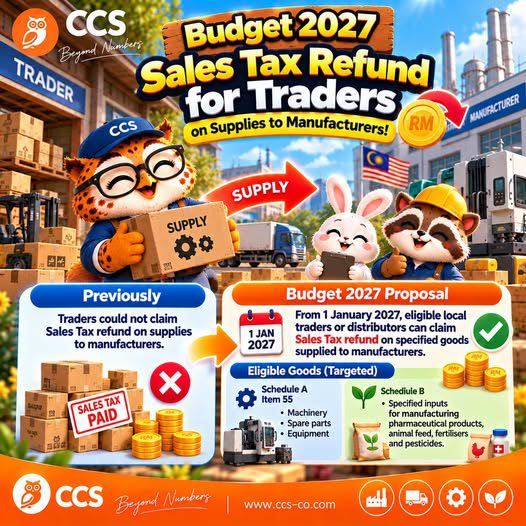
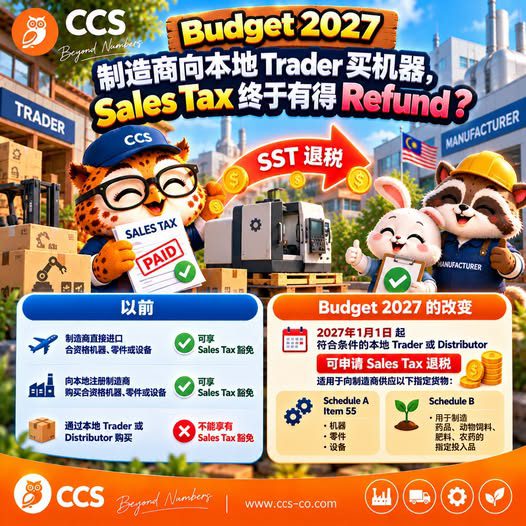
Appendix 33 of Budget 2027 proposes a Sales Tax Refund Facility to address this difference. Rather than introducing a blanket SST exemption, the proposal would allow eligible local traders or distributors to apply for a refund of sales tax already paid on specified goods supplied to manufacturers.
The Procurement-Route Difference
Under the existing arrangements described in the proposal:
- A manufacturer importing eligible machinery, parts or equipment directly may qualify for a sales tax exemption.
- A manufacturer purchasing eligible goods directly from a locally registered manufacturer may also qualify.
- Purchasing through a local trader or distributor has not been covered by the same exemption mechanism.
As a result, a manufacturer’s eligibility may depend on how the goods are procured.
What Does Budget 2027 Propose?
From 1 January 2027, local traders or distributors that have paid sales tax may be eligible to apply for a refund when supplying specified goods to manufacturers.
The proposal covers two categories:
1. Machinery, Parts and Equipment
Goods specified under Schedule A, Item 55 of the Sales Tax (Persons Exempted from Payment of Tax) Order 2018, including qualifying machinery, spare parts and equipment.
2. Specified Manufacturing Inputs
Specified inputs under Schedule B of the Exemption Order, used in the manufacture of:
Not all goods will qualify. The applicable item or schedule and its requirements will need to be checked.
Who Is Intended to Apply?
The proposed refund mechanism is intended for local traders or distributors that have paid the relevant sales tax and supplied eligible goods to manufacturers. It should not be assumed that manufacturers themselves will apply directly for this refund simply because they bought goods from a trader.
What Is the Policy Intended to Address?
The proposal aims to reduce the cost of doing business and strengthen local supply chains. Previously, manufacturers may have preferred to import directly or buy from locally registered manufacturers to access sales tax exemptions. The proposed refund facility would improve the tax treatment of local traders and distributors, potentially helping them compete on procurement costs.
Points for Businesses to Check
Machinery traders, equipment distributors and suppliers of designated manufacturing inputs should consider whether:
- the goods supplied fall under Item 55 or Schedule B;
- the business has paid the relevant sales tax;
- the customer qualifies as a relevant manufacturer; and
- procurement, tax payment and sales records are complete.
The application process and supporting-document requirements are still pending the release of implementation rules by Customs.
The proposed facility may allow eligible businesses to claim a sales tax refund, but it will not automatically recover a customer’s invoice that has been overdue for 180 days. A tax refund may be claimable; recovering a bad debt is another matter.
CCS | Beyond Numbers
Budget 2027:拟为向制造商供货的贸易商设立销售税退款机制
为什么制造商直接进口合资格的机器,或向本地注册制造商购买时,可能享有销售税豁免;但通过本地贸易商购买同类货物,却未必享有相同待遇?
《2027年财政预算案》附录33提出设立销售税退款机制,以处理这项差异。这并非全面豁免SST,而是拟允许符合条件的本地贸易商或分销商,就已缴纳销售税的指定货物申请退款。
采购渠道带来的差异
根据提案所述的现有安排:
- 制造商直接进口合资格的机器、零件或设备,可能符合销售税豁免条件。
- 制造商直接向本地注册制造商购买合资格货物,也可能符合豁免条件。
- 通过本地贸易商或分销商采购,则未被纳入相同的豁免机制。
因此,制造商是否符合条件,可能取决于货物的采购渠道。
Budget 2027提出什么措施?
从2027年1月1日起,已缴纳销售税的本地贸易商或分销商,在向制造商供应指定货物时,拟可申请退款。
提案涵盖两类货物:
1. 机器、零件与设备
《2018年销售税(获豁免缴税人士)命令》附表A第55项所列货物,包括符合条件的机器、零件及设备。
2. 指定制造业投入品
豁免令附表B所列、用于制造以下产品的指定投入品:
并非所有货物都符合退款条件,须核对适用项目或附表及其具体要求。
哪些企业拟可申请?
这项拟议退款机制适用于已缴纳相关销售税,并向制造商供应合资格货物的本地贸易商或分销商。制造商仅仅因为向贸易商购买货物,并不代表可以直接申请这项退款。
政策希望解决什么问题?
这项提案旨在降低企业经营成本并加强本地供应链。过去,制造商可能为了享有销售税豁免,倾向于直接进口,或向本地注册制造商采购。拟议的退款机制将改善本地贸易商和分销商的税务待遇,并有望提升他们在采购成本方面的竞争力。
企业应检查的事项
机器贸易商、设备分销商及指定制造业投入品供应商,应考虑确认:
具体申请程序及所需证明文件,仍有待海关公布实施细则。
符合条件的企业或可申请销售税退款,但这并不代表政府会自动替企业追回逾期180天的客户发票。税款或许可以申请退款,坏账则是另一回事。
CCS | Beyond Numbers