Day: August 25, 2023

  • Income Tax (Exemption) (No. 3) Order 2023:New Principal Hubs

    Income Tax (Exemption) (No. 3) Order 2023:New Principal Hubs

    IN exercise of the powers conferred by paragraph 127(3)(b) of the Income Tax Act 1967 [Act 53], the Minister makes the Income Tax (Exemption) (No. 3) Order 2023 [P.U. (A) 252/2023]. This Order, alongside the earlier Income Tax (Exemption) (No. 2) Order 2023, was gazetted by the Minister of Finance to provide tax incentives for principal hub companies operating in Malaysia.

    While the No. 2 Order offers a tax exemption for existing principal hubs, the No. 3 Order introduces a more attractive 10-year (initial 5 years + potential 5-year extension) income tax exemption specifically targeting new principal hub companies incorporated in Malaysia.

    Both orders aim to promote the growth and development of principal hubs to transform Malaysia into a global supply chain hub. The incentives reflect the government’s commitment to spurring investments and economic activities through the principal hub initiative. Here is a summary of the key points of the Income Tax (Exemption) (No. 3) Order 2023 [PUA 252/2023], with remarks on differences from the Income Tax (Exemption) (No. 2) Order 2023 [PUA 251/2023]:

    • This applies to new companies incorporated in Malaysia as principal hubs without existing entities carrying out qualifying services.
      • (differs from Order No.2, which covers existing companies)
    • Provides 10-year (initial 5 years + potential 5-year extension) income tax exemption on statutory income from qualifying services and trading activities
      • (differs from the 5-year partial exemption in No.2)
    • Minimum number of full-time new employees in Malaysia with a minimum salary of twenty-five thousand ringgit per month for Category 5, 4 for Category 2
      • (No.2: 5)
    • Minimum RM10 million annual operating expenditure for Category 1, RM5 million for Category 2
      • (differs from RM10-13 million in No.2)

    Similarity:

    • Separate source and accounts for exempt vs. non-exempt income
      • (same as No.2)
    • Tax losses disregarded during and after the exempt period
      • (same as No.2)
    • Excludes companies granted other incentives/exemptions
      • (same as No.2)
    • Minimum paid-up capital exceeds RM2.5 million.
      • (same as No.2)
    • The Minister may withdraw the exemption granted.
    • The Minister may, at any time, except where the principal hub fails to comply with any conditions imposed in relation to the exemption, allow the principal hub to surrender the exemption granted.

    References:-

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure the information presented is current and accurate, we cannot promise the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    7. Threads ✍ https://www.threads.net/@ccs_your_auditor

    8. 小红书 ID ✍ 2855859831

    3
  • Steps for Tax Firms to Prepare for TAeF 2.0 Transition

    Steps for Tax Firms to Prepare for TAeF 2.0 Transition

    The Inland Revenue Board of Malaysia (LHDNM) has issued a notice informing tax agents and tax firms of the upcoming launch of the new TAeF 2.0 system in November 2023.

    The enhanced Tax Agent e-Filing system aims to improve the efficiency and integration of tax e-services through the MyTax portal.

    In preparation for the transition, tax agents and firm administrators need to take steps to update user details, register for digital certificates, and attend demo sessions.

    The notice highlights critical features of TAeF 2.0, requirements for existing users, and opportunities for pilot testing. Tax firms are advised to make the necessary preparations to ensure a smooth changeover to the new system by the targeted rollout date.

    Key highlights:

    • TAeF 2.0 login will be through the MyTax portal. Ensure all users have individual TINs and digital certificates.
      • If the user does not have a TIN (Individual), please register via e-Daftar at https://mytax.hasil.gov.my/ no later than 30 September 2023 to ensure smooth data migration in October 2023
      • For users who still failed to register the TIN and IDC, users’ data will not be migrated to TAeF 2.0
    • Only tax agents approved by the Ministry of Finance can submit e-Forms. Taxpayers to appoint agents in MyTax.
    • Tax agents can access the ledger, refund status, taxpayer’s address and instalment schedule through MyTax if given functional permission by taxpayers.
    • Modern interface, enhanced features like integration with other LHDNM systems
    • Tax firms must update user details by 31 August 2023 for data migration. Use valid NRIC/passport numbers.
    • Attend the TAeF 2.0 demo webinar in September 2023. Registration opens on 6 September 2023, limited to 1,000 pax.
    • Pilot test opportunities will be available for Klang Valley firms in October 2023. Submit details by 15 September if interested.

    Please prepare your firm and users for the transition to TAeF 2.0 by the launch date. Visit the LHDNM website or email [email protected] for assistance.

    Reference:-

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure the information presented is current and accurate, we cannot promise the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    7. Threads ✍ https://www.threads.net/@ccs_your_auditor

    8. 小红书 ID ✍ 2855859831

    6
  • LHDNM to Enforce Mandatory Use of e-Tax Services in Stages from 1 September 2023

    LHDNM to Enforce Mandatory Use of e-Tax Services in Stages from 1 September 2023

    In line with technological transformation and digitisation of tax services, the Inland Revenue Board of Malaysia (LHDNM) will enforce mandatory use of e-Services for online tax services through the MyTax portal starting 1 September 2023.

    This is to empower and sustain the digitisation of service delivery to the public.

    The implementation supports the government’s aim to increase fully online end-to-end (E2E) services in stages, expected to be fully implemented by 1 January 2024.

    It is part of LHDNM’s efforts to instil Awareness, Education and Services (A.E.S.) at all LHDNM Service Counters.

    Taxpayers are encouraged to switch to E2E services in all transactions, including using online payment methods provided to make payments to ensure that all recorded transactions are safe and in order.

    The list of mandatory e-Services can be accessed via https://www.hasil.gov.my/e-perkhidmatan/, while user guides are available on the MyTax portal at https://mytax.hasil.gov.my/.

    Any inquiries and feedback can be submitted via Hasil Care Line 03-8911 1000 / 603-8911 1100 (overseas), HASiL Live Chat, or Feedback Form at https://maklumbalaspelanggan.hasil.gov.my/.

    Reference:

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure the information presented is current and accurate, we cannot promise the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    7. Threads ✍ https://www.threads.net/@ccs_your_auditor

    8. 小红书 ID ✍ 2855859831
    7
  • Form SST-ADM & Form SST-ADM 2:Voluntary Declaration of Taxes Under Sales Tax and Service Tax Act

    Form SST-ADM & Form SST-ADM 2:Voluntary Declaration of Taxes Under Sales Tax and Service Tax Act

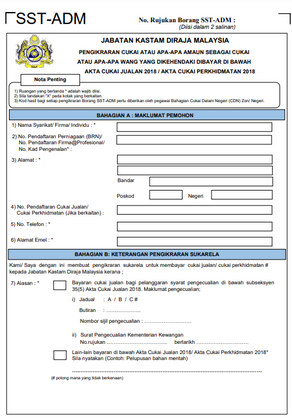
    The Royal Malaysian Customs Department (RMCD) has issued the following forms on its MySST website on 1 August 2023.

    Here is a summary of the SST-ADM and SST-ADM 2 forms:

    SST-ADM

    Purpose: For voluntary declaration to pay sales or service tax to Royal Malaysian Customs Department.

    Used when:

    1. Declaring sales tax for breach of exemption conditions under the Sales Tax Act 2018
    2. Other payments under the Sales Tax Act 2018 or Service Tax Act 2018
      • Must state reason and details of declaration.

    SST-ADM 2

    Purpose: For voluntary declaration to pay sales tax for goods acquired under Sales Tax (Person Exempted from Payment of Tax) Order 2018.

    Used when:

    • Breach of sales tax exemption conditions
    • Other voluntary payments under the Sales Tax or Service Tax Acts

    Key Notes:

    • Get the Kod Hasil for each payment from the Customs Domestic Taxes Division.
    • The declaration does not prevent Customs from audits or legal action for any breach.
    • Pay at the designated collection centres listed.
    • Ensure forms are completed and signed in duplicate copies.

    References:-

    7
  • Notification of Functions of Company Director and Director’s Representative in MyTax for Submission

    Notification of Functions of Company Director and Director’s Representative in MyTax for Submission

    Starting from 1 January 2023, taxpayers with the role of Company Director in MyTax can appoint representatives online.

    The appointed representative must possess a Tax Identification Number (TIN) and an Individual Digital Certificate.

    The Inland Revenue Board of Malaysia (LHDNM) reserves the right to obtain a letter of appointment for the representative, which should be on the company’s letterhead and signed by the company’s Board of Directors.

    LHDNM has enhanced the functions of the roles of Director and Director’s Representative in MyTax as follows:

    1. The appointment of representatives by Directors in MyTax is not limited. However, the respective Directors are responsible for their appointed representatives.
    2. Directors and representatives within the same appointment hierarchy can enter data and access e-Borang within the same assessment year.
    3. Appointed representatives are only allowed to review and input data. The system will not permit these representatives to submit and sign e-Borang forms.
    4. Submission and signature of e-Borang forms can only be made by taxpayers with the role of Company Director in MyTax, in line with the provisions of Section 75(1) of the Income Tax Act 1967 (ACP 1967).
    5. The system will only store the most recent inputted data. Therefore, Directors must ensure the data is accurate before submitting and signing the relevant e-Borang forms.
    6. This function applies to e-C and e-PT for the assessment years 2022 and 2023. It will be extended to all e-Borang forms for the specified assessment years in stages.

    Thank you.

    关于在 MyTax 公司董事和董事代表在提交 e-Borang 表格方面的功能通知

    自2023年1月1日起,担任公司董事角色的纳税人可以在 MyTax 线上委任董事代表(Director’s Representative)。

    被委任的代表必须拥有纳税识别号(TIN)和个人数字证书。

    马来西亚内陆税收局(LHDNM)保留向公司董事索取委任董事代表信函的权利,该信函应在公司信头纸 (Letterhead) 上,并由公司董事会签署。

    马来西亚内陆税收局(LHDNM)已增强了MyTax中董事和董事代表角色的功能,具体如下:

    1. 在 MyTax 中由董事委任的董事代表数量不受限制。然而,相关董事应对其所委任的董事代表负责。
    2. 同一委任层级内的董事和董事代表,可以在同一评估年度内输入数据并游览 e-Borang。
    3. 被委任的董事代表仅允许审核和输入数据。系统不会允许这些董事代表提交和签署 e-Borang 表格。
    4. 只有根据1967年所得税法令 (ITA 1967) 第75(1)条的规定,在 MyTax 中担任公司董事角色的纳税人,才能提交和签署 e-Borang 表格。
    5. 系统只会存储最近输入的数据。因此,在提交和签署相关的 e-Borang 表格之前,董事必须确保数据准确。
    6. 此功能适用于2022年和2023年的评估年度 (assessment year) 的 e-C 和 e-PT。将逐步扩展到所指定评估年度的所有类型的 e-Borang 表格。

    谢谢。

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure the information presented is current and accurate, we cannot promise the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    7. Threads ✍ https://www.threads.net/@ccs_your_auditor

    8. 小红书 ID ✍ 2855859831
    8