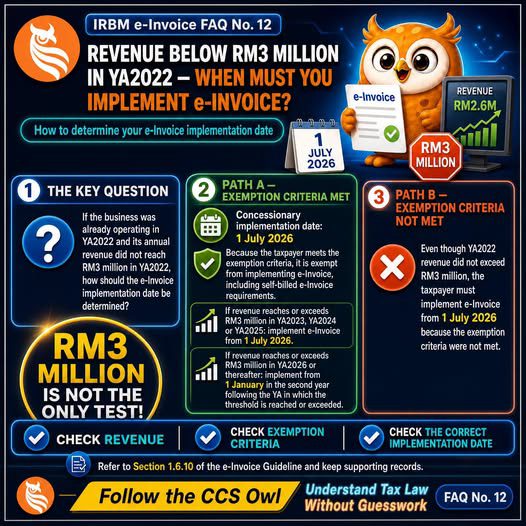
Turnover below RM3 million in YA 2022 does not automatically exempt a business from implementing e-Invoice. The business must also meet the exemption criteria in Section 1.6.10 of the e-Invoice Guideline.
Businesses that meet the exemption criteria are exempt from implementing e-Invoice, including self-billed e-Invoice. The implementation date depends on when the RM3 million threshold is reached and whether the exemption criteria are met:
- Threshold reached in YA 2023, YA 2024 or YA 2025: Implementation must begin on 1 July 2026.
- Threshold reached in YA 2026 or a later year: Implementation must begin on 1 January of the second tax year following the YA in which the threshold was reached.
- Exemption criteria not met: Implementation must begin on 1 July 2026, even if turnover in YA 2022 was below RM3 million.
Key reminder: RM3 million is not the only test. Businesses should check their turnover, whether they meet the exemption criteria and the implementation date that applies to their circumstances.
e-Invoice豁免:营业额、豁免条件与实施日期
YA 2022营业额低于RM300万,并不代表企业自动获豁免实施 e-Invoice。企业还必须符合《e-Invoice Guideline》第1.6.10节所列的豁免条件。
符合豁免条件的企业可豁免实施 e-Invoice,包括自开 e-Invoice。具体实施日期取决于企业何时达到RM300万门槛,以及是否符合豁免条件:
- 在YA 2023、YA 2024或YA 2025达到门槛:须从2026年7月1日起实施。
- 在YA 2026或之后才达到门槛:须从达到门槛所在课税年度之后第二个课税年度的1月1日起实施。
- 不符合豁免条件:即使YA 2022营业额低于RM300万,仍须从2026年7月1日起实施。
核心提醒:RM300万并非唯一判断标准。企业还应检查自身营业额、是否符合豁免条件,以及适用的实施日期。