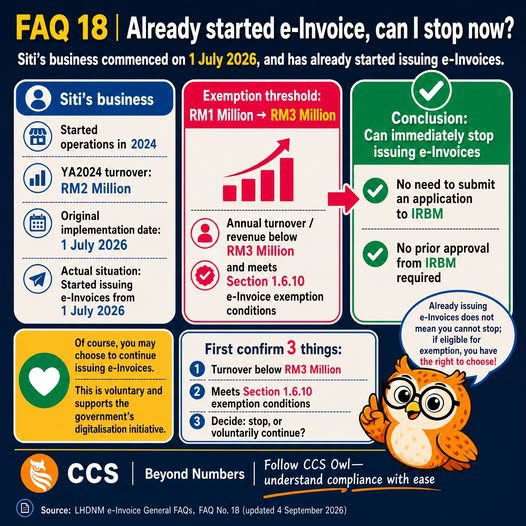
Siti commenced trading in 2024 and recorded turnover of RM2 million in YA 2024. Her business began issuing e-Invoices from its original implementation date of 1 July 2026.
Following the increase in the exemption threshold to RM3 million, and provided the business meets the exemption criteria in Section 1.6.10, it may stop issuing e-Invoices immediately.
No separate application to the Inland Revenue Board of Malaysia (IRBM) is required, and prior approval is not needed. The business may also choose to continue issuing e-Invoices voluntarily in support of the Government’s digitalisation programme.
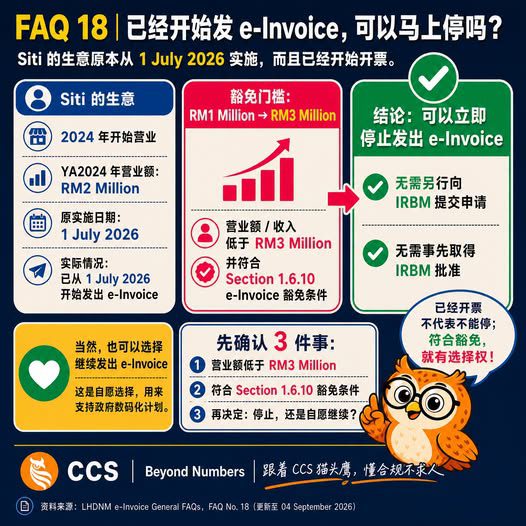
e-Invoice常见问题第18条:符合条件的企业可停止开具 e-Invoice,无需向IRBM申请
Siti于2024年开始营业,其生意在YA 2024的营业额为RM200万。企业原定从2026年7月1日起实施 e-Invoice,并已开始开具 e-Invoice。
随着豁免门槛提高至RM300万,只要企业符合第1.6.10节所列的豁免条件,即可立即停止开具 e-Invoice。
企业无需另行向马来西亚内陆税收局(IRBM)提交申请,也无需事先取得批准。企业也可以选择继续自愿开具 e-Invoice,以支持政府的数码化计划。