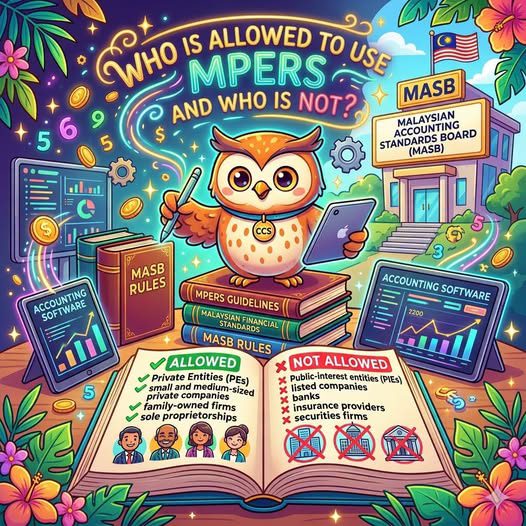
Before studying any other section, an accountant or auditor should first determine whether the entity is eligible to apply MPERS.
Section 1: Private Entities
MPERS Section 1 sets out the key eligibility requirements for private entities and explains the available choice of accounting framework.
A qualifying private entity may choose to apply either:
- MPERS; or
- MFRS Accounting Standards.
A Common Misunderstanding
Many people mistakenly believe:
Private company = Must use MPERS
This is not correct.
A private company that qualifies as a private entity may choose to apply:
- MPERS; or
- MFRS Accounting Standards.
Both frameworks may be acceptable, subject to the entity’s eligibility and the applicable requirements.
Example 1: ABC Sdn. Bhd.
ABC Sdn. Bhd. is:
- A private company;
- Generating revenue of RM5 million; and
- Not subject to public accountability.
If it satisfies the relevant eligibility requirements, the company may choose to apply either MPERS or MFRS Accounting Standards.
Example 2: Subsidiary of a Multinational Group
A subsidiary of a multinational group may qualify as a private entity under MPERS.
However, if the group’s reporting package is prepared under IFRS, management may choose to apply MFRS Accounting Standards to align the subsidiary’s financial reporting with the group’s reporting requirements.
The fact that the entity qualifies as a private entity does not mean that it must use MPERS. A qualifying private entity may choose MFRS instead.
The first step is therefore to assess the entity’s eligibility. Only after that should management decide which accounting framework is more appropriate for the entity’s reporting needs.
哪些主体可以采用 MPERS?了解适用资格与会计框架选择
在研究其他任何章节之前,会计师或审计师应先确定有关实体是否符合采用 MPERS 的资格。
第 1 节:私营实体
MPERS 第 1 节列出了私营实体的主要适用资格要求,并说明企业可以选择采用哪一种会计框架。
符合资格的私营实体可以选择采用:
- MPERS;或
- MFRS 会计准则。
常见误解
很多人误以为:
私营公司 = 必须使用 MPERS
这个理解并不正确。
符合私营实体定义的私营公司,可以选择采用:
- MPERS;或
- MFRS 会计准则。
在符合相关资格及要求的前提下,两套会计框架都可能是可以接受的选择。
示例一:ABC 私人有限公司
ABC 私人有限公司:
- 是一家私营公司;
- 收入为 RM5 million;以及
- 不承担公众问责责任。
如果公司符合相关适用资格,就可以选择采用 MPERS 或 MFRS 会计准则。
示例二:跨国集团的子公司
跨国集团的子公司可能符合 MPERS 对私营实体的定义。
不过,如果集团的报告套件是根据 IFRS 编制,管理层可以选择采用 MFRS 会计准则,使子公司的财务报告与集团报告保持一致。
企业符合私营实体资格,并不代表它必须采用 MPERS。符合资格的私营实体也可以选择采用 MFRS。
因此,第一步应先评估实体是否符合采用 MPERS 的资格。完成这项评估后,管理层才应根据企业的报告需求,决定哪一种会计框架更适合。