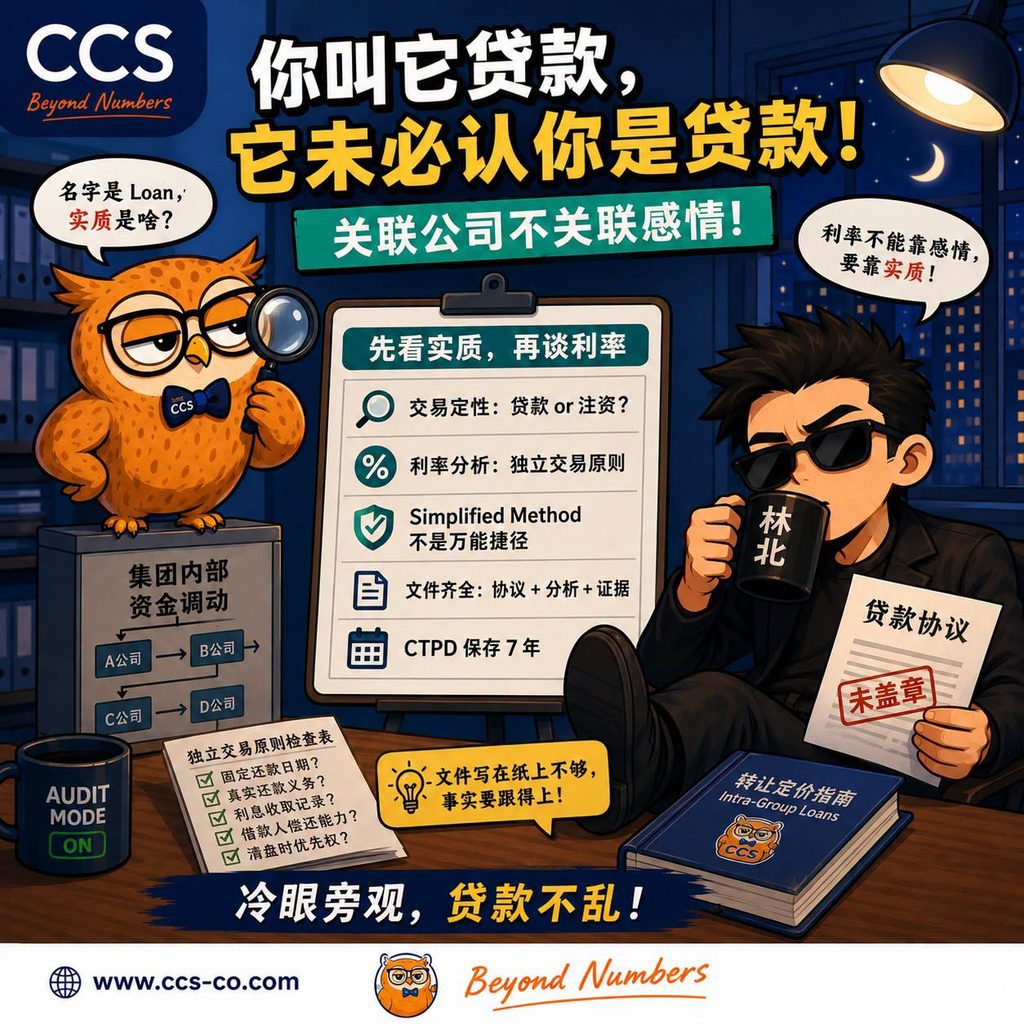
Episode One: Calling It a Loan Does Not Necessarily Make It One
At 9.00 p.m., Lin Bei was in his office. On the table were coffee, a loan agreement, financial statements and a piece of paper labelled “intra-group fund transfers”.
Robert Zai entered with a stack of documents, while Dr Foo sat opposite Lin Bei with the expression of someone who had already found a solution.
“Boss, sorry to disturb you. Dr Foo said that his property company lent RM20 million to a seafood wholesaler. The seafood company then lent the money to a construction company, and the construction company placed the funds into an e-commerce company.”
Lin Bei looked up. “Excellent. Your first assignment, and you have already encountered a financial roller coaster.”
“Roller coaster?” Dr Foo replied. “This is intra-group resource optimisation. My money is moving between different companies, and everyone is family.”
“Family?”
“Yes. The left hand lends to the right hand, and the right hand lends to the next hand. They are all my companies. The relationship is very stable.”
“I cannot comment on whether the relationship is stable. However, for transfer pricing purposes, financial assistance between associated companies does not automatically become a ‘family gift’ simply because they share the same owner.”
Robert Zai asked, “Boss, what counts as financial assistance? Must there be a formal document with the word ‘Loan’ on it?”
“Not necessarily. A loan, advance, guarantee, extended trade credit, or even a funding arrangement with no express provision for interest may be regarded as a controlled financial transaction. The key issue is not what you call it, but its actual economic substance.”
Dr Foo asked, “If I title the document ‘Friendship Support Agreement’, does that solve the interest issue?”
“No. If you rename overdue rent as a ‘space usage appreciation payment’, the rent does not disappear.”
“So the first step is not to decide the interest rate immediately, but to determine whether the arrangement is actually a loan or a capital contribution?”
“Finally, someone has asked the right question. This process is known as delineation. It involves identifying the true nature of the transaction based on the commercial and financial relationships, together with the economically relevant characteristics. Only after confirming that the arrangement is genuinely a loan should you proceed to the interest rate analysis.”
Dr Foo produced a document. “My agreement is very clear: Loan Agreement, an interest rate of 1%, and repayment after ten years. Is that sufficient?”
“A clearly drafted document only proves that you know how to draft a document. It does not automatically prove that the transaction behaves like a loan.”
“What else do we need to look at?”
“The actual conduct. Is there a fixed repayment date? Is there a genuine obligation to repay? Does the lender expect the principal to be recovered? Does the borrower have the ability to repay? Is there a fixed return? Can the lender legally enforce repayment? In a liquidation, is the fund provider a creditor, or a holder of residual equity ranking behind all creditors?”
Robert Zai summarised, “It sounds like the real question is: are you lending money, or are you giving it away?”
“Exactly. Confucius said, ‘If names are not correct, language will not accord with the truth.’ Here, the document may be called a Loan, but if the actual conduct resembles Equity, LHDN will not accept it as a loan simply because the cover page looks professional.”
Dr Foo protested, “But I genuinely intend to recover the money.”
“‘Intend’ is a very gentle word. Is there a repayment history? Have you issued demands for payment? Have you charged interest according to the agreement? If repayment is postponed every year, interest is never collected, and you eventually say, ‘We are all within the same group; there is no need to be so serious’, the arrangement may not look like a loan that an independent third party would accept.”
“What happens if LHDN considers it more similar to equity?”
“The arrangement may need to be recharacterised. Interest previously claimed as a deduction by the borrowing company may be disallowed. Taxable income may increase, and there may also be transfer pricing adjustment and surcharge risks. Based on the rules stated in the Guidelines, where the transaction does not comply with the arm’s length principle, a surcharge of up to 5% of the transfer pricing adjustment may also arise.”
Dr Foo was confused. “Wait. I lent money to my own company, and the company may not even be allowed to deduct the interest?”
“If the arrangement is not a genuine debt, you cannot package a capital contribution as an interest deduction machine. Tax is not a wishing well. Putting a Loan Agreement into it does not automatically produce a tax deduction.”
Act Two: Interest Rates Are Not Set According to the Boss’s Mood
Dr Foo asked, “All right. Assuming it is genuinely a loan, can I charge 1% interest? It is an intra-group loan, after all. We should give our own people a special rate.”
“It can be considered, but not solely according to how generous you feel today. The interest rate between associated companies should reflect the arm’s length principle. In other words, if the parties were independent of each other, what terms would independent parties agree to under similar circumstances?”
Robert Zai asked, “What should the lender and borrower consider respectively?”
“The lender should ask: If I were a bank, would I lend the money? What is the borrower’s financial position? Is its cash flow sufficient to repay the loan? Are the loan amount and tenor reasonable? Is there collateral? Who bears the interest rate risk, foreign exchange risk and default risk?”
Lin Bei continued, “The borrower should ask: Are there other financing options in the market? Is the cost of funds reasonable? Can I provide security? Will I need to refinance in the future? If the group did not provide this funding, would I borrow from a bank or another third party?”
Dr Foo shook his head. “I do not want to ask so many questions. I only want to know how much interest I can charge.”
“That is like visiting a doctor and asking immediately, ‘Can you prescribe medicine without asking where it hurts?’”
“So we need to conduct a comparability analysis?”
“Yes. The main method would generally be the CUP Method, which involves identifying comparable loans between independent third parties, bond issuances, external borrowings by the borrower or the group itself, and other reasonable market financing alternatives.
“You cannot compare only one interest rate figure. You must also consider the loan amount, tenor, currency, collateral or guarantee, seniority, purpose of the loan, market conditions and the borrower’s credit standing.”
Dr Foo replied, “All four of my companies have excellent credit because I started all of them.”
“That is an ownership relationship, not a credit rating.”
“But the group is well known. Banks feel comfortable when they see my name.”
“The group relationship may provide implicit support. In other words, being part of the group may lead the market to believe that certain companies are less likely to fail. However, this benefit cannot be overstated and used to force the interest rate down to an unreasonable level. A clear and actively provided guarantee is also not the same as passive support arising from a group relationship.”
“What if we cannot find a suitable comparable market loan?”
“You may consider the Cost of Funds Approach, based on the lender’s financing costs, operating costs, risk premium and reasonable profit margin. Related fees, such as arrangement fees and commitment fees, cannot simply be ignored.”
Dr Foo tried another approach. “What if I charge 0%? We have a good relationship.”
“The relationship may be valued at 0%, but the documents and tax analysis will not automatically become 0%. The absence of an explicitly charged interest rate does not mean that the financial assistance is completely outside the scope of transfer pricing review.”
Act Three: The Simplified Method Is Not Simplified Thinking
Robert Zai asked, “Boss, the Guidelines mention a Simplified Method. Does that mean we no longer need to conduct a comparability study?”
Dr Foo immediately announced, “Excellent! From today onwards, every loan will carry an interest rate of 0.5%. That is group efficiency.”
Lin Bei replied, “Your understanding of ‘simplification’ is similar to deleting the entire set of accounts and then saying that the documentation has become shorter.”
“So what exactly is the Simplified Method?”
“It allows eligible taxpayers to choose a prescribed interest rate without conducting a full comparability analysis. However, it does not apply automatically, nor can it be used simply because the company wishes to use it. The company must confirm each year that it continues to satisfy the relevant conditions and must still retain supporting documents.”
“Are there many conditions?”
“There are several. Based on the framework set out in the Guidelines, the company would generally need to confirm that it is not carrying on a money-lending business, that the relevant interest income is of the nature referred to under section 4(c) of the Income Tax Act 1967, that the loan is denominated in Malaysian Ringgit, and that the amount does not exceed the prescribed threshold.”
Robert Zai asked, “Are Deposit Rate and Average Lending Rate two different routes?”
“Yes. Where the Deposit Rate is used, the conditions set out in the Guidelines include that the loan is funded from internal funds, both the lender and borrower are Malaysian tax residents, and other applicable conditions are satisfied.
“Where the Average Lending Rate is used, there are also corresponding conditions, including that the aggregate amount of cross-border loans between associated companies does not exceed RM50 million, among other requirements.”
Dr Foo asked, “My group has property, seafood, construction and e-commerce companies. Does that count as ‘internal funds’?”
“That depends on the actual source of the funds, the specific arrangement and the applicable conditions, not on the number of companies you own. Owning four companies does not automatically give the four companies four times the compliance eligibility.”
“What if we do not qualify for the Simplified Method?”
“Then you cannot force the prescribed interest rate onto the arrangement. You must still conduct a comparability analysis and use the most appropriate method to determine the arm’s length interest rate. Even if the company qualifies for the Simplified Method, the tax authorities may still replace or adjust the rate if the rate used does not in substance comply with the arm’s length principle.”
Dr Foo summarised, “So the Simplified Method is a shortcut, not an invisibility cloak.”
“Good. That is finally a sentence worth including in the training materials.”
Act Four: Documents Are Not Decorations
Dr Foo said, “I have documents. Robert, bring out the agreement.”
Robert Zai looked through the papers. “Boss, there is only one page here: Company A lends money to Company B, the interest rate is ‘at market rate’, and the repayment date is ‘to be determined’.”
Lin Bei looked at the page. “This is not a loan agreement. It is a suspense story.”
“Is ‘at market rate’ not specific enough?”
“A loan agreement should clearly state the lender and borrower, financing date, amount, interest rate, interest collection policy, as well as the economically relevant characteristics and commercial purpose of the transaction. The actual arrangement must also be consistent with the document.”
“If we use the Simplified Method, what must we retain?”
“You should retain a copy of the agreement, evidence that the funds came from internal funds, confirmation of the currency, amount and loan terms, evidence that the company is not carrying on a money-lending business, evidence that the loan is denominated in Malaysian Ringgit and falls within the relevant threshold, as well as the interest rate basis obtained from official BNM or IRBM materials.”
“Do we need to keep a screenshot from the BNM website?”
“Yes. Not because the tax authorities enjoy looking at your computer screen, but because you need to demonstrate that the interest rate adopted at the time had a reliable source.”
“What about the CTPD? Does it need to be submitted together with the tax return?”
“The Guidelines state that the CTPD generally does not need to be submitted together with the tax return. However, if the DGIR requests it in writing, the relevant CTPD must be submitted within 14 days from the date of the notice.
“Relevant records, including the CTPD, should be retained for seven years and kept in Malaysia. Failure to maintain or produce the information may result in compliance and penalty risks.”
“Seven years? My seafood does not even last seven years.”
“That is why seafood spoils. Documents do not disappear on your behalf. You may think no one will look at old records, but that may simply be because they have not yet been requested.”
“That sounds like a suitable conclusion, Boss.”
“Do not be so quick. The real conclusion usually arrives in a letter from LHDN.”
Act Five: The Boss’s Final Question
Dr Foo said, “Lin Bei, I understand now. What if I cancel all the loans between the companies and rename them ‘temporary financial assistance’? Would that mean transfer pricing no longer applies?”
“You have changed the title, not the transaction.”
“What if I call it a ‘shareholder care fund’?”
“Zhuge Liang borrowed the east wind, but at least he understood the direction of the wind. You lend money to an associated company but do not even want to determine the nature of the transaction. That is not tax planning; it is playing hide-and-seek with definitions.”
Robert Zai asked, “Boss, if a company lends money to a director, does the same set of rules apply?”
“It cannot be treated in the same way. The Guidelines specifically state that a Loan or Advance to Director involves an arm’s length interest issue under section 140B of the Income Tax Act 1967 and should be considered separately. A company lending money to a director and a director lending money to a company cannot be treated as the same issue simply because both arrangements are called a loan in English.”
“So, from a tax perspective, a director lending money to a company and a company lending money to a director are not simply two sides of the same mirror?”
“They are two sides, but the mirror will not explain the tax law for you. The direction is different, the facts are different, the provisions are different, and the consequences may also be different.”
“What is the most important message in this new guidance?”
“It is not where the word ‘loan’ appears, but what the money actually represents in reality. It is also not enough for the interest rate to appear reasonable. You must consider whether the overall transaction is an arrangement that independent parties would have agreed to.”
Robert Zai asked, “What should we do now?”
Lin Bei replied:
“First, identify all intra-group funding arrangements.
“Second, determine the true nature of each arrangement: debt, capital contribution or another financial instrument.
“Third, assess the borrower’s creditworthiness, repayment capacity, tenor, currency, security and commercial purpose.
“Fourth, select the appropriate pricing method.
“Fifth, retain the agreements, analysis and supporting evidence properly.”
Dr Foo sighed. “That sounds like a lot of work.”
“Of course. The fantasy of paying less tax takes only one minute. Proving that an arrangement is reasonable usually requires documentation.”
Robert Zai said, “Boss, I finally understand why your auditors and tax advisers are still in the office at 11.00 p.m.”
“It is not because we like coffee. It is because some companies are unwilling to face their loan agreements during the day and only dare to open them at night.”
Dr Foo said, “I will ask all the companies to organise everything when I get back.”
“Good. Remember to organise the documents first, not the explanations.”
“What if I already have a loan agreement signed ten years ago?”
“You still cannot place it in a filing cabinet and hope that time will complete the debt and arm’s length analysis for you. Existing arrangements should still be reviewed, particularly loans that have remained outstanding for a long period, have terms that have not been updated, or where no interest has actually been collected and no repayments have been made.”
Lin Bei paused and said, “Du Fu wrote: ‘Knowledge gained from books alone is shallow; true understanding comes only through practice.’”
“What does that mean?”
“A loan agreement on paper is not enough. Actual repayments, interest collection, records and supporting evidence must also follow.”
Lin Bei picked up the loan agreement and concluded:
“Associated companies may share resources, but they cannot share wishful thinking.
“You may call it a loan, but LHDN will examine whether it is truly a loan. You may call it an internal arrangement, but LHDN will still look at its substance.”
Robert Zai asked, “Boss, if we keep a cool eye on things, will the loans stay under control?”
Lin Bei looked at Dr Foo. “This episode is called: Associated Companies Without Associated Feelings — Interest Rates Cannot Be Based on Feelings.”
Dr Foo asked, “Can I rely on friendship instead?”
“You can. Friendship can pay for the coffee; documentation must prove the transaction.”
This article is an entertaining adaptation based on the content of the Malaysia Transfer Pricing Guidelines relating to controlled financial transactions and intra-group loans. It does not constitute formal tax advice.
第一集:你叫它贷款,它未必认你是贷款
晚上9点,林北的办公室里,桌上放着咖啡、贷款协议、财务报表,以及一张写着“集团内部资金调动”的纸。
Robert 仔抱着文件走进来,Dr Foo 则带着一副“我已经想好办法”的表情坐在对面。
“老板,打扰一下。Dr Foo 说,他的地产公司借了 RM20 million 给海鲜批发公司,海鲜公司再借给建筑公司,建筑公司又把钱放进了电商公司。”
林北抬起头:“很好。你的第一份工作,就遇上了一辆资金过山车。”
Dr Foo 不以为然:“哪里是过山车?这是集团内部资源优化。我的钱在不同公司之间流动,大家都是自己人。”
“自己人?”
“对。左手借给右手,右手再借给后面的手。都是我的公司,感情非常稳定。”
“感情稳不稳定,我不知道。但在转让定价中,关联公司之间的金融援助,不能因为大家共用一个老板,就自动变成‘家庭红包’。”
Robert 仔问道:“老板,什么叫金融援助?一定要有正式写着 Loan 的文件吗?”
“不一定。贷款、advance、担保、延长贸易信贷,甚至没有明文规定收取利息的资金安排,都可能被视为受控金融交易。重点不是你给它取什么名字,而是它的实际经济性质。”
Dr Foo 追问:“那我把文件标题写成‘友情支持协议’,是不是就没有利息问题?”
“不会。你把‘拖欠租金’改名为‘空间使用感谢金’,租金也不会因此消失。”
Robert 仔点头:“所以,第一步不是马上决定利率,而是先判断它到底是贷款还是资本投入?”
“终于有人问到重点。这个过程称为 delineation,也就是根据商业和财务关系,以及经济上相关的特征,识别交易的真实本质。确认它确实是一笔贷款之后,才进入利率分析。”
Dr Foo 立即拿出文件:“我的协议已经写得很清楚:Loan Agreement、利率1%、十年后还款。这样够不够?”
“文件写得清楚,只能证明你很会写文件,不能自动证明交易实际上像一笔贷款。”
“那还要看什么?”
“看实际行为。有没有固定还款日期?有没有真实的还款义务?贷款方有没有期待收回本金?借款方有没有能力偿还?有没有固定回报?贷款方能不能依法追讨?在清盘时,资金提供者是债权人,还是排在所有债权人之后的剩余权益持有人?”
Robert 仔总结道:“听起来很像在问:你到底是在借钱,还是把钱送出去?”
“完全正确。孔子说:‘名不正,则言不顺。’在这里,名字叫 Loan,但实际行为像 Equity,LHDN 不会因为你的封面印得漂亮,就接受它作为贷款。”
Dr Foo 解释道:“可是我真的打算收回。”
“‘打算’是一个很温柔的词。有没有还款记录?有没有催收?有没有按照协议收取利息?如果每年都延后、每次都不收,最后还说‘集团内部不用这么认真’,那这笔钱看起来就不像独立第三方会接受的贷款。”
Robert 仔问道:“如果 LHDN 认为它比较像 equity,会发生什么?”
“可能需要重新定性。借款公司之前申报扣除的利息,可能被否定;应税收入可能增加,还可能出现转让定价调整和附加税风险。根据指南所载的规则,相关交易若不符合独立交易原则,也可能面对不超过转让定价调整5%的 surcharge。”
Dr Foo 感到不解:“等一下。我借钱给自己的公司,结果公司还不能扣利息?”
“如果那不是一笔真正的债务,当然不能把‘资本投入’包装成‘利息扣除机器’。税务不是许愿池,投一份 Loan Agreement 进去,不会自动吐出 tax deduction。”
第二幕:利率不是老板凭感觉定出来的
Dr Foo 问道:“好,假设它确实是贷款。那我收取1%利息,可以吗?集团内部嘛,给自己人一点优惠。”
“可以讨论,但不能只凭你今天的心情决定。关联公司之间的利率,应当反映独立交易原则。换句话说,假设双方不是关联公司,而是独立人士,在相似情况下会同意什么条件?”
Robert 仔问道:“那贷款方和借款方分别要考虑什么?”
“贷款方要问:如果我是银行,会不会借?借款人的财务状况如何?现金流是否足以偿还?贷款金额和期限是否合理?有没有抵押品?利率风险、汇率风险和违约风险由谁承担?”
林北继续说道:“借款方则要问:市场上有没有其他融资选择?这项资金成本是否合理?我能不能提供抵押?未来是否需要再融资?如果集团不给我这笔钱,我会不会向银行或其他第三方借款?”
Dr Foo 摇了摇头:“我不想问这么多。我只想知道可以收多少利息。”
“这就像你去看医生,一坐下就问:‘可不可以直接开药,不用问我哪里痛?’”
Robert 仔问道:“所以要做 comparability analysis?”
“是。主要方法通常是 CUP Method,也就是寻找独立第三方之间的可比贷款、债券发行、借款人或集团本身的外部借款,以及其他合理的市场融资替代方案。
“比较时不能只看一个利率数字,还要考虑贷款金额、期限、货币、抵押或担保、优先级、贷款用途、市场环境,以及借款人的信用状况。”
Dr Foo 说道:“我的四家公司信用都很好,因为都是我开的。”
“这叫股权关系,不叫信用评级。”
“可是集团有名气,银行看到我的名字就放心。”
“集团关系可能带来 implicit support,也就是集团成员身份产生的隐含支持,使市场认为某些公司比较不容易倒。但这个好处不能被夸大,用来强行把利率压到不合理的程度。真正明确、主动提供的担保,与被动形成的集团关联支持,也不是同一回事。”
Robert 仔继续问道:“如果找不到合适的市场可比贷款呢?”
“可以考虑 Cost of Funds Approach,按照贷款方的融资成本、营运成本、风险溢价和合理利润空间进行分析。贷款安排费、承诺费等相关费用,也不能假装不存在。”
Dr Foo 试探道:“那我收取0%呢?大家感情好。”
“感情可以是0%,文件和税务分析不会自动变成0%。没有收取明确利息,并不代表这项金融援助完全不需要接受转让定价审视。”
第三幕:Simplified Method 不是老板的 Simplified Thinking
Robert 仔问道:“老板,指南好像有一个 Simplified Method。是不是以后不用进行 comparability study 了?”
Dr Foo 立即宣布:“太好了!从今天开始,所有贷款利率统一为0.5%。这就是集团效率。”
林北说道:“你对‘简化’的理解,就像把整份账目删掉之后,再说‘文件变少了’。”
Robert 仔问道:“那 Simplified Method 到底是什么?”
“它是让符合条件的纳税人选择指定利率的方法,无需进行完整的可比性分析。但它不是自动适用,也不是想用就能用。企业每年都要确认自己是否仍然符合条件,并且仍须保留证明材料。”
“条件很多吗?”
“不算少。按照指南列出的框架,企业一般要先确认自己不是从事借贷业务,相关利息收入属于 Income Tax Act 1967 第4(c)条的性质,贷款以马币计价,且金额不超过规定门槛。”
Robert 仔继续问道:“Deposit Rate 和 Average Lending Rate,是不是两条不同的路?”
“对。若采用 Deposit Rate,指南列出的条件包括贷款由内部资金提供、贷款方和借款方均为马来西亚税务居民,以及其他适用条件。
“若采用 Average Lending Rate,也有相应的条件,包括跨境关联公司贷款合计不超过 RM50 million 等。”
Dr Foo 问道:“我的集团有地产、海鲜、建筑和电商,算不算‘内部资金’?”
“要看资金的真实来源、具体安排和适用条件,而不是看你有多少家公司。你拥有四家公司,不代表四家公司合起来就自动拥有四倍的合规资格。”
Robert 仔问道:“如果不符合 Simplified Method 呢?”
“那就不能硬套指定利率,仍须进行可比性分析,并采用最适合的方法确定独立交易利率。即使企业符合 Simplified Method,如果采用的利率实际上仍不符合独立交易原则,税务机关也可能进行替代或调整。”
Dr Foo 总结道:“所以,Simplified Method 是捷径,不是隐形斗篷。”
“很好,终于有一句话可以写进培训讲义。”
第四幕:文件不是装饰品
Dr Foo 拿出文件:“我有文件。Robert,把那份协议拿出来。”
Robert 仔翻了翻文件:“老板,这里只有一页:A 公司借钱给 B 公司,利率‘按市场’,还款日期‘待定’。”
林北看了一眼:“这不是贷款协议,这是未来的悬念。”
Dr Foo 问道:“‘按市场’还不够具体吗?”
“贷款协议至少要清楚写明贷款方和借款方、融资日期、金额、利率、利息收取政策,以及交易的经济相关特征和商业目的。实际安排也必须与文件一致。”
Robert 仔问道:“如果选择 Simplified Method,还需要保留什么资料?”
“要保留协议副本、资金来自内部资金的证明、货币和金额及贷款条件的确认、公司并非从事借贷业务的证明、贷款以马币计价及金额门槛的证明,以及来自 BNM 或 IRBM 官方资料的利率依据。”
Dr Foo 问道:“BNM 官网截图也要保留?”
“对。截图不是因为税务机关喜欢看你的电脑桌面,而是因为你需要证明当时采用的利率有可靠来源。”
Robert 仔又问道:“那 CTPD 要不要跟 tax return 一起提交?”
“指南提到,CTPD 通常不需要随税务申报表一起提交。但如果 DGIR 以书面通知要求提供,适用的 CTPD 必须在通知日起14天内提交。
“相关记录,包括 CTPD,应保留7年并存放在马来西亚。不备存或不能提供资料,可能带来相应的合规和处罚风险。”
Dr Foo 惊讶道:“七年?我的海鲜都没有保存七年。”
“所以海鲜会坏,文件不会替你消失。你以为旧账没有人看,只是因为它还没有被提起。”
Robert 仔说道:“老板,这句话好像很适合做结尾。”
“别急,真正的结尾通常在 LHDN 的信里。”
第五幕:老板的最后一个问题
Dr Foo 说道:“林北,我明白了。那我把公司之间的贷款全部取消,改成‘临时资金援助’,是不是就不用看转让定价?”
“你只是换了标题,不是改变了交易。”
“那改成‘股东关爱基金’?”
“孔明借东风,至少还知道风向。你借钱给关联公司,却连交易性质都不想确认,这不是税务规划,而是在定义里玩捉迷藏。”
Robert 仔问道:“老板,如果公司把钱借给董事,是不是也适用同一套规则?”
“不能混为一谈。指南特别指出,Loan or Advance to Director 涉及 Income Tax Act 1967 第140B条下的独立交易利息问题,应单独考虑。公司借钱给董事,和董事借钱给公司,不能因为英文都叫 loan,就当成同一道题。”
Dr Foo 问道:“所以董事借钱给公司,和公司借钱给董事,税务上不是镜子的两面?”
“是两面,但镜子不会替你解释税法。方向不同、事实不同、条文不同,后果也可能不同。”
“那这份新指南最重要的一句话是什么?”
“不是‘贷款’两个字写在哪里,而是这笔钱在现实中到底是什么。也不是只要利率看起来合理就结束,而是要看整项交易是否像独立人士会同意的安排。”
Robert 仔问道:“老板,那我们现在要做什么?”
林北答道:
第一,盘点集团内部所有资金安排。
第二,确认每一笔安排的真实性质,是债务、资本投入,还是其他金融工具。
第三,评估借款人的信用能力、还款能力、期限、货币、担保和商业用途。
第四,选择合适的定价方法。
第五,妥善保存协议、分析和证据。
Dr Foo 叹道:“听起来有很多工作。”
“当然。少缴税的幻想只需要一分钟,证明安排合理通常需要文件。”
Robert 仔说道:“老板,我现在终于知道为什么你们审计师和税务顾问晚上11点还在办公室了。”
“不是因为我们喜欢咖啡,而是因为有些企业的贷款协议,白天不敢面对,晚上才敢打开。”
Dr Foo 说道:“那我今天回去就叫所有公司整理。”
“很好。记得先整理文件,不要先整理说辞。”
“如果我已经有一份十年前签署的贷款协议呢?”
“也不能只把它放进档案柜,然后祈祷时间会替你完成债务与独立交易分析。现有安排仍然值得重新检视,特别是长期未偿还、条款没有更新、没有实际收取利息或进行还款的贷款。”
林北想了想,说道:“杜甫说:‘纸上得来终觉浅,绝知此事要躬行。’”
Dr Foo 问道:“意思是?”
“贷款协议写在纸上还不够,实际还款、收息、记录和证据也必须跟得上。”
林北拿起贷款协议,总结道:
“关联公司之间可以共享资源,但不能共享侥幸。
“你叫它贷款,LHDN 会看它是不是贷款;你叫它内部安排,LHDN 还是会看它的实质。”
Robert 仔说道:“老板,冷眼旁观,贷款不乱?”
林北看向 Dr Foo:“这一集叫——关联公司不关联感情,利率不能靠感情。”
Dr Foo 问道:“那我可以靠友情吗?”
“可以。友情负责请咖啡,文件负责证明交易。”
本文根据《Malaysia Transfer Pricing Guidelines》有关受控金融交易及集团内部贷款的内容进行娱乐化改写,不替代正式税务意见。