Many companies assume that once a contract has been signed, the process is complete.
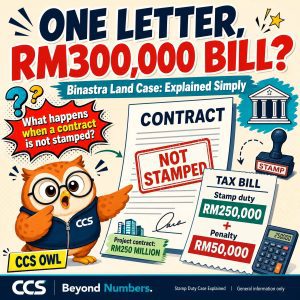
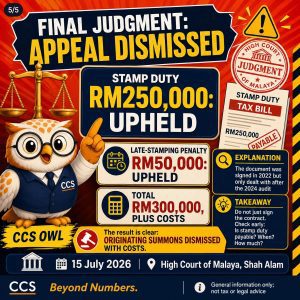
However, in Binastra Land Sdn Bhd & Anor v. Pemungut Duti Setem, a document titled “Letter of Award” ultimately resulted in:
- RM250,000 in stamp duty; and
- RM50,000 in penalties for late stamping.
This brought the total amount to RM300,000, excluding litigation costs.
A Letter of Award That Set the Entire Project in Motion
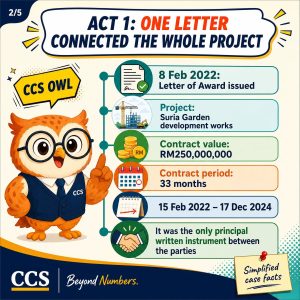
On 8 February 2022, Binastra Land appointed another party to participate in the Suria Garden development project through a Letter of Award.
The contract was valued at RM250,000,000 and had a term of 33 months, beginning on 15 February 2022 and ending on 17 December 2024.
Importantly, the Letter of Award was the sole primary written document between the parties. It set out the scope of the project services, payment arrangements and the parties’ related responsibilities.
The Company Said There Was No Stamp Duty
The company advanced two main arguments.
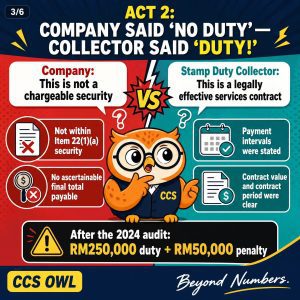
First, it argued that the Letter of Award was not a “security” as defined under the Stamp Duty Act 1949.
Second, it argued that the contract did not specify a determinable final payment amount. Therefore, stamp duty should not be imposed under Item 22(1)(a) of the First Schedule to the Stamp Duty Act.
The Stamp Duty Officer took a different view. According to the officer, the document was a legally binding service contract with a clear payment schedule, a defined contract term and a calculable contract amount. It was therefore a document subject to stamp duty.
Why Did the Court Rule That Stamp Duty Was Payable?
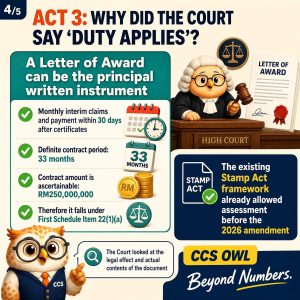
The High Court held that it was not sufficient to focus solely on whether a document was titled a “Letter of Award”. The court also had to consider the actual role played by the document in the transaction.
The court noted the following:
Clear payment schedule
The contract required interim claims to be submitted monthly, with payment to be made within 30 days after the issuance of the relevant certificates.
Defined contract term
The project had a clearly specified term of 33 months, together with stated commencement and completion dates.
Clearly defined contract amount
The total contract amount was RM250,000,000, and the final amount payable could be calculated on an identifiable basis.
The court therefore concluded that the Letter of Award was a legally binding principal written document containing service obligations and payment arrangements. It fell within the scope of Item 22(1)(a) of the First Schedule to the Stamp Duty Act.
Could the Stamp Duty Be Assessed in 2024?
Another issue was whether stamp duty could be assessed in 2024, given that the new provisions relating to the relevant process had not yet taken effect.
The company argued that the new provisions would only take effect on 1 January 2026. It therefore contended that the Stamp Duty Officer had no authority to issue an assessment in 2024.
The court rejected this argument.
It held that, before the new provisions took effect in 2026, the original Sections 3A, 36, 38A and 39 of the Stamp Duty Act had already provided legal mechanisms for requiring the production of documents, assessing stamp duty, filing objections and bringing appeals.
In other words, the introduction of the new provisions did not establish that the Stamp Duty Officer had no authority whatsoever under the previous law.
Final Judgment: Company’s Appeal Dismissed
On 15 July 2026, the Shah Alam High Court dismissed the company’s application and ordered the company to bear the litigation costs.
The outcome was as follows:
| Item | Amount |
|---|---|
| Stamp duty | RM250,000 |
| Penalty for late stamping | RM50,000 |
| Total | RM300,000 |
The court also confirmed that the documents had been signed in 2022, but the stamp duty was only processed after the 2024 audit. This triggered the penalty provisions for late stamping.
The penalty amounted to 20% of the RM250,000 stamp duty, which was RM50,000.
Three Reminders for Business Owners
1. The document’s title is not the determining factor
Whether a document is called a “Letter of Award”, “Confirmation Letter” or “Letter of Appointment” does not necessarily mean that it is exempt from stamp duty.
The court will examine the document’s actual legal effect and function within the transaction.
2. Check stamp duty requirements when the document is signed
Businesses should not wait until an audit, inquiry or dispute arises to discover that a contract was signed long ago but was not stamped within the required time.
3. Confirm the applicable requirements
Businesses should confirm:
- whether stamp duty is payable;
- when it must be paid; and
- how much is due.
Conducting a stamp duty review promptly is often more cost-effective than dealing with additional taxes, penalties and litigation costs after the event.
Conclusion
Signing a contract is only the first step. Confirming the related stamp duty obligations is the true end point of the compliance process.
This case also serves as a reminder that, in tax and legal matters, the document title is merely the packaging. The court’s primary focus is the substantive content of the contract and the legal effect it produces.
CCS | Beyond Numbers
The above content is provided for general reference only and does not constitute tax or legal advice.
The stamp duty treatment of any document should be analysed on a case-by-case basis, having regard to the document’s specific contents, the date of signing, the payment arrangements and the applicable laws.
一封 Letter of Award 为何最终带来 RM300,000 的印花税账单?
许多公司都认为,合同一旦签署,整个程序就已经完成。
然而,在 Binastra Land Sdn Bhd & Anor v. Pemungut Duti Setem 一案中,一份名为“Letter of Award”的文件,最终导致:
- RM250,000 的印花税;以及
- RM50,000 的迟延盖印罚款。
因此,公司最终面对的金额为 RM300,000,另加诉讼费用。
一封启动整个项目的 Letter of Award
2022 年 2 月 8 日,Binastra Land 通过一封 Letter of Award,委任另一方参与 Suria Garden 发展项目。
该合同价值 RM250,000,000,期限为 33 个月,从 2022 年 2 月 15 日开始,至 2024 年 12 月 17 日结束。
重要的是,这封 Letter of Award 是双方之间唯一的主要书面文件,并列明了项目服务范围、付款安排以及双方相关的责任。
公司认为无需缴付印花税
公司提出了两项主要论点。
第一,公司认为该 Letter of Award 并不属于 Stamp Duty Act 1949 所定义的“security”。
第二,公司认为该合同并没有列明一个可以确定的最终付款金额。因此,根据 Stamp Duty Act 第一附表 Item 22(1)(a),该文件不应被征收印花税。
Stamp Duty Officer 则持有不同看法。该官员认为,这是一份具有法律约束力的服务合同,具备明确的付款时间表、确定的合同期限以及可以计算的合同金额。因此,该文件属于应缴付印花税的文件。
为什么法院裁定必须缴付印花税?
High Court 认为,不能仅仅根据文件是否被命名为“Letter of Award”来作出判断。法院也必须考虑该文件在有关交易中实际发挥的作用。
法院注意到以下几点:
付款时间表明确
合同规定,中期索赔必须按月提交,并须在相关证明书发出后的 30 天内付款。
合同期限明确
该项目的合同期限明确为 33 个月,并列明了开始日期及完成日期。
合同金额明确
合同总额为 RM250,000,000,而最终应付金额也可以根据明确的基础计算出来。
因此,法院认为,该 Letter of Award 是一份具有法律约束力的主要书面文件,包含服务义务及付款安排,属于 Stamp Duty Act 第一附表 Item 22(1)(a) 的范围。
在 2024 年是否可以作出印花税评估?
另一个争议点是,由于有关新条文尚未生效,印花税是否可以在 2024 年被评估。
公司主张,有关新条文要到 2026 年 1 月 1 日才生效。因此,Stamp Duty Officer 无权在 2024 年发出评估。
法院驳回了这项论点。
法院认为,在 2026 年新条文生效之前,Stamp Duty Act 原有的第 3A、36、38A 及 39 条,已经提供了要求提交文件、评估印花税、提出反对以及提出上诉的法律机制。
换句话说,新条文的引入并不能证明 Stamp Duty Officer 在旧法下完全没有作出有关评估的权力。
最终判决:公司申请被驳回
2026 年 7 月 15 日,Shah Alam High Court 驳回了公司的申请,并下令由公司承担诉讼费用。
最终结果如下:
| 项目 | 金额 |
|---|---|
| 印花税 | RM250,000 |
| 迟延盖印罚款 | RM50,000 |
| 总额 | RM300,000 |
法院也确认,有关文件在 2022 年已经签署,但印花税直到 2024 年审计之后才处理,因此触发了迟延盖印的罚款条文。
有关罚款为 RM250,000 印花税的 20%,即 RM50,000。
给企业主的三项提醒
1. 文件名称不是决定性因素
一份文件被称为“Letter of Award”、“Confirmation Letter”或“Letter of Appointment”,并不代表该文件必然豁免印花税。
法院会审查该文件的实际法律效力,以及它在有关交易中的实际功能。
2. 在签署文件时检查印花税要求
企业不应等到审计、调查或争议发生后,才发现一份合同早已签署,却没有在规定期限内完成盖印。
3. 确认相关要求
企业应确认:
- 是否需要缴付印花税;
- 何时必须缴付;以及
- 应缴付多少印花税。
及时进行印花税审查,通常比事后处理额外税款、罚款及诉讼费用更具成本效益。
总结
签署合同只是第一步。确认相关的印花税责任,才是合规程序真正完成的标志。
这宗案件也提醒我们,在税务及法律问题上,文件名称只是表面形式。法院真正关注的,是合同的实质内容以及该合同所产生的法律效力。
CCS|Beyond Numbers
以上内容仅供一般参考,并不构成税务或法律意见。
任何文件的印花税处理,都应根据个案进行分析,并考虑文件的具体内容、签署日期、付款安排及适用法律。