You sold goods worth RM100,000 to a customer. The customer requested 60 days’ credit, and you agreed because it was a long-standing customer.
The accounts now show:
Trade receivable: RM100,000
At year end, the customer has not gone bankrupt or disappeared. The customer still answers calls, but payment behaviour has begun to change:
- Payment that previously took 30 days now takes 60 days;
- Then 90 days; and
- Responses such as “The cheque is being prepared” or “The boss is travelling” become increasingly common.
The question is:
If the customer has not formally defaulted, should an impairment loss be recognised?
The answer depends on whether the company applies MFRS 9 or MPERS 2025.
MFRS 9: Do Not Wait Until the Loss Becomes Obvious
For companies applying the MFRS framework, trade receivables generally fall within the scope of MFRS 9 Financial Instruments.
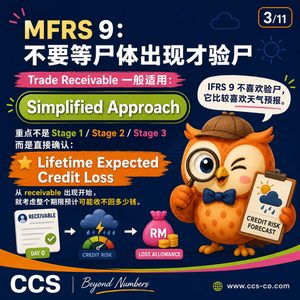
For ordinary trade receivables without a significant financing component, MFRS 9 generally requires the use of the simplified approach.
The focus is not on applying the three-stage model mechanically:
- Stage 1;
- Stage 2; and
- Stage 3.
Instead, the entity generally recognises lifetime expected credit losses (Lifetime ECL) from the initial recognition of the trade receivable.
In other words, the entity considers, from the outset, how much it expects not to recover over the receivable’s expected life. It does not wait until the customer is formally bankrupt before recognising a loss allowance.
MFRS 9 does not wait for the “body” to appear. It prefers a forecast of the financial weather.
What Is Expected Credit Loss?
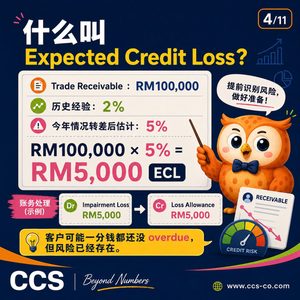
Assume that the company has a trade receivable of RM100,000.
Historical information shows that similar customers have resulted in an average loss rate of 2%. However, current conditions have deteriorated:
- The customer’s industry is experiencing a downturn;
- The customer’s cash flow has weakened; and
- Economic forecasts have become less favourable.
After making reasonable adjustments, the company estimates an expected loss rate of 5%.
The expected credit loss would be:
RM100,000 × 5% = RM5,000
The accounting entry would be:
Dr Impairment loss RM5,000
Cr Loss allowance RM5,000
The customer may not yet have missed a payment or become overdue. However, if credit risk is already present, MFRS 9 does not permit the company to ignore it.
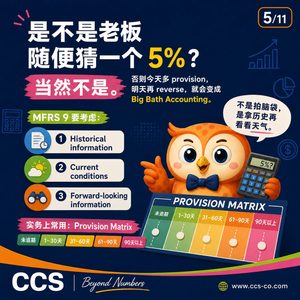
Is the Loss Rate Based on Management’s Guess?
No.
Otherwise, management could increase provisions when profit is high and reverse them when profit is under pressure. This could result in a form of earnings management sometimes referred to as “big bath accounting”.
MFRS 9 requires the assessment to consider:
- Historical information — How many similar customers failed to pay in the past?
- Current conditions — What is the current financial position of the customer and its industry?
- Forward-looking information — What is the expected future economic environment?
In practice, a company may use a provision matrix with different expected loss rates for:
- Balances that are not overdue;
- 1–30 days overdue;
- 31–60 days overdue;
- 61–90 days overdue; and
- More than 90 days overdue.
The rates should then be adjusted for current and forward-looking economic conditions.
IFRS 9 expressly permits a provision matrix as a practical expedient for measuring ECL on trade receivables.
It is not a matter of guessing. It is a matter of using historical experience and considering the financial outlook.
MPERS 2025: The Incurred Loss Model Remains
This is where the analysis differs.
Some may assume that MPERS 2025, being a revised standard, must have adopted the IFRS 9 ECL model. It has not.
MPERS 2025, which is based on the third edition of the IFRS for SMEs Accounting Standard, retains the incurred loss model rather than fully adopting the IFRS 9 expected credit loss model.
Therefore, a private entity applying MPERS 2025 does not generally recognise lifetime ECL from Day 1.
Instead, at the reporting date, it considers whether there is objective evidence of impairment.
Does MPERS Mean That the Customer Must Be Bankrupt?
No.
This is an important distinction.
Under MPERS 2025 Section 11, impairment evidence may include circumstances such as:
- The customer experiencing significant financial difficulty;
- The customer defaulting or becoming seriously overdue;
- The company granting a concession to the customer because of the customer’s financial difficulty;
- The customer being likely to enter bankruptcy or another form of financial reorganisation; or
- A group of receivables experiencing a measurable decline in estimated future cash flows associated with adverse economic, industry or regional conditions.
Therefore, MPERS does not mean:
“Recognise a provision only after the customer has collapsed.”
A more accurate explanation is:
Recognise impairment when objective evidence indicates that a loss event has occurred.
This is the main conceptual difference between:
- MFRS 9: Expected Credit Loss; and
- MPERS 2025: Incurred Loss Model.
The Same Customer May Be Assessed Differently
Assume a customer owes RM100,000.
At the reporting date:
- The balance is not overdue;
- There is no obvious financial difficulty; but
- Economic forecasts for the following year have deteriorated significantly.
Under MFRS 9, the company still asks:
“How much do we expect to lose in the future?”
Even if the customer is currently paying on time, a Lifetime ECL allowance may still be required.
Under MPERS 2025, the key question is different:
“At the reporting date, is there objective evidence that impairment has already occurred?”
If there is no such evidence, the company would generally not create an ECL allowance merely because future conditions may become unfavourable.
However, if the economic, industry or regional conditions have already created observable evidence of impairment, the company cannot ignore it.
Why Does MPERS 2025 Not Simply Copy MFRS 9?
The main considerations include relevance, simplicity, faithful representation, and cost versus benefit.
A complete ECL model may involve:
- Probability of default (PD);
- Loss given default (LGD);
- Exposure at default (EAD);
- Forward-looking economic scenarios; and
- Credit risk modelling.
A bank may respond:
“That is manageable. We have a risk department.”
An ordinary Sdn. Bhd. may respond:
“Our accounts department consists of one person and an intern.”
When developing the revised IFRS for SMEs requirements, the IASB considered how far the framework should align with full IFRS, taking into account relevance, simplicity, faithful representation and the related costs and benefits.
The incurred loss model was therefore retained.
When Does MPERS 2025 Take Effect?
MPERS 2025 has been issued in Malaysia, but it is mandatorily effective for annual periods beginning on or after 1 January 2027. Early application is permitted.
Therefore, if a company has not early adopted MPERS 2025, the fact that MPERS 2025 is being discussed does not mean that its current financial statements automatically apply the revised requirements.
This transition date is particularly important for auditors and preparers of financial statements.
The Key Difference
For trade receivables, remember the following:
MFRS 9
Ask:
How much do we expect to lose in the future?
This leads to:
- Expected Credit Loss;
- The simplified approach for ordinary trade receivables; and
- Generally, Lifetime ECL.
MPERS 2025
Ask:
Is there objective evidence that impairment has already occurred?
This leads to:
- The incurred loss model; and
- Recognition of impairment when objective evidence of loss exists.
A customer’s repayment depends on creditworthiness. The provision for doubtful debts must not depend on guesswork.
CCS | Beyond Numbers
A final point is worth emphasising: for ordinary trade receivables without a significant financing component under MFRS 9, the analysis should not be taught mechanically as Stage 1, followed by Stage 2 and Stage 3. The more relevant framework is:
Simplified approach → Lifetime ECL
MFRS 9 与 MPERS 2025 下的贸易应收款:为什么客户还没违约,也可能需要确认减值?
你卖了 RM100,000 的货给客户。客户说:
“老板,给我 60 天。”
因为是老客户,你答应了。
于是账上出现:
Trade Receivable:RM100,000
到了年结,客户还没有倒闭,也没有跑路,电话仍然接得通,只是付款情况开始变得不太正常:
- 以前 30 天付款,现在变成 60 天;
- 后来变成 90 天;以及
- 打电话时,对方开始说:“Cheque preparing already……”或“Boss travelling……”
问题来了:
客户还没有正式违约,要不要先确认减值?
答案取决于公司采用的是 MFRS 9 还是 MPERS 2025。
MFRS 9:不要等损失完全显现才处理
如果公司采用 MFRS Framework,贸易应收款一般属于 MFRS 9 Financial Instruments 的范围。
对于一般没有重大融资成分的贸易应收款,MFRS 9 通常要求采用简化方法(Simplified Approach)。
重点不是机械式地套用:
- Stage 1;
- Stage 2;以及
- Stage 3。
相反,企业一般会从贸易应收款初始确认开始,直接确认其整个存续期的预期信用损失(Lifetime Expected Credit Loss,Lifetime ECL)。
换句话说,企业从一开始就需要考虑:在这笔应收款预计存续期间内,可能有多少金额无法收回,而不是等到客户正式破产后才确认损失准备。
MFRS 9 不喜欢等到“尸体出现”才验尸,它比较重视提前观察财务天气。
什么是预期信用损失?
假设公司有一笔:
Trade Receivable:RM100,000
历史资料显示,类似客户过去平均有 2% 的金额无法收回。
不过,今年的情况开始恶化:
- 客户所在行业正在衰退;
- 客户现金流转差;以及
- 经济预测变得不利。
经过合理调整后,公司估计 Expected Loss Rate 为 5%。
预期信用损失为:
RM100,000 × 5% = RM5,000
会计分录为:
借:Impairment Loss RM5,000
贷:Loss Allowance RM5,000
客户可能还没有逾期,也可能还没有正式违约。
但是,如果信用风险已经存在,MFRS 9 不允许企业假装看不见。
损失率可以由管理层随便猜吗?
当然不可以。
否则,企业可能在利润较高时提高损失准备,在利润较差时又将准备转回,形成类似“Big Bath Accounting”的盈余管理行为。
MFRS 9 要求企业考虑:
- 历史资料(Historical Information)——过去类似客户有多少金额无法收回?
- 当前情况(Current Conditions)——客户及其所在行业目前的财务状况如何?
- 前瞻性资料(Forward-looking Information)——未来经济环境预计会怎样?
实务上,企业可以采用准备矩阵(Provision Matrix),根据不同账龄设置不同的预期损失率,例如:
- 尚未逾期;
- 逾期 1–30 天;
- 逾期 31–60 天;
- 逾期 61–90 天;以及
- 逾期超过 90 天。
之后,再根据当前及未来的经济情况调整相关损失率。
IFRS 9 明确允许企业使用准备矩阵,作为计量贸易应收款预期信用损失的一种实务简化方法。
这不是拍脑袋,而是参考历史经验,再结合未来的财务天气作出判断。
MPERS 2025:仍然采用已发生损失模型
这里开始出现差异。
有些人可能会以为,MPERS 2025 既然是新版标准,就应该把 IFRS 9 的 ECL 模型一起搬进来。
答案是:没有。
MPERS 2025 以第三版 IFRS for SMEs Accounting Standard 为基础,仍然保留已发生损失模型(Incurred Loss Model),并没有完整采用 IFRS 9 的预期信用损失模型。
因此,采用 MPERS 2025 的私人企业,一般不会从 Day 1 就确认整个存续期的 ECL。
企业在报告日需要问的是:
有没有客观证据显示已经发生减值?
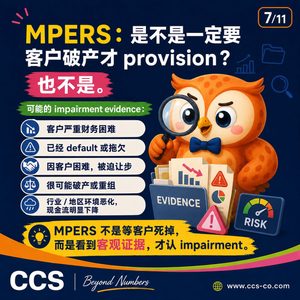
MPERS 是不是一定要等客户破产才计提?
也不是。
这一点千万不要讲错。
根据 MPERS 2025 第 11 节,以下情况都可能构成减值的客观证据:
- 客户出现严重的财务困难;
- 客户已经违约或严重拖欠;
- 因为客户的财务困难,公司被迫给予让步;
- 客户很可能进入破产或其他财务重组;或
- 某一组应收款项的预计未来现金流出现可观察的下降,而这种下降与不利的经济、行业或地区环境有关。
因此,MPERS 并不是:
“客户倒闭后才确认准备。”
更准确的说法是:
当客观证据显示损失已经发生时,才确认减值。
这就是以下两种理念之间的主要差异:
- **MFRS 9:**预期信用损失(Expected Credit Loss);以及
- **MPERS 2025:**已发生损失模型(Incurred Loss Model)。
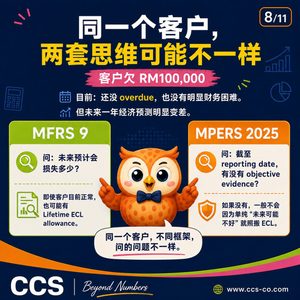
同一个客户,两套准则可能采用不同思维
假设客户欠公司:
RM100,000
在报告日:
- 款项还没有逾期;
- 客户没有明显的财务困难;但是
- 对未来一年的经济预测已经明显转差。
如果公司采用 MFRS 9
公司仍然需要问:
“未来预计会有多少金额收不回来?”
因此,即使客户目前仍然正常付款,也可能需要确认 Lifetime ECL Loss Allowance。
如果公司采用 MPERS 2025
核心问题则不同:
“截至报告日,是否有客观证据显示减值已经发生?”
如果没有这样的证据,企业一般不会单纯因为“未来情况可能变差”,就照搬 MFRS 9 的方法建立 ECL Loss Allowance。
不过,如果经济、行业或地区情况已经形成可观察的减值证据,企业就不能假装什么都没有发生。74
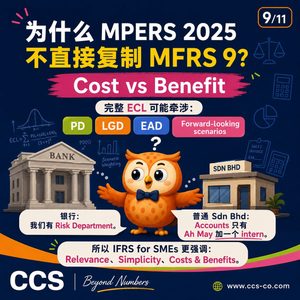
为什么 MPERS 2025 不直接复制 MFRS 9?
其中一个重要考虑是:
Cost versus Benefit(成本与效益)。
完整的 ECL 模型可能涉及:
- PD:Probability of Default,违约概率;
- LGD:Loss Given Default,违约损失率;
- EAD:Exposure at Default,违约风险敞口;
- Forward-looking economic scenarios,前瞻性经济情景;以及
- Credit risk modelling,信用风险模型。
银行可能会说:
“可以,我们有 Risk Department。”
普通的 Sdn. Bhd. 可能会说:
“老师,我们 Accounts Department 就 Ah May 加一个 Intern。”
IASB 在制定修订后的 IFRS for SMEs 要求时,仍然根据相关性、简化性、如实反映,以及成本与效益等因素,决定应在多大程度上与 Full IFRS 保持一致。
因此,MPERS 2025 最终保留了 Incurred Loss Model。
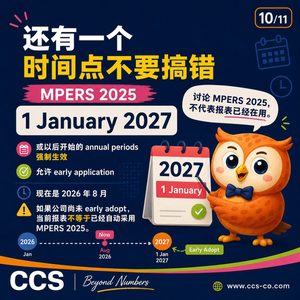
MPERS 2025 什么时候生效?
MPERS 2025 已经在马来西亚发布,但强制适用于 2027 年 1 月 1 日或以后开始的年度期间,并允许提前采用。
因此,如果公司尚未提前采用 MPERS 2025,就不能因为现在正在讨论 MPERS 2025,而认为公司目前的财务报表已经自动采用新版要求。
这个过渡时间点对于审计师和财务报表编制者都非常重要。
最重要的区别
对于贸易应收款,可以这样记忆:
MFRS 9
先问:
未来预计会损失多少?
对应的是:
- Expected Credit Loss;
- 一般贸易应收款采用 Simplified Approach;以及
- 通常确认 Lifetime ECL。
MPERS 2025
先问:
有没有客观证据显示减值已经发生?
对应的是:
- Incurred Loss Model;以及
- 当存在客观损失证据时确认减值。
客户还钱靠信用,坏账准备可不能靠感觉。
CCS | Beyond Numbers
最后再强调一点:对于 MFRS 9 下、一般没有重大融资成分的贸易应收款,不应机械地教成 Stage 1、Stage 2、Stage 3。更相关的逻辑是:
Simplified Approach → Lifetime ECL