Tag: Sales Tax Exemption

  • Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position
    Smoking cessation services at Government health clinics and hospitals have been implemented since 2000.

    Starting in 2015, this programme expanded to private health facilities, including hospitals, clinics and pharmacies, through public and private collaboration under the mQuit Programme.

    In this programme, Nicotine Replacement Therapy (NRT) is used as one of the medical treatment options for smoking cessation.

    The NRT aims to supply smokers with enough nicotine to gradually reduce the symptoms of addiction without the harmful substances resulting from burning cigarettes or heating the liquid of electronic cigarettes.

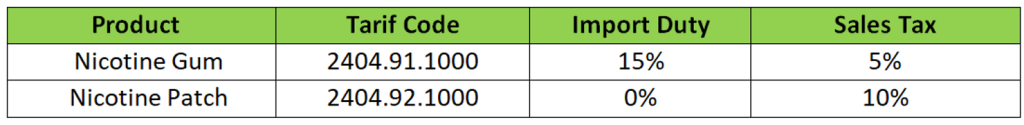
    Two NRT products in the market are subject to import duty and sales tax as follows:
    Proposal
    To support the mQuit Programme and encourage the use of NRT as an option for smoking cessation, it is proposed that import duty and sales tax exemption be given to nicotine gum and nicotine patch for a period of 3 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 April 2023 until 31 March 2026.
    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Import Duties and Sales Tax Exemption on Studio and Filming Production Equipment

    Import Duties and Sales Tax Exemption on Studio and Filming Production Equipment

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Dasar Industri Kreatif Negara has been introduced to empower the creative industries holistically based on creativity and innovation by producing high-quality products and dignifying the art and cultural heritage.

    The availability of high-tech infrastructure and a conducive ecosystem are the main catalysts to promote growth and increase the competitiveness of the local creative industry. To produce creative content with international standards, industry players, including film producers, must continue exploring innovation and taking advantage of new technologies.

    Importation of specific equipment for the creative industry, such as cameras and broadcast equipment, audio and video systems, studio equipment and filming production equipment, is subject to import duty between 5% to 30% and sales tax of 10%.

    Proposal

    To encourage industry players to produce high-quality creative content for the domestic and international markets as well as to attract foreign producers filming in Malaysia, it is proposed import duty and sales tax exemptions on studio and filming production equipment be given to equipment providers and production services, including post-production, studio and cinema for 3 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 April 2023 until 31 March 2026.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    16
  • Excise Duty and Sales Tax Exemption on the Sale or Transfer of Individually owned Taxis & Hired Cars

    Excise Duty and Sales Tax Exemption on the Sale or Transfer of Individually owned Taxis & Hired Cars

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    In Budget 2012, excise duty and sales tax exemption were given on the sale/transfer/private use/disposal of budget taxis and hired cars subject to the following conditions:

    • limited to individually owned budget taxis and hired cars only; and
    • age of the vehicle must exceed 7 years from the date of registration.

    Proposal

    To assist individual taxi owners affected by the COVID-19 pandemic, it is proposed excise duty and sales tax exemption on the sale/transfer/private use/disposal of individually owned taxis and hired cars be reviewed as follows:

    1. exemption granted based on these licenses and services:
      1. taxis (budget taxis, executive taxis and TEKS1M);
      2. airport taxis (budget and family); and
      3. hired cars
    2. vehicle age is relaxed to at least 5 years from the registration date.

    Effective Date

    For applications received by the Royal Malaysian Customs Department from 1 March 2023.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    16
  • Extension of Sales Tax Exemption for the Purchase of Locally Assembled Bus

    Extension of Sales Tax Exemption for the Purchase of Locally Assembled Bus

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    MOF's response: Off-budget.

    Current Position

    A sales tax exemption of 10% on the purchase of buses, including locally installed air conditioning, is given to eligible bus operators such as:

    1. School Buses,
    2. Stage Buses,
    3. Express Buses,
    4. Excursion Buses; and
    5. Employee Buses.

    The sales tax exemption is effective from 1 January 2021 to 31 December 2022.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    To reduce the operating costs and assist the bus operators during the transition phase to endemic, it is proposed sales tax exemption be extended for a period of 2 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 January 2023 until 31 December 2024.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    16
  • Sales Tax Policy No. 1/2022 – Sales Tax Exemption on Pallets

    Sales Tax Policy No. 1/2022 – Sales Tax Exemption on Pallets

    1. On April 11, 20222, the Royal Malaysia Customs Department (RMCD) published the Sales Tax Policy 1/2022 (“SATP 1/2022”) on its website.

    2. The SATP 1/2022, which was dated April 5, 2022, is presently only available in Bahasa Malaysia.

    3. Join our Telegram – https://t.me/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻

    1. 20222年4月11日,马来西亚皇家关税局 (RMCD)在其网站上公布了1/2022号销售税政策(‘SATP 1/2022”)。

    2. 第3/2021号服务税政策(第1号修正案)目前只有马来语版本。

    3. 加入 Telegram 群 – https://t.me/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    12