Service Tax is a consumption tax administered under the Service Tax Act 2018 and its subsidiary legislation. The effective date of the Service Tax Act 2018 is 1 September 2018.
Service tax is levied on services known as “Taxable Services”.
Any person providing taxable services exceeding the prescribed threshold is required to be registered under the Service Tax Act 2018 and known as a “registered person” and is required to charge service tax on taxable services supplied to their customers.
The Royal Malaysian Customs Department (RMCD) has released a draft Guide on Goods Delivery Services, which is expected to replace the current Guide on Courier Service dated 21 August 2019 once finalised.
This guide is provided to assist you in understanding the service tax implications relating to the delivery of goods.
Please be advised that these draft Guides are subject to change and have not been finalised yet. The RMCD has made them available to the public to obtain feedback and comments.
In accordance with the Sales Tax (Amendment) Act 2022, the Sales Tax 2018 is amended by including a new “PART IIIA” which stipulates the following:
“Low-Value Goods” is defined as “any prescribed goods or class of goods outside Malaysia which are sold at a price not more than a prescribed amount and brought into Malaysia in the manner as prescribed”;
“Seller” is defined as “a person, whether in or outside Malaysia, who sells low-value goods on an online marketplace or operates an online marketplace for the sales and purchase of low-value goods”;
“Registered Seller” covers “any seller registered under Section 13 of the Sales Tax Act 2018”.
The draft copy of Guide on Sales Tax on LVG
The draft copy of Guide on Sales Tax on LVG (as of 9 January 2023) defines “Online Marketplace (“OMP”)” as:
“an online platform that provides facilities for the sale and purchase of LVG, which includes a marketplace operated via the website, internet portal or gateway, distribution platform or any other type of electronic interface. This does not include payment processor/payment gateway or internet service provider”.
LVG refers to:
all goods;
the sale value of such goods shall be RM500 or less; and
such goods brought from outside Malaysia by land, sea or air mode into Malaysia, including SA and DA.
The Guide covers the following:-
1. Part 1 – Imposition and Scope on LVG
• Terminology
• Imposition and Scope of Tax
• Registration
• Notification of the Changes on Particulars
• Cancellation of Registration
• Accounting for Tax
• Refund of Sales Tax, Penalty, Fee or Other Money
• Remission of Penalty
• Transitional Provisions
• Other Related Information
2. Part II – Customs Clearance Procedures On The Importation Of LVG
• Terminology
• General Import Procedures
• LVG Information Requirements During Importation
• Import Declaration Via Air Mode
• Import Declaration Via Road and Sea Mode
• Importation Using Portal Service
• LVG Declaration Using The Customs Form No. 1 (K1)
• Inquiry
• Further Assistance and Information on LVG
According to the RMCD, the content of this draft guide is subject to change.
Sales Tax (Rate of Tax for Low-Value Goods) Order 2022
Sales Tax is chargeable at 10% on the sale value of LVG.
When calculating the Sales Tax payable on LVG, it is important to note that the value being considered should not include any transportation and insurance costs, as well as any tax or duties that may be chargeable or payable on the sale of LVG.
These additional costs and charges are not part of the value of the LVG being sold and, therefore, should not be included in the calculation of the Sales Tax payable.
De minimis
A treatment facility when goods imported by air using courier service (including postal service), with a total C.I.F. value not exceeding MYR500 per consignment, are exempted from Import Duties and Sales Tax on Import during importation through any airports listed under Item 94 of the Customs Duties Order (Exemption) 2017 and Item 24 of the Sales Tax (Person Exempted from Payment of Tax) 2018.
This exemption does not apply to:
cigarettes;
tobacco;
intoxicating liquor;
smoking pipes, including pipe bowls;
electronic cigarette and similar personal electric vaporising devices; and
preparation of a kind used for smoking through the electronic cigarette and electric vaporising device, in forms of liquid or gel, not containing nicotine
We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.
Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.
These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.
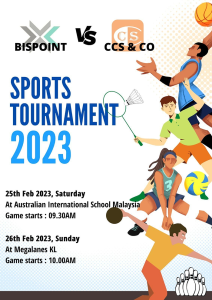
This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!
Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |