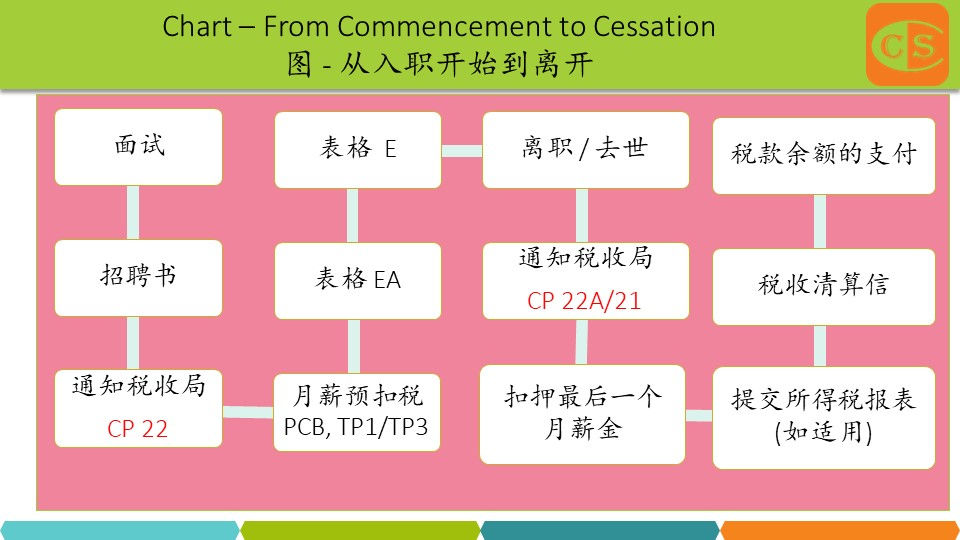
Mandatory adoption of Prescribed Forms CP 21, CP 22, CP 22A and CP 22B effective from 1 January 2022
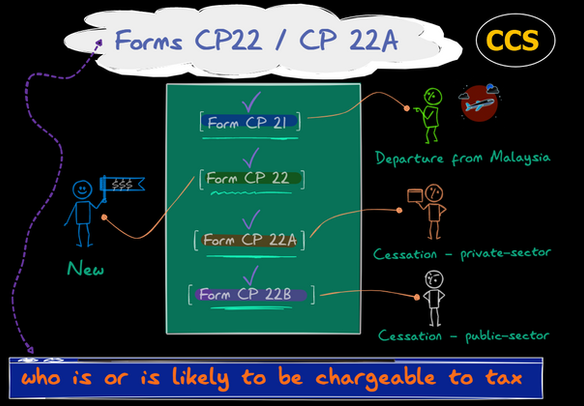
Effective January 1, 2021, under the amendments to subsections 83 (2), (3), and (4) of the Income Tax Act 1967, Forms CP 21, CP 22, CP 22A, and CP 22B must be submitted by the employers using the Forms as prescribed by the Malaysian Inland Revenue Board (IRBM) under section 152 of the Act for:
- Notification of Employee’s Departure from Malaysia;
- Notification of New Employee;
- Notification of Cessation of Employment or Death of Employees
Income Tax Act 1967
Section 83(2):
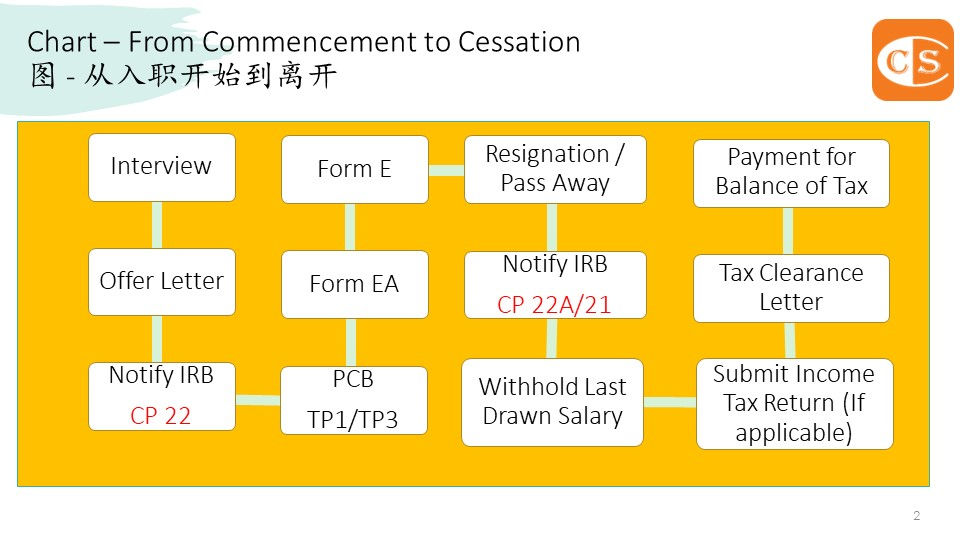
Where an employer commences to employ an individual who is or is likely to be chargeable to tax in respect of income in respect of gains or profits from the employment, the employer shall give notice in the prescribed form to the Director-General (“DG”) not later than thirty days after the commencement of the employment.
Section 82(3):
Where an employer is about to cease to employ an individual who is or is likely to be chargeable to tax in respect of income in respect of gains or profits from the employment or where an individual under his employment dies, the employer shall, not less than thirty days before the cessation of the employment, or in respect of cessation by reason of death not more than thirty days after being informed of the death of the individual, give notice in the prescribed form to the Director-General of the cessation of the employment:
Provided that, where he is satisfied that it is reasonable to do so in the circumstances, the Director-General may accept for the purposes of this subsection:
- a notice in the prescribed form given less than thirty days before the cessation of the employment, or
- a notice in the prescribed form given on or after the cessation, or
- in respect of cessation by reason of death, a notice in the prescribed form given more than thirty days after being informed of the death of the individual:
Provided further that an employer shall not be required to give the notice in the prescribed form to the Director General under this subsection in respect of an individual—
- where the income from the employment of that individual is subject to deduction under any rules made pursuant to section 154(1)(a); or
- where the total monthly remuneration from the employment of that individual is below the minimum amount of income that is subject to deduction under any rules made pursuant to section 154(1)(a),
and where it is known to him that the individual is not retiring from any employment.
Layman’s terms
According to Section 83(2) and (3), an employer who has an employee who is or is likely to be chargeable to tax is obligated to provide written notice in the prescribed form to the DG.
According to Section 83(2), 83(3), and 83(4) of the ITA, “only individual likely to be charged tax” need to give written notification using Forms CP21, Form 22, and Form 22A.
IRBM’s Practice
However, in the course of the tax audit, Unit Majikan requests that Form CP 22 be produced for all employees (including those who are not liable to income tax).
It appears that ALL newer and leavers are required to give notice via Forms CP21, 22, and 22A.
IRBM’s Response to CTIM
The MIRB has responded, dated 27 April 2022, to the above issues that were brought up in the CTIM Memorandum on Compliance and Operational Issues 1/2022 dated 12 April 2022.
Employers are responsible for reporting new employees who are taxable or likely to be taxed on Form CP22 (Prescribed Form for the Notification of New Employee) within thirty days of the date the employee began working for the company.
It is not a violation of the law for a Unit Majikan audit officer to request Form CP22 from all newly hired employees, including those who are not taxable, as part of their auditing duties.
The audit officer from Unit Majikan is asking for Form CP22 to verify and cross-reference whether or not the employer complies with the provisions of subsection 83(2) of the ITA 1967.
If the employer does not submit CP22 forms for new employees who are not eligible or taxable, the employer has the option of providing the Unit Majikan audit officer with supporting documentation, such as salary slips or any other documents that show payment of salary,
- These documents verify or prove that the employee is not eligible to be taxed.
Employers do not need to submit Forms CP 22A or CP 22B if the employee’s income is subject to a monthly tax deduction (PCB) or the employee’s monthly salary is below the minimum amount eligible for PCB. However, this is conditional on whether the employee will continue to work or not or retire from any employment in Malaysia.
It is possible to submit Forms CP21, CP22A, and CP22B online using the e-SPC service, which may be accessed through MyTax. In addition, IRBM is working to improve the e-SPC service to allow required Forms to be uploaded through the portal.
In 2023, IRBM will commence the process of developing the online submission mechanism for Form CP22.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
要获得即时更新,请与我们保持联系
1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍
- https://www.facebook.com/YourHRAdvisory/?ref=pages_you_manage
- https://www.facebook.com/YourAuditor/?ref=pages_you_manage
4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy
6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/