Tag: Malaysian Investment Development Authority

  • Automation Capital Allowance for Automation Equipment in Manufacturing, Services & Agriculture

    Automation Capital Allowance for Automation Equipment in Manufacturing, Services & Agriculture

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Automation Capital Allowance (ACA) is a tax incentive introduced in Budget 2015 to encourage manufacturers to engage in innovative and productive activities, expedite the adoption of automation, especially for labour-intensive industries, and further spur automation initiatives.

    The incentive is split into 2 categories of industries i.e.

    • Category 1: High Labour-intensive Industries (Rubber products, plastics, wood, furniture and textiles); and
    • Category 2: Industries Other than Category 1

    It was proposed in Budget 2020 that the existing Automation Capital Allowance (ACA) incentive for Category 2 of the manufacturing sector be expanded to the services sector to boost productivity and efficiency in labour-intensive industries.

    Manufacturing and services companies which incur qualifying capital expenditure on automation equipment are given tax incentives as follows:

    Category 1: Labour-Intensive Industry (rubber, plastic, wood and textile products)

    • ACA of 100% for automation equipment on the first RM4 million for Qualifying Capital Expenditure incurred and can be utilised within 1 year.

    Category 2: Industries other than Category1 including the services sector

    • ACA of 100% for automation equipment on the first RM2 million for qualifying capital expenditure incurred and can be utilised within 1 year.

    Both categories are eligible for income tax exemption equivalent to 100% of qualifying capital expenditure incurred for automation equipment. Thus, eligible capital expenditure that can be absorbed is 200%within a year.

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) until 31 December 2023.

    Guideline and Procedure for the Application of Automation Capital Allowance (Automation CA) for Services Sector – for an existing company only.

    Effective Date

    To further drive productivity and improve efficiency through automation, it is proposed the ACA for automation equipment be enhanced as follows:

    • scope of automation to include the adaptation of Industry 4.0 elements;
    • scope of tax incentives is expanded to include the agriculture sector; and
    • capital expenditure threshold for categories 1, 2 and agriculture be aligned and increased to RM10 million.

    For applications received by MIDA and the Ministry of Agriculture and Food Security (MAFS) from 1 January 2023 until 31 December 2027.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    CTIM proposed the mutually exclusive rules to be applied on an asset basis instead of a company basis.

    MOF’s Feedback:

    The proposal was duly noted.

    Further studies will be conducted regarding the mutually exclusive clause to ensure its suitability for implementation.

    For assets under hire purchase, kindly confirm there is no requirement for the hire purchase instalments to commence and end within the qualifying period from 1 January 2023 until 31 December 2027 to qualify for the accelerated capital allowance (“ACA”) claim.

    In essence, as long as it is a qualifying asset, the incentive applies to the whole capital expenditure incurred.

    LHDNM’s Feedback:

    The ACA incentive also applies to assets acquired through hire-purchase agreements.

    The eligible capital expenditure for hire-purchased assets is the principal amount incurred during the basic period of a particular assessment year for assets acquired between 1 January 2023 and 31 December 2027.

    Therefore, principal payments made outside the incentive period are not eligible to enjoy this incentive.

    ACA on capital expenditure up to RM10 million is welcomed.

    Still, there should be clarity on whether it is a 200% allowance like in the past (i.e. 100% accelerated capital allowance plus 100% automation capital allowance) or just a 100% accelerated capital allowance.

    LHDNM’s Feedback:

    This extended Accelerated Capital Allowance (ACA) incentive refers to the incentive under ACA (Automation Enhancement).

    This incentive should be read and applied with the income tax order that provides an exemption equal to 100% of the ACA (Automation Enhancement) amount.

    This exemption applies to statutory income from eligible projects but is limited to 70%.

    The characteristics of the incentive are the same as the original incentive.

    This matter will be clarified in the relevant subsidiary legislation.

    MOF’s Feedback:

    The characteristics of the incentive will be the same as the original incentive.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    19
  • Extension of Tax Incentives for the Aerospace Industry

    Extension of Tax Incentives for the Aerospace Industry

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Background to the Aerospace Industry

    Strategically located at the heart of the wider Asia-Pacific region, Malaysia sits within the world’s largest air travel market and has world-class infrastructure such as the KLIA Aeropolis, Subang Aerotech Park, Senai Aerospace Park, Serendah High-Value Manufacturing Park and Kulim Hi-Tech Park.

    With its business-friendly Government, supportive industry policies, diversified manufacturing base, and widely available industry talent, the country is a cost-effective location for projects.

    The Malaysian Government considers the industry a catalytic high-value industry under its 11th Malaysia Plan (11MP), which runs from 2016 to 2020.

    To that end, they have emphasised the development of the aerospace industry, its supply chain, and its competency through industry-led research and technology (R&T).

    On top of the 11MP initiatives, the Government has also implemented the Malaysian Aerospace Industry Blueprint 2030 (MAIB 2030) to help drive the industry’s growth.

    Underscoring the Asia-Pacific region’s air travel market growth, The Boeing Company predicts that plane demand will increase over the next decade, with the region needing almost 17,485 planes.

    The region will also account for 39% of global deliveries of passenger and freight planes over the same period. With 40% of aerospace industry growth coming from Asia-Pacific alone and a collective GDP of four ASEAN countries exceeding US$1 trillion by 2030, the industry’s future is in Asia.

    Malaysia is targeting to capture 50% of the Southeast Asian MRO business and five% of the global market by 2030, positioning the country as Southeast Asia’s top aerospace hub. Subang Aerotech Park, which offers a competitive cost base, is the country’s largest MRO centre, with local and global service providers.

    Para 61 of the 2023 Budget Speech, Prime Minister Datuk Seri Anwar Ibrahim said:

    Current Position

    New and existing aerospace companies in Malaysia undertaking high-value activities such as manufacturing or assembling of systems, devices, parts or components and maintenance, repair and overhaul for aircraft (MRO), systems, devices, parts or components and engineering & design/services related are given tax incentives as follows.

    New Company

    1. Income Tax Exemption of 70% to 100% for a period between 5 to 10 years; or
    2. Investment Tax Allowance of 60% to 100% for five years and can be set off against 70% to 100% of statutory income for each assessment year.

    Existing Company

    An Investment Tax Allowance of 60% for five years and can be set off against 70% of statutory income for each year of assessment.

    Applications are received by the Malaysian Investment Development Authority (MIDA) until 31 December 2022.

    Aerospace Industry in Malaysia:

    Download

    Proposal

    In line with the 12th Malaysia Plan to transform Malaysia into a regional key player in the aerospace industry, the proposed tax incentive will be extended for three years.

    Effective Date

    • For applications received by MIDA from 1 January 2023 until 31 December 2025.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    MOF confirmed that this incentive will apply to all manufacturing activities except those on the negative list.

    CTIM also sought confirmation on whether the extension is also applicable to companies (and C-suite employees) which carry on “Selected Services”, which are covered under Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022, i.e., service activities which adopt Industrial Revolution 4.0 and digitalisation technology undertaken by a qualifying company:

    • Provision of technology solutions or technology company which develops technology and provides technology solutions based on substantial scientific or engineering challenges;
    • Provision of infrastructure and technology for cloud computing;
    • Research and development or design and development activities;
    • Medical devices testing laboratory and clinical trials; or
    • Any service activity or manufacturing-related service activity as determined by the Minister of Finance.

    MOF’s Response:

    The incentives under Income Tax Regulations P.U. (A) 398/2022 (Relocation Services Incentive Scheme) will not be extended.

    These Rules shall apply to a qualifying company which applies in writing for the Relocation of Provision of Services Business Incentive Scheme to the Minister through the Malaysian Investment Development Authority.

    Such application is received on or after 7 November 2020 but not later than 31 December 2022.

    Reference:

    Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure the information presented is current and accurate, we cannot promise the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Tax Incentives for Manufacturer of Electric Vehicle Charging Equipment

    Tax Incentives for Manufacturer of Electric Vehicle Charging Equipment

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Under the National Automotive Policy 2020 and the Low Carbon Mobility Blueprint 2021 – 2030, Malaysia is making significant strides toward developing an ecosystem for electric mobility.

    The National Automotive Policy 2020 was launched on February 21, 2020, with the goal of improving the automotive industry during the digital industrial transformation era. Its focus is on Next-Generation Vehicles (NxGV), Industrial Revolution 4.0 (IR 4.0), and Mobility-as-a-Service (MaaS) to position Malaysia as a regional leader in manufacturing, engineering, and technology.

    The policy builds upon the objectives of the NAP 2014, which aimed to establish Malaysia as a hub for Energy Efficient Vehicles (EEV) through research and development capabilities for right-hand drive vehicles and related technologies such as fuel efficiency, light materials, telematics, tooling, and component design. To widen the infrastructure network of charging equipment, it is vital to ensure that the product can be produced locally at competitive cost.

    Proposal

    It is proposed that the following tax incentives be offered to better complement the ecosystem for electric vehicles and to attract immediate high-value investment in the manufacturing of electric vehicle charging equipment.

    • income tax exemption of 100% on statutory income from the year of assessment 2023 to the year of assessment 2032. Companies that make early investments are eligible to enjoy tax exemption for a period up to 10 years. Thus, companies that make investments after the year of assessment 2023 are eligible to enjoy the remaining exemption period only; or
    • Investment Tax Allowance of 100% for 5 years, and it can be used to offset up to 100% of statutory income for each year of assessment.

    Effective Date

    For applications received by the Malaysian Investment Development Authority (MIDA) from 25 February 2023 until 31 December 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    17
  • Application For Sales Tax Exemption Certificate Under Item 65, Schedule A of the Exemption Order

    Application For Sales Tax Exemption Certificate Under Item 65, Schedule A of the Exemption Order

    The announcement from the Royal Malaysian Customs Department (RMCD) on 20 December 2022 pertains to the Application for Sales Tax Exemption Certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.

    On 20 December 2022, the Royal Malaysian Customs Department (RMCD) released an announcement regarding the Application for a Sales Tax Exemption Certificate under Item 65 of Schedule A of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018.

    Guide on Application For Sales Tax Exemption Certificate Under Item 65, Schedule A Of The Sales Tax (Persons Exempted From Payment Of Tax) Order 2018 dated 1 January 2023 (in the Malay language) was released as a result of this.

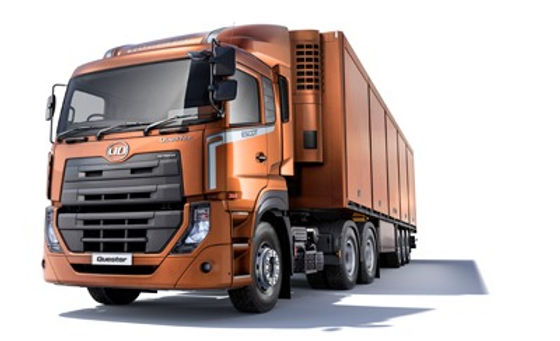
    This guide is provided to assist haulage operators registered with the Malaysian Investment Development Authority (MIDA) in the application process for a sales tax exemption certificate under Item 65, Schedule A of the Sales Tax (Persons Exempted from Payment of Tax) Order 2018 in Malaysia.

    The eligible items for sales tax exemption under this item are Prime Movers and Container Trailers, subject to the specified conditions.

    Beginning 1 January 2023, the sales tax exemption certificate applications must be made through the MySST and Vehicles Tax Exemption Monitoring System (eVTEMS) platform.

    One sales tax exemption certificate application is only for one unit of either a prime mover or a container trailer.

    Applicants are required to sign up to get eVTEMS ID access. Please refer to the User Manual (Company) via https://evtems.customs.gov.my

    For further information, please refer to the guides below:-

    1. Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai) (Click Here)
    2. User Manual (Company) eVTEMS (Click Here)
    3. User Manual Schedule A, MySST – Item 65 (Click Here)

    Reference

    1. Panduan Permohonan Sijil Pengecualian Cukai Jualan Di Bawah Butiran 65, Jadual A Perintah Cukai Jualan (Orang Yang Dikecualikan Daripada Pembayaran Cukai)

    2. User Manual (Company) eVTEMS

    3. User Manual Schedule A, MySST – Item 65

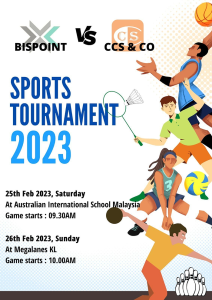
    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    11
  • Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022

    Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022

    We want to inform you that the Minister has exercised the powers conferred by paragraph 154(1)(b), read together with subsection 6(1A) of, and paragraph 2 of Part XVII of Schedule 1 to, the Income Tax Act 1967 [Act 53] and issued the Income Tax (Relocation of Provision of Services Business Incentive Scheme) Rules 2022 [P.U. (A) 398/2022].

    These rules will take effect from the year of assessment 2021. They will apply to qualifying companies that submit a written application for the Relocation of Provision of Services Business Incentive Scheme to the Minister through the Malaysian Investment Development Authority.

    The application must be received between November 7, 2020, and December 31, 2022.

    Interpretation

    In these Rules:-

    “Qualifying Company” means a new company or an existing company which fulfils the eligibility condition imposed by the Minister under the Act and these Rules

    “Malaysian Investment Development Authority” means the Malaysian Investment Development Authority established under the Malaysian Investment Development Authority (Incorporation) Act 1965 [Act 397];

    “Relocation of Provision of Services Business Incentive Scheme” means an incentive scheme for the qualifying company to undertake a qualifying activity and approved by the Minister;

    “New Company” means a company

    1. which is incorporated under the Companies Act 2016 [Act 777] and resident in Malaysia;
    2. which is established to carry on a qualifying activity under these Rules:
      1. which does not have an existing entity or related entity in Malaysia prior to the application referred to in rule 2 being made; or
      2. which has an existing entity or related entity in Malaysia which has not carried on a qualifying activity in Malaysia prior to the application referred to in rule 2 being made; and
    3. which:
      1. relocates its facility for the qualifying activity from outside Malaysia into Malaysia;
      2. relocates a new qualifying activity into Malaysia which is different from the existing qualifying activity outside Malaysia; or
      3. establish a new operation in Malaysia;

    “Existing Company” means a company:

    1. which is incorporated or registered under the Companies Act 2016 and resident in Malaysia; and
    2. which is already operating in Malaysia and carrying on a qualifying activity for a new business segment separated from the operation of the existing qualifying activity;

    Qualifying Activity

    A qualifying activity referred to under these Rules is any of the following service activities which adopt Industrial Revolution 4.0 and digitalisation technology undertaken by a qualifying company:

    1. provision of technology solutions or technology company which develops technology and provides technology solutions based on substantial scientific or engineering challenges;
    2. provision of infrastructure and technology for cloud computing;
    3. research and development or design and development activities;
    4. medical devices testing laboratory and clinical trials; or
    5. any service activity or manufacturing-related service activity as determined by the Minister

    Applicable Rate

    These income tax rates will apply to the chargeable income of a qualifying company that carries on business in respect of a qualifying activity under the Relocation of Provision of Services Business Incentive Scheme for the specified years of assessment [a period of up to ten consecutive years of assessment for the implementation of the Relocation of Provision of Services Business Incentive Scheme commencing from the year of assessment as determined by the Minister].

    Conditions for the Relocation of Provision of Services Business Incentive Scheme

    • A qualifying company applying for the incentive scheme must comply with conditions set by the Minister as specified in the approval letter and the Guidelines and Procedures for the Application of Special Tax Incentive for Selected Services Activities under the National Economy Recovery Plan (PENJANA).
    • The conditions for the scheme may be revised by the Malaysian Investment Development Authority and approved by the Minister.
    • The conditions shall include the following:
      • Employing at least 80% full-time Malaysian employees on or before the third year from the date of the first invoice in relation to the qualifying activity issued by the qualifying company until the end of the specified years of assessment.
      • Incurring an approved adequate amount of annual operating expenditure to carry on the qualifying activity or an approved adequate investment in fixed assets to carry on the qualifying activity.

    Non-application

    These Rules shall not apply to a qualifying company which, in the specified years of assessment:-

    1. has claimed reinvestment allowance under Schedule 7A to the Act or investment allowance for the service sector under Schedule 7B to the Act;
    2. has been granted any incentive under the Promotion of Investments Act 1986 [Act 327];
    3. has been granted an exemption under paragraph 127(3)(b) or subsection 127(3A) of the Act;
    4. has been approved by the Minister an incentive scheme under any rules made under section 154 of the Act; or
    5. has claimed deduction under any rules made under section 154 of the Act except:-
      1. the rules in relation to an allowance under Schedule 3 to the Act;
      2. the Income Tax (Deduction for Audit Expenditure) Rules 2006 [P.U. (A) 129/2006]; or
      3. the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) Rules 2020 [P.U. (A) 162/2020].

    Reference

    5 games to keep employees of CCS & Co Plt – Chartered Accountants and Bispoint Group of Accountants connected.

    We put a lot of emphasis on ensuring that our team members enjoy a balanced life outside work.

    Hence, our firm’s Sports and Social Committee is responsible for actively organising an exciting variety of events, such as the Annual Dinner, Annual Trips and Inter-accounting Firm Tournament.

    These events are planned so that our professionals can take some time off to relax and, more importantly, come together to strengthen their sense of community and teamwork.

    This year’s Inter-Accounting Firm Tournament will be held on February 25 and 26, 2023 (Saturday and Sunday). We welcome your support!

    5项活动让 CCS 特许会计师 和 Bispoint Group of Accountants 的员工保持联系。

    我们非常重视我们的团队成员享受工作以外的平衡生活。

    有鉴于此,我们公司的康乐委员会积极举办各种令人兴奋的活动,如年度晚宴、年度旅行和会计师事务所之间的比赛。

    这些活动的策划是为了让我们的专业人员可以抽出一些时间来放松,更重要的是,他们可以聚在一起加强社区意识和团队精神。

    今年的会计师事务所之间的比赛将于2023年2月25日和26日(星期六和星期日)举行。我们欢迎你前来支持!

    Our website's articles, templates, and material are solely for you to look over. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    13
  • Extension of Tax Incentive for Principal Hub 3.0

    Extension of Tax Incentive for Principal Hub 3.0

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    MOF's response: Off-budget.

    Background to the Principal Hub Incentive

    A locally incorporated company that uses Malaysia as a base for conducting its regional and global businesses and operations is considered to be a Principal Hub.

    This type of company uses Malaysia as its base to manage, control, and support its key functions, which can include the management of risks, decision-making, strategic business activities, trading, finance, management, and human resources.

    This new incentive, which went into effect on May 1, 2015, has replaced the International Procurement Centres (IPC), Regional Distribution Centres (RDC), and Operational Headquarters (OHQ) incentive schemes.

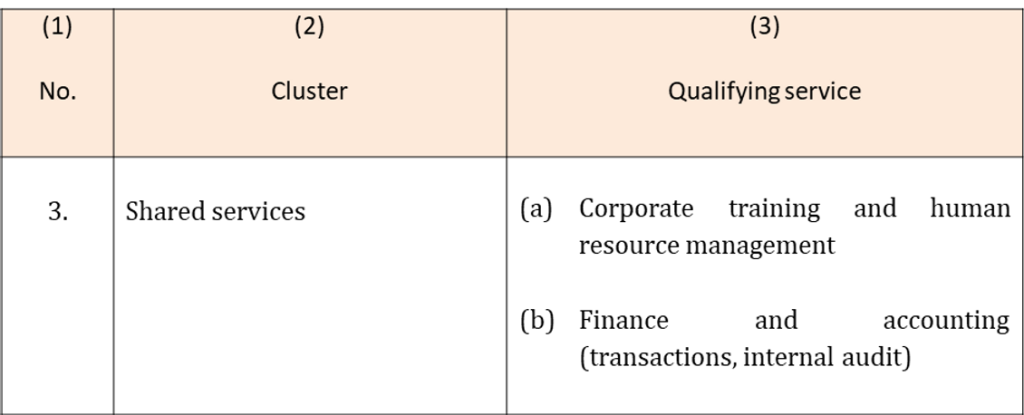
    To be eligible to apply for this incentive, a locally incorporated company must have a paid-up capital of more than RM2.5 million, in addition to providing at least three Qualified Services.

    The provision for the incentive can be found in the Income Tax Act of 1967 and approved through the National Committee on Investment.

    Principal Hub Incentive 3.0

    A review of the Principal Hub incentive scheme was one of the initiatives announced in the Budget 2021. This study is now mandated by legislation in the form of the Income Tax (The Principal Hub Incentive Scheme) Rules 2022.

    In the meantime, trading operations are now included under the umbrella of the Global Trading Center incentive.

    The Malaysian Investment Development Authority (MIDA) has issued guidelines that explain the tax incentive for the establishment of a Principal Hub. These guidelines can be found here:-

    174.1 Guidelines for Principal Hub Incentive 3.0

    .pdf

    Download PDF • 267KB

    The guidelines have regularly been updated to take into account any new legislative initiatives that have been taken.

    Current Position

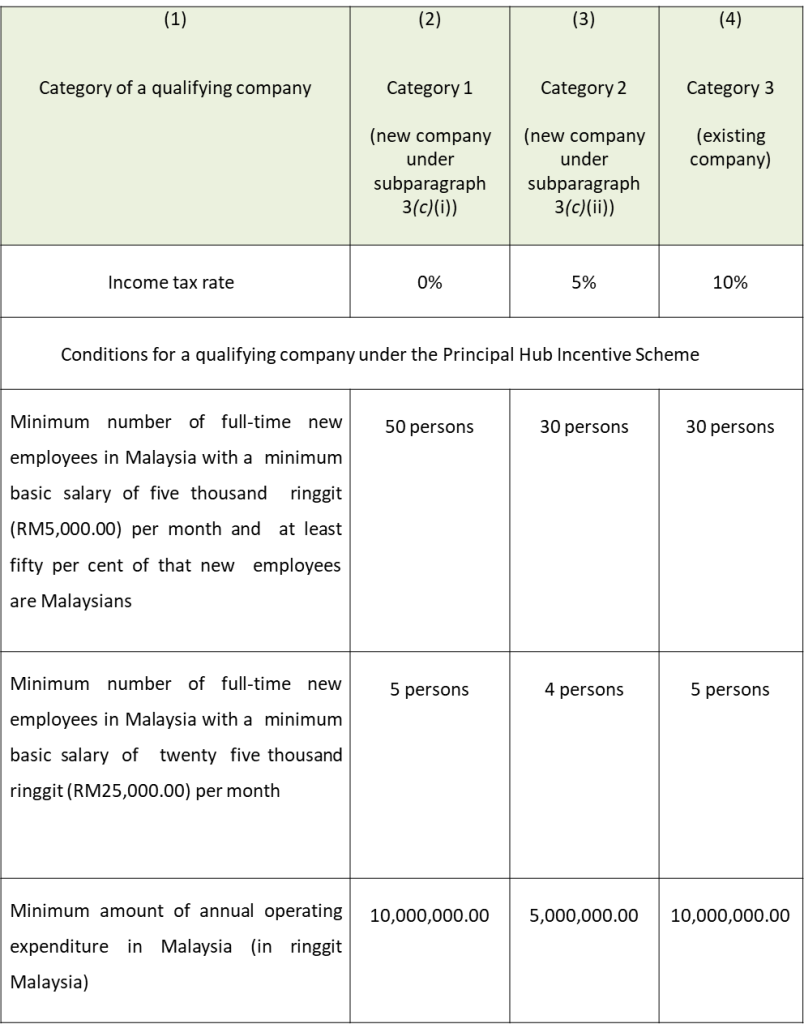
    New and existing companies using Malaysia as a global regional hub for high-value activities that manage, control and support main business functions such as risk management, decision-making, strategic business, finance and human resource management are eligible for principal hub tax incentives with 0%, 5% or 10% income tax rate.

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) until 31 December 2022.

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    In attracting more companies to establish their principal hub in Malaysia, the proposed tax incentive will be extended for 3 years.

    Effective Date

    For applications received by MIDA from 1 January 2023 until 31 December 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    17
  • Extension of Tax Incentive for Intellectual Property Development

    Extension of Tax Incentive for Intellectual Property Development

    Update: The Ismail Sabri Government Budget is no longer applicable.

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023.

    Response from MOF: MOF is currently reviewing off-budget items.

    The phrase “MOF is currently reviewing off-budget items” typically refers to the Ministry of Finance (MOF) conducting an evaluation or examination of expenses or financial matters that are not included in the official budget. Off-budget items are expenditures or revenue sources not directly accounted for in the regular budgeting process.

    Governments often create budgets to allocate funds for various programs, projects, and expenses. However, certain financial activities may fall outside the scope of the official budget. These off-budget items could include emergency spending, special funds, grants, subsidies, or other financial transactions not explicitly accounted for in the regular budgeting process.

    When the MOF reviews off-budget items, they are scrutinising these financial activities to assess their impact, legality, appropriateness, or potential risks. This review aims to ensure transparency, fiscal responsibility, and effective financial management within the government. It helps identify discrepancies, assess the necessity and effectiveness of off-budget items, and make informed decisions regarding their continuation or modification.

    Current Position

    The government proposed in Budget 2020 that qualifying intellectual property (IP)-generated income derived from the development of patents and copyright software be given a 100% income tax exemption for up to 10 years.

    In response to the proposal presented above, the Malaysian Investment Development Authority (MIDA) has published, with an effective date of January 1, 2020, the Guidelines on Incentives for Intellectual Property (IP) Development.

    For tax exemption computation, the income that qualifies for the exemption will be calculated based on the Modified Nexus Approach (MNA).

    Eligible applicants

    New/existing companies own the rights of the qualifying IPs and are receiving income from the qualifying IP activities related to the promoted activities/list prescribed under the Promotion of Investments Act 1986 (PIA) and the Income Tax Act 1967 (ITA).

    Qualifying IP asset types

    • Patent or utility innovation
    • Copyrighted software
    • Family of qualifying IPs

    Qualifying IP income types

    • Royalty
    • Licensing Fees

    Eligibility criteria

    • R&D activities must be conducted in Malaysia, where such activities lead to the development, improvement, modification or creation of the Qualifying Asset.
    • Adequate operating expenditure incurred annually to support the company in conducting its business operation in Malaysia.
    • The company must have at least 30% of science and technical staff have a degree or diploma with a minimum of five years of experience from related fields.

    Qualifying R&D expenditure

    • Eligible R&D expenditure for MNA calculation will align with the eligible expenditure types under s 34A of the ITA.
    • Includes expenditure under cost-sharing agreements, provided that the cost of payable R&D is clearly stated in the agreement.
    • Qualifying expenditure can be backdated up to three years from the date the IP is registered/filed.

    The incentive will apply to applications received by MIDA between 1 January 2020 and 31 December 2022. Three sets of the application are to be submitted to the following:

    • Chief Executive Officer
    • Malaysian Investment Development Authority (MIDA)
    • MIDA Sentral
    • No. 5, Jalan Stesen Sentral 5
    • Kuala Lumpur Sentral
    • 50470 Kuala Lumpur

    (Attention: Advanced Technology and Research & Development Division (ATRD) Division)

    Proposal [This tax incentive included in Budget 2023, tabled in Parliament on 7 October 2022, was not included in Budget 2023 (Re-tabled) on 24 February 2023]

    To further encourage R&D activities and IP registration in Malaysia, the proposed tax incentive will be extended for 3 years.

    Effective Date

    For applications received by MIDA from 1 January 2023 until 31 December 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    16
  • Green Investment Tax Allowance (GITA) & Green Income Tax Exemption (GITE)

    Green Investment Tax Allowance (GITA) & Green Income Tax Exemption (GITE)

    Updated on 15 July 2023 - Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Malaysia’s national budget for 2023 was re-tabled again in February 2023; for more info, please visit – https://www.ccs-co.com/post/budget-2023-malaysia-madani.

    The Ismail Sabri Government Budget is no longer applicable. Therefore, these tax incentives included in Budget 2023, tabled in Parliament on 7 October 2022, were not included in Budget 2023 (Re-tabled) on 24 February 2023.

    The good news is that based on the response from MOF (Ministry of Finance), these incentives will be reviewed during Budget 2024.

    Current Position

    There are currently incentives for green technology, including:

    • the Green Investment Tax Allowance for qualifying green activities, and
    • the Green Investment Tax Exemption for qualifying green services and solar leasing activities.

    In Budget 2020, green technology tax incentives have been extended until 31 December 2023.

    Meanwhile, in Budget 2022, Rainwater Harvesting Systems (RHS) are included within Qualifying Green Services and Qualifying Green Assets.

    1. Green Investment Tax Allowance (GITA)

    • Investment Tax Allowance (ITA) of 100% on capital expenditure for qualifying green activity for 3 years.
    • This allowance can be set off against 70% of statutory income.

    2. Green Income Tax Exemption (GITE)

    • income tax exemption of 70% on statutory income for qualifying green services activities for 3 years of assessment; and
    • income tax exemption of 70% on statutory income for up to 10 years for solar leasing activities.

    The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) from 1 January 2020 until 31 December 2023.

    The proposal under Ismail Sabri Government Budget [But these tax incentives included in Budget 2023, tabled in Parliament on 7 October 2022, were not included in Budget 2023 (Re-tabled) on 24 February 2023.]

    As a continuous support for green technology development initiatives in line with the Green Technology Master Plan 2017-2030, it is proposed tax incentives for qualifying green activities under GITA and GITE be reviewed based on tiering approach as follows:

    1. ITA of 60% for solar activity; and ITA of 100% for activity other than solar, including Battery Energy Storage System (BESS);
    2. tax incentive period be extended from 3 years to 5 years for selected projects; and
    3. application period for tax incentives is extended for two years.

    The details of tiering approach for GITA and GITE, as in SCHEDULE 1, as below:-

    Effective Date

    These tax incentives included in Budget 2023, tabled in Parliament on 7 October 2022, were not included in Budget 2023 (Re-tabled) on 24 February 2023. Therefore, it is no longer relevant.

    For applications received by MIDA from 1 January 2024 until 31 December 2025.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM[21/6/2023]

    CTIM would like to know when the government will issue the Income Tax Exemption Order (GITE) so that the taxpayers can claim the tax incentive.

    LHDNM’s Feedback:

    The draft exemption order is currently in the process of being gazetted.

    Update on the status: Green Investment Tax Allowance (“GITA”)

    On the extension of 100% Investment Tax Allowance to the YA 2023 on qualifying capital expenditure incurred for green technology activities.

    LHDNM’s Feedback:

    Various technical and legal parties are reviewing the draft exemption order, namely MOF, AGC, LHDNM, MGTC, and MIDA.

    A discussion was held on 18 April 2023 between MOF, AGC, and LHDNM to address issues and questions raised by AGC regarding the draft GITA Asset.

    The drafts for GITA Asset, GITA Project, and GITA Green Building are currently in the process of being gazetted with AGC.

    Update on the status: Green Income Tax Exemption (“GITE”)

    • Extension of income tax exemption of 70% of statutory income for qualifying green technology services to the YA 2023; and
    • Income tax exemption of 70% of statutory income up to 10 years of assessment for solar leasing companies certified by the Sustainable Energy Development Authority (“SEDA”).

    LHDNM’s Feedback:

    The draft exemption order is currently in the process of being gazetted with AGC.

    Update on the status: Extension of the list of qualifying assets from nine to forty in the MyHIJAU directory for green investment tax allowance (“GITA”).

    LHDNM’s Feedback:

    A discussion was held on 18 April 2023 between MOF, AGC, and LHDNM to address issues and questions raised by AGC regarding the draft GITA Asset.

    The draft exemption order is currently in the process of being gazetted with AGC.

    MOF’s Feedback:

    Various technical and legal parties are currently reviewing the draft exemption order, namely MOF, AGC, LHDNM, and MGTC.

    Update on the status: Investment tax allowance for the purchase of green technology equipment and tax exemption on the use of green technology systems be granted

    LHDNM’s Feedback:

    A discussion was held on 18 April 2023 between MOF, AGC, and LHDNM to address issues and questions raised by AGC regarding the draft GITA Asset.

    The draft exemption order is currently in the process of being gazetted with AGC.

    MOF’s Feedback:

    Various technical and legal parties are reviewing the draft exemption order, namely MOF, AGC, LHDNM, and MGTC.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    23
  • Income Tax (The Principal Hub Incentive Scheme) Rules 2022

    Income Tax (The Principal Hub Incentive Scheme) Rules 2022

    Principal hub incentive 3.0

    It was announced in the Budget 2021 that the deadline for submitting applications for the principal hub incentive will be deferred by an additional two years, to the 31st of December in 2022.

    The submission deadline had previously been open until the 31st of December 2020.

    In addition, in connection with the renewal of the incentive following the initial five-year period, the criteria that must be met by new companies will be loosened up.

    The Malaysian Investment Development Authority (“MIDA”) has now published the “Guidelines for Principal Hub Incentive 3.0” in response to the announcement that was made earlier.

    The guidelines are available from MIDA’s website [https://www.mida.gov.my/
    • (Forms and Guidelines | Services Sector | Regional Operations)].
    On 24 May 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with subsection 6(1A) and paragraph 2 of Part XVII of Schedule 1 to the Income Tax Act 1967 [Act 53], gazetted the Income Tax (The Principal Hub Incentive Scheme) Rules 2022 
    [P.U (A) 164].

    What it is All About

    A qualifying company will be subject to these Rules if it submits a written application for the Principal Hub Incentive Scheme to the Minister through the Malaysian Investment Development Authority.

    The application must be received on or after January 1, 2021, and no later than December 31, 2022.

    What is a Principal Hub?

    A locally incorporated company that uses Malaysia as a base for conducting its regional and global businesses and operations is considered to be a principal hub. This type of company uses Malaysia as its base in order to manage, control, and support its key functions, which can include the management of risks, decision-making, strategic business activities, trading, finance, management, and human resources.

    What is the “Principal Hub Incentive Scheme”?

    It means an Incentive Scheme for the Qualifying Company which carries on Qualifying Activity and is approved by the Minister.

    The principal hub incentive was first introduced in 2015, with the goal of making Malaysian cities more attractive to multinational companies (MNCs) looking to establish a regional hub in Southeast Asia.

    This was particularly important due to the fact that the country had established a manufacturing base for MNCs from the 1980s to the 2000s.

    What is the “Malaysian Investment Development Authority”?

    It means the Malaysian Investment Development Authority which was established under the Malaysian Investment Development Authority(Incorporation) Act 1965 [Act 397].

    What are the Qualifying Activities for principal hubs in Malaysia?

    It is an activity that fulfills the eligibility condition prescribed by the Minister as provided under rule 4.

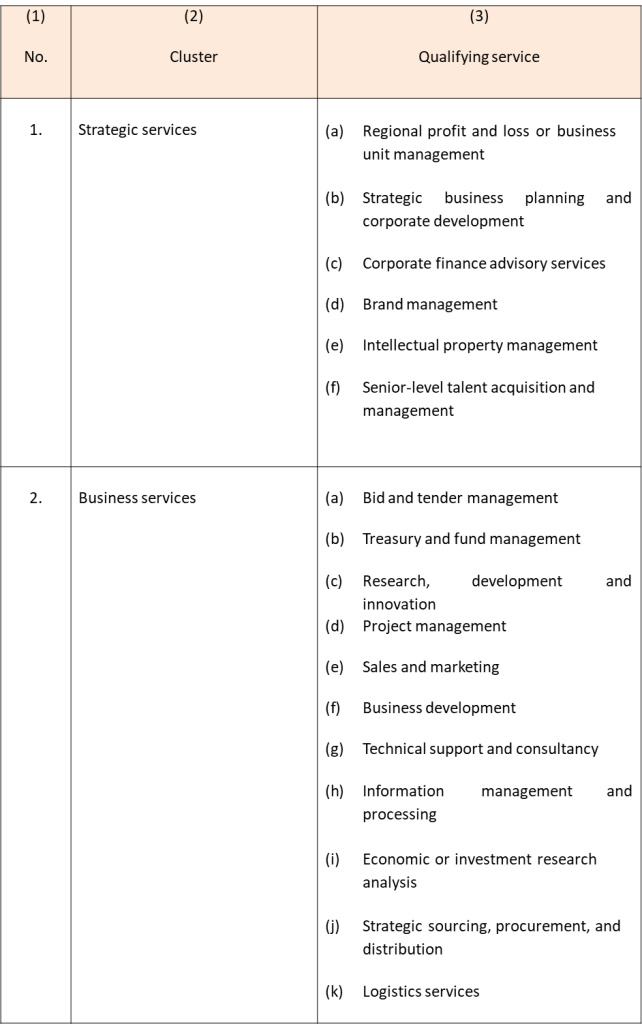
    The qualifying activities are as follows:

    What is the “Qualifying Company”?

    It is a new company or an existing company that fulfills the eligibility condition imposed by the Minister under the Income Tax Act 1967 (‘ITA’) and the 2022 Rules.

    Rule 3 of the 2022 Rules provides that a new company must:

    1. be incorporated under the Companies Act 2016 (‘CA 2016’) and resident in Malaysia;
    2. have a paid-up capital of more than RM2,500,000; and
    3. be established to carry on a qualifying activity, which:
    • does not have an existing entity or related entity in Malaysia before the application referred to in rule 2 was made [Category 1]; or
    • has an existing entity or related entity in Malaysia which has not carried on a qualifying activity in Malaysia before the qualifying company’s application for approval as a principal hub under the Scheme [Category 2].

    Rule 3 of the 2022 Rules provides that an existing company must:

    1. be incorporated under the CA 2016 and resident in Malaysia;
    2. already be operating in Malaysia and carrying on a manufacturing or services activity other than the qualifying activity before the qualifying company’s application for approval as a principal hub under the Scheme; and
    3. have a paid-up capital of more than RM2,500,000.

    The Tax Incentive

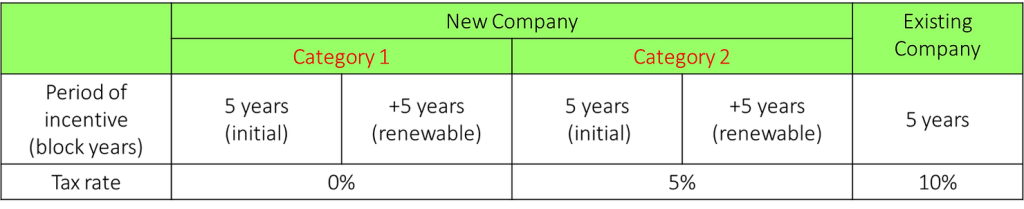
    The incentive, if granted, will be for a period of 5 consecutive years of assessment.

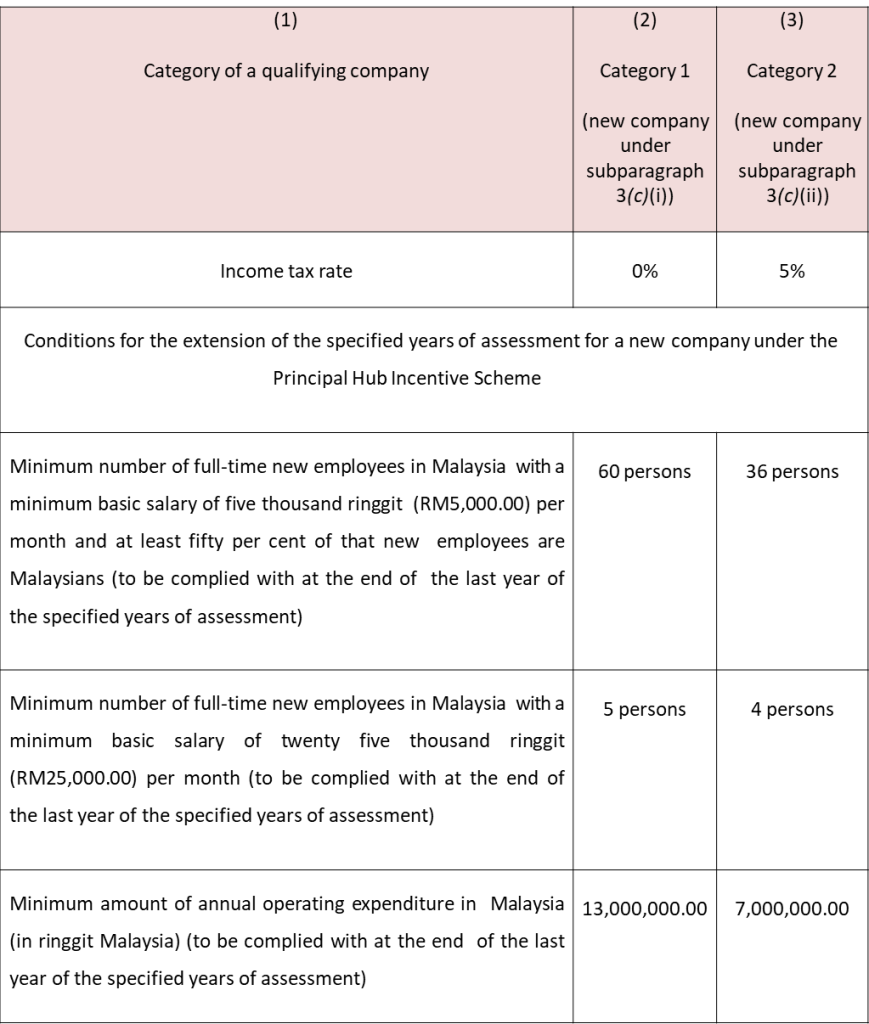
    The rate of income tax that shall be charged under the 2022 Rules is as follows::

    Extension of Specified Years of Assessment for a New Company

    The Minister may extend the specified years of assessment for a new company for another period of five years of assessment subject to the new company fulfilling all conditions imposed by the Minister as specified in the approval letter and any other conditions as specified in Schedule 3 as follows:-

    In Summary:

    Exclusion and Non-Application

    • Income derived from the intellectual property (Note 1) from a qualifying activity shall not be included in ascertaining the statutory income of a qualifying company as the income shall be subject to tax under the ITA.
    • A qualifying company that has made a claim for relief, exemption, deduction, or incentive (Note 2)under certain provisions of the ITA or the Promotion of Investments Act of 1986 is excluded from the application of the 2022 Rules.

    Note 1

    1. A qualifying company owns an intellectual property right if the qualifying company is the owner or the licensee of the right;
    2. royalties or other income is derived from an intellectual property right if it is receivable as consideration for the commercial exploitation of that right; and
    3. “intellectual property right” means a right arising from any patent, utility innovation and discovery, copyright, trademark, and service mark, industrial design, layout-design of the integrated circuit, secret processes or formulae and know-how, geographical indication, and the grant of protection of a plant variety, and other like rights, whether or not registered or registrable.

    Note 2

    1. has made a claim for reinvestment allowance under Schedule 7A to the Act or investment allowance the for service sector under Schedule 7B to the Act;
    2. has been granted an incentive under the Promotion of Investments Act 1986 [Act 327];
    3. has been granted an exemption under paragraph 127(3)(b) or subsection 127(3A) of the Act; or
    4. has been approved by the Minister an incentive scheme under any rules made under section 154of the Act; or
    5. has made a claim for deduction under any rules made under section 154 of the Act except—
    • the rules in relation to an allowance under Schedule 3 to the Act;
    • the Income Tax (Deduction for Audit Expenditure) Rules 2006 [P.U.(A) 129/2006];or
    • the Income Tax (Deduction for Expenses in relation to Secretarial Fee and Tax Filing Fee) Rules 2020 [P.U. (A) 162/2020].
    20
  • Income Tax (Deduction for Invt. in a Project of Commercialisation of R&D Findings) Rules 2022

    Income Tax (Deduction for Invt. in a Project of Commercialisation of R&D Findings) Rules 2022

    1. On 6 January 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Investment in a Project of Commercialisation of Research and Development Findings) Rules 2022 [P.U. (A) 3]

    2. These Rules are deemed to have come into operation on 7 November 2020.

    3. Join our Telegram 👉 https://t.me/YourAuditor/2535

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2022 年 1 月 6 日,部长行使 1967年所得税法令 [法案53] 第154(1)(b) 段与第33(1)(d)段一并阅读所赋予的权力,在宪报上颁布了 2022年所得税(研究与开发成果商业化项目投资扣除) 细则 [P.U. (A) 3]。

    2. 这项细则视为于2020年11月7日开始实施。

    3. 加入我们的 Telegram 群 👉 https://t.me/YourAuditor/2535

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    11