Tag: Import Duty Exemption

  • Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position
    Smoking cessation services at Government health clinics and hospitals have been implemented since 2000.

    Starting in 2015, this programme expanded to private health facilities, including hospitals, clinics and pharmacies, through public and private collaboration under the mQuit Programme.

    In this programme, Nicotine Replacement Therapy (NRT) is used as one of the medical treatment options for smoking cessation.

    The NRT aims to supply smokers with enough nicotine to gradually reduce the symptoms of addiction without the harmful substances resulting from burning cigarettes or heating the liquid of electronic cigarettes.

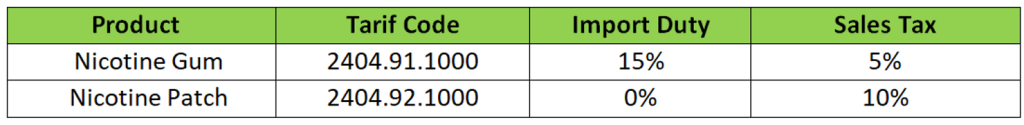
    Two NRT products in the market are subject to import duty and sales tax as follows:
    Proposal
    To support the mQuit Programme and encourage the use of NRT as an option for smoking cessation, it is proposed that import duty and sales tax exemption be given to nicotine gum and nicotine patch for a period of 3 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 April 2023 until 31 March 2026.
    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    18
  • Review of Tax Incentives for Bionexus Status Company

    Review of Tax Incentives for Bionexus Status Company

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    “Bio Nexus Status Company” means a company incorporated under the Companies Act 2016 [Act 777] engaged in the life sciences business.

    Tax incentives for BioNexus status companies are given as follows:

    1. a company undertaking biotechnology activity and approved with BioNexus status:
      1. Income Tax Exemption of 70% on statutory income commencing from the first statutory income for a period of 10 or 5 years, subject to new or existing business (expansion project);
      2. concessionary tax rate of 20% on income from qualifying activities for 10 years upon the expiry of the tax exemption period;
      3. Double Tax Deduction on research & development expenditure;
      4. Industrial Building Allowance on building for biotechnology research activities; and
      5. Import Duty Exemption on raw materials / components and machinery / equipment.
    2. a company that undertakes investment in a BioNexus status subsidiary company engaging in a new project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made.

    The tax incentive is for applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2021 until 31 December 2022.

    Proposal

    To encourage more industry players, it is proposed tax incentives be reviewed as follows:

    • income tax exemption on statutory income be increased from 70% to 100%; and
    • the application period for tax incentives is extended for 2 years.

    Effective Date

    For applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2023 until 31 December 2024.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    BioNexus status companies also get an income tax exemption which is equivalent to the allowance based on 100% of qualifying capital expenditure (“QCE”), i.e. Investment Tax Allowance (“ITA”).

    CTIM sought to confirm that the proposed two years application period extension applies to all tax incentives for BioNexus status companies, including the ITA and is not just restricted to the items listed in Appendix 19.

    MOF’s Feedback:

    Extending the 2-year application period applies to all tax incentives for BioNexus status companies, including the Investment Tax Allowance.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    17
  • Extension of Import Duty and Excise Duty Exemption on Imported CBU Electric Vehicles

    Extension of Import Duty and Excise Duty Exemption on Imported CBU Electric Vehicles

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Imported Completely Built-Up (CBU) Electric Vehicles (EV) consisting of passenger vehicles (including SUV and MPV), motorcycles and commercial vehicles are subject to duties and taxes as follows:

    In Budget 2022, full import and excise duty exemptions are given on imported CBU EVs from 1 January 2022 until 31 December 2023.

    Proposal

    To encourage domestic demand for EVs in line with the Low Carbon Mobility Blueprint, EV Roadmap and National Automotive Policy 2020, as well as considering the global shortage of automotive chips, it is proposed full import duty and excise duty exemption on imported CBU be extended for a period of 1 year.

    Effective Date

    From 1 January 2024 until 31 December 2024.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    15