1. Companies, co-operative societies, limited liability partnerships, and trust bodies are all required to file tax returns, even if they are dormant, in the same way, they were in previous years.
2. They do not have to report the estimated tax payable (Form CP 204) if they have not started operations.
1. Companies are required to pay tax in monthly instalments depending on estimated tax liabilities. Each month’s instalments must be paid on or by the 15th of the month.
2. A 10% penalty may be imposed for late or inadequate payments. If the actual tax payable exceeds the estimate by more than 30%, a 10% penalty will be imposed.
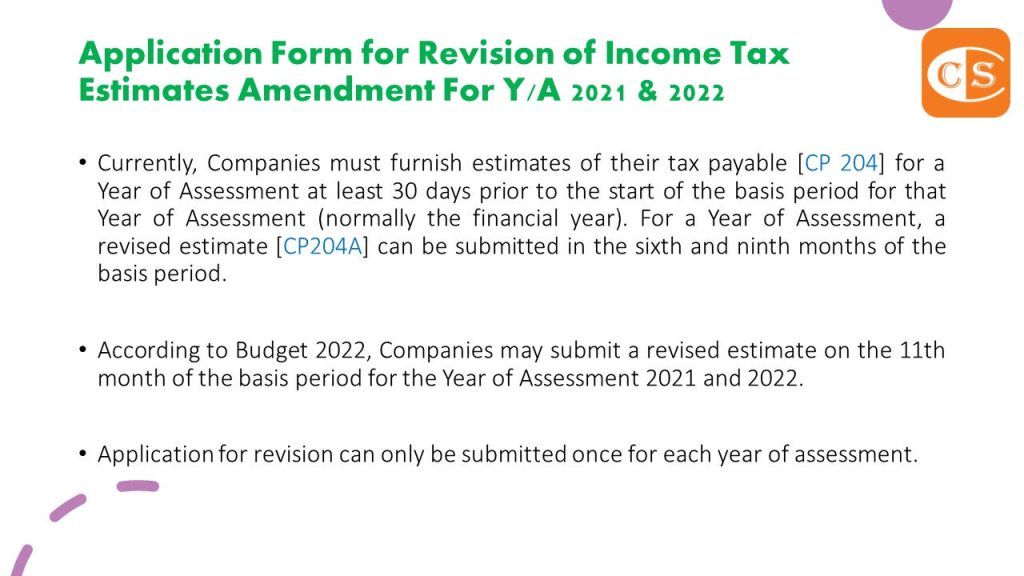
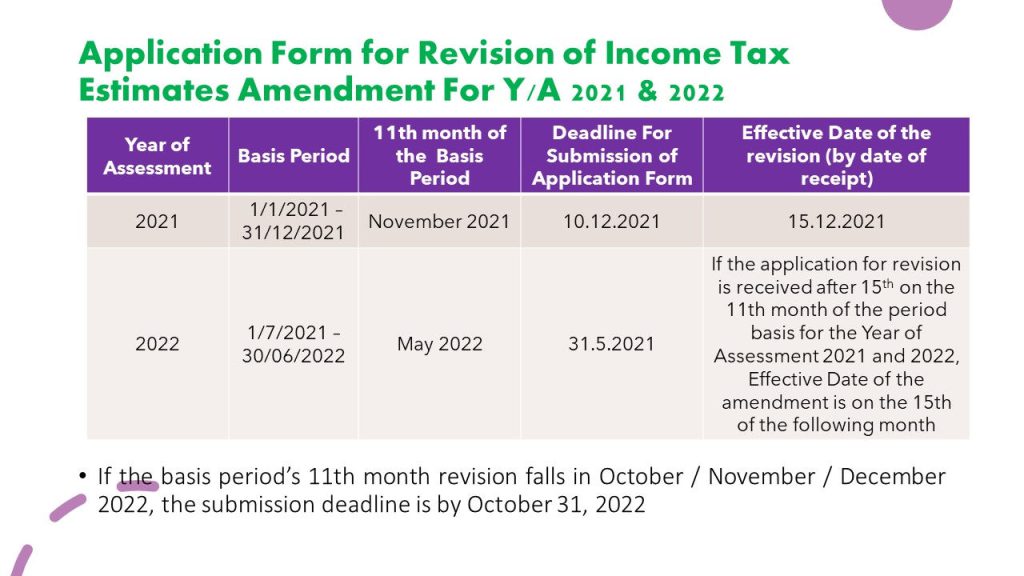
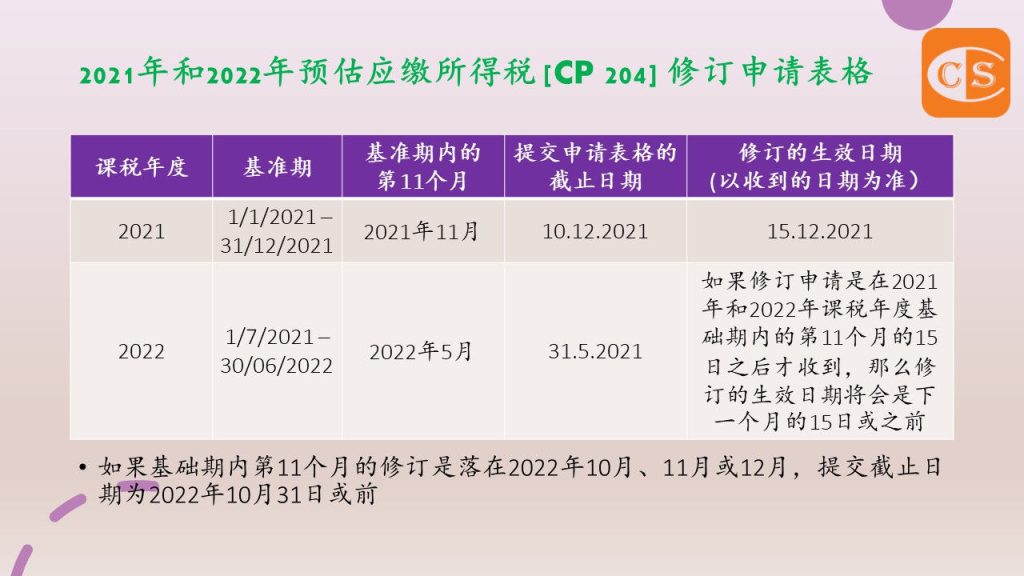
3. According to Budget 2022, Companies may submit a revised estimate on the 11th month of the basis period for the Year of Assessment 2021 and 2022.
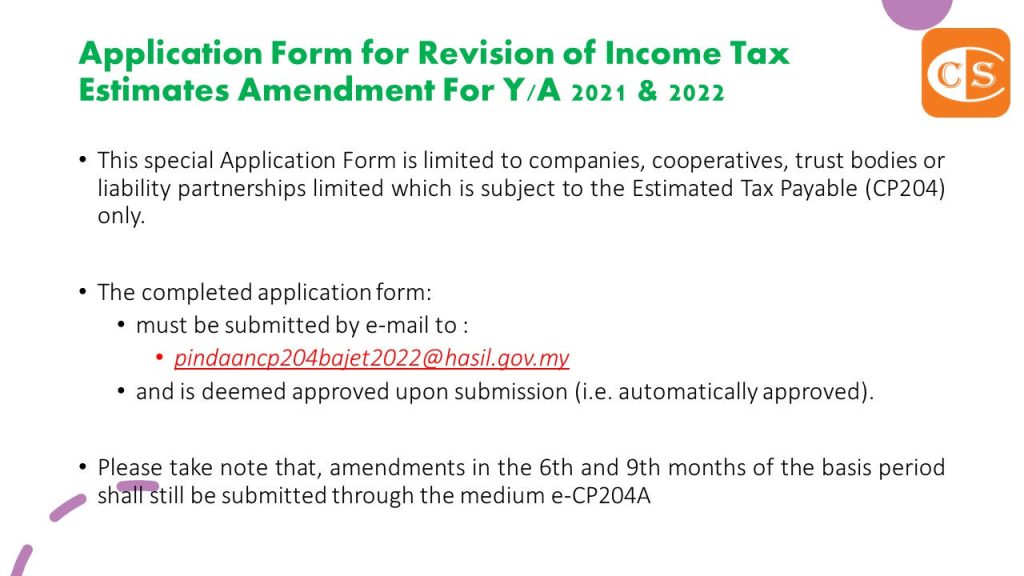
4. On its website, the Malaysian Inland Revenue Board has uploaded the Application Form (in Bahasa Malaysia version only)
5. The LHDNM has also uploaded the Frequently Asked Questions (FAQs) dated November 25, 2021 (in Bahasa Malaysia only). 6. To Download Application Form & FAQs – https://www.ccs-co.com/publications
1) The Inland Revenue Board (IRB) has released Operational Guidelines No. 1/2021 (GPO 1-2021) on its website, dated December 22, 2020.
2) The guidelines are captioned “Pengemukaan Anggaran Cukai Yang Kena Dibayar Di Bawah Seksyen 107C Akta Cukai Pendapatan 1967 (ACP)” and are prepared in Bahasa Malaysia.
3) The new 45 pages Guidelines supersede the previous Operational Guidelines No. 1-2017 [GPO 1-2017], which were issued on February 23, 2017.