Tag: Covid-19

  • Revised Special Guidelines: Income Tax Deduction for Community/Charity Projects to curb Covid-19

    Revised Special Guidelines: Income Tax Deduction for Community/Charity Projects to curb Covid-19

    The announcement that contributions (in cash or in-kind) to overcome the COVID-19 outbreak is allowed for deduction under s 34(6)(h) of the Income Tax Act was made by the Government on March 23, 2020.

    A guideline was then issued by the Ministry of Finance (MOF) to explain the conditions and procedures in such claims.

    Further, donations made to vaccination centres (PPVs) would be eligible for tax deductions under the provisions of the National People’s Well-Being and Economic Recovery Package (PEMULIH).

    As a result of this announcement, the guideline issued by the MOF was updated on 2 August 2021 to include contributions to PPVs under s 34(6)(h).

    The Ministry of Finance (MOF) has revised the guidelines published on its website on April 1, 2022, regarding Income Tax Deduction for Community/Charity Projects to curb Covid-19 under Section 34(6)(h) of the Income Tax Act.

    The Guidelines are in Bahasa Malaysia and are named “Garis Panduan Khas Permohonan Potongan Cukai Bagi Projek Komunity/Amal untuk Menangani Wabak Covid-19” (Guidelines).

    The Guidelines can be found here:-

    The Guidelines apply to contributions made from April 1, 2022, to December 31, 2022.

    Key Updates

    1. Qualifying contributions

    Under the Revised Special Guidelines, Qualifying contributions are now limited to:-

    • Equipment – ventilators, beds, air-conditioners and air purifier/filtration
    • Consumables – masks, hand sanitisers, gloves, test kits and personal protective equipment

    Under the revised Special Guidelines, the following are no longer considered qualifying contributions and have been taken off the list of qualifying contributions:

    • Cash
    • Raw food ingredients and ready-to-eat foods
    • Sanitisation services, provision of portable toilets, costs of delivery of supplies
    • Sponsorships such as the provision of permanent or temporary site infrastructure (e.g. marquee tents)
    • Provision of COVID-1 9 vaccination facilities such as halls, equipment and supplies in respect of PPVs

    2. Qualifying Recipients

    Under the Revised Special Guidelines, the donees are restricted to the following:

    • Government departments//agencies
    • Public hospitals
    • Public schools

    Under the revised Special Guidelines, the following recipients who were once eligible to get donations are no longer on the list:

    • Registered non-governmental agencies which are not profit oriented or politically affiliated
    • Private hospitals
    • Universities and educational institutions
    • PPVs throughout the country which are managed by the COVID-19 Immunisation Task Force (CITF) or private sectors with the approval of CITF

    Effective Date

    These guidelines apply to donations made to community or charity projects to combat the spread of the COVID-19 outbreak during the period beginning in February 2020 and ending on December 31, 2022, or until the outbreak of COVID-19 is declared over by the World Health Organisation (WHO), whichever comes first

    Tax deduction claims can be claimed from the assessment year 2020 and are applicable for the assessment year the contribution is made.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    17
  • Double Tax Deduction for the Cost of Detection Test of Covid-2019

    Double Tax Deduction for the Cost of Detection Test of Covid-2019

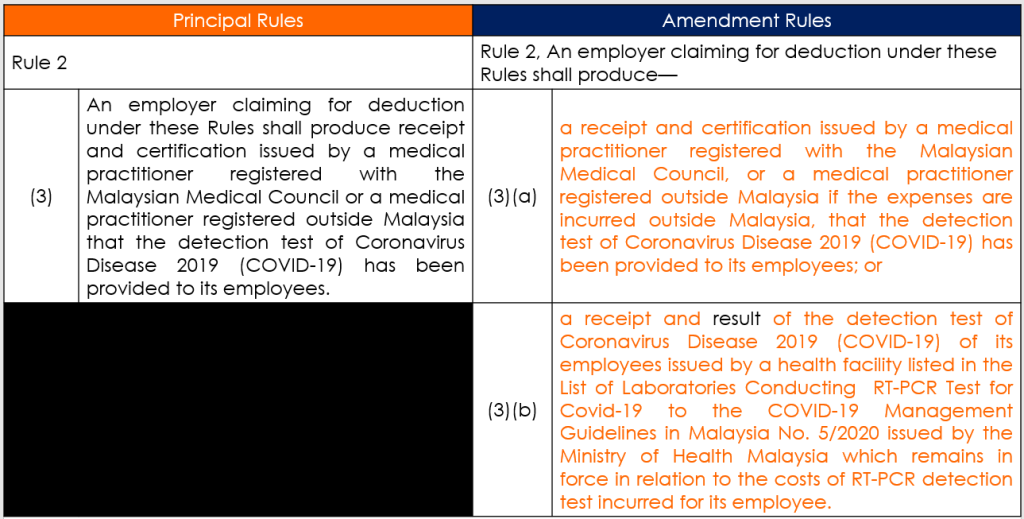
    In the exercise of the powers conferred by paragraph 154(1)(b) read together with paragraph 33(1)(d) of the Income Tax Act 1967 [Act 53], the Minister, on September 9, 2022, gazetted the Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) (Amendment) Rules 2022 (P.U. (A) 291/2022) (“Amendment Rules“) to amend the Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) Rules 2021 [P.U. (A) 404/2021] (“Principal Rules”).

    Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) Rules 2021

    Under these Principal Rules, a Double Tax Deduction of expenses incurred by an employer resident in Malaysia for the cost of detection test of COVID-19 for its employees from 1 January 2021 until 31 December 2021.

    An employer who wishes to claim a deduction under the Rules must produce a receipt and certification issued by a medical practitioner registered with the Malaysian Medical Council or a medical practitioner registered outside Malaysia stating that the Covid-19 Detection Test has been provided to the employees of the employer.

    Therefore, a medical report without a certificate is not eligible to claim this deduction.

    Likewise, receipts without a certificate are also not eligible to claim this deduction.

    The Inland Revenue Board of Malaysia has issued responses dated 18 May 2022 to CTIM members’ issues dated January 31, 2022, reiterating that Sub-rule 2(3) in P.U(A) 404/2021 must be complied with.

    Income Tax (Deduction for Expenses in relation to the Cost of Detection Test of Coronavirus Disease 2019 (COVID-19) for Employees) (Amendment) Rules 2022

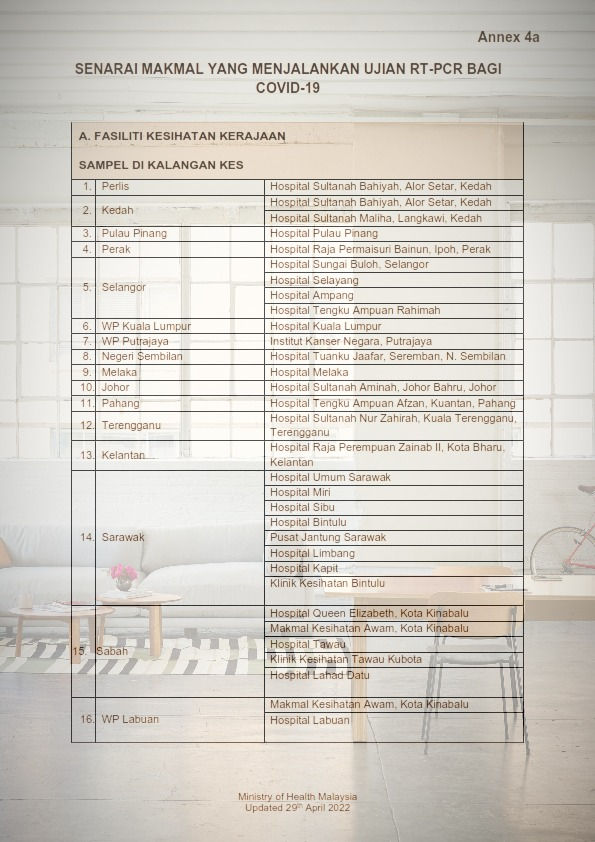
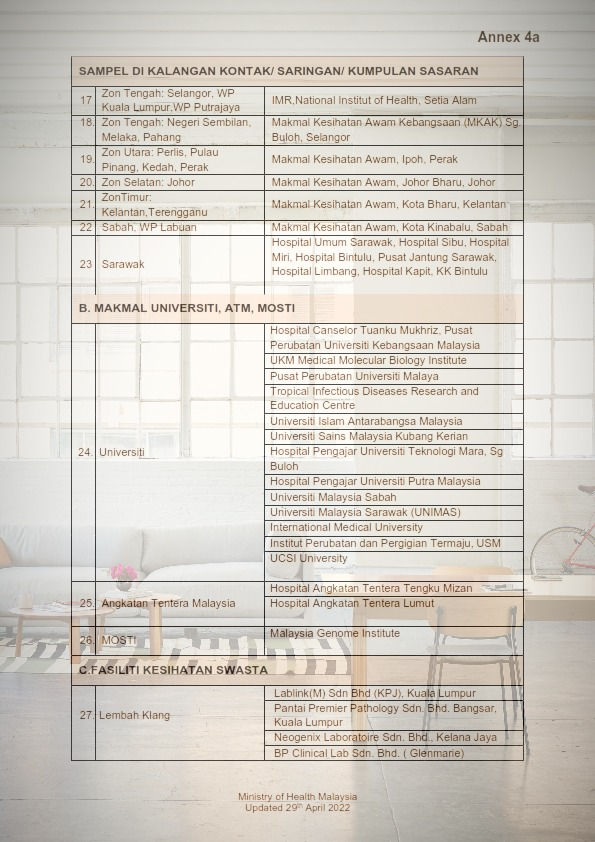
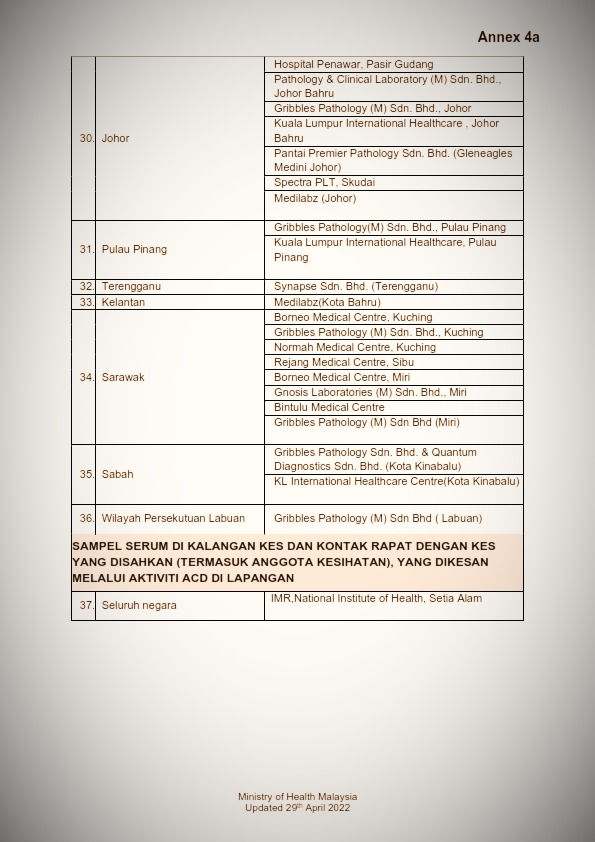
    The Amendment Rules amend the Principal Rules to state that, as an alternative, an employer wishing to claim such a deduction may present a receipt and the results of the Covid-19 Detection Test performed on its employees and issued by a health facility listed in the List of Laboratories Conducting RT-PCR Test for Covid-19 to the COVID-19 Management Guidelines in Malaysia No. 5/20201 issued by the Ministry of Health Malaysia.

    List of Laboratories Conducting RT-PCR Test for Covid-19 to the COVID-19 Management Guidelines in Malaysia No. 5/20201

    To Download:

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    26
  • Tax Concessions Due to COVID-19 Travel  Restrictions expired on 31 December 2021

    Tax Concessions Due to COVID-19 Travel Restrictions expired on 31 December 2021

    1. On December 24, 2021, the Inland Revenue Board (IRB) updated the FAQ on International Tax Issues Due to COVID-19 Travel Restrictions (FAQ) and announced:

    👉 the Tax concessions Due to COVID-19 Travel Restrictions expired on 31 December 2021

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021年12月24日,税税局 (IRB) 更新了关于新冠肺炎的旅行限制导致的国际税收事项常见问题 [FAQ],并宣布:

    👉 关于新冠肺炎期间的行动限制所给予的税务宽免,于2021年12月31日结束

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10