Tag: Budget 2023

  • Review of Tax Deduction on Cost of Listing in Bursa Malaysia

    Review of Tax Deduction on Cost of Listing in Bursa Malaysia

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    A deduction on expenses made by a technology-based company in connection with listing in the ACE (i.e. Access, Certainty, and Efficiency) or LEAP (i.e. Leading Entrepreneur Accelerator Platform) market will be permitted beginning in the year 2020 and continuing through the year 2022.

    The Income Tax (Deduction for Expenses in Relation to Listing on Access, Certainty, Efficiency (Ace) Market or Leading Entrepreneur Accelerator Platform (Leap) Market of Bursa Malaysia Securities Berhad) Rules 2020 allow for the deduction to be taken.

    The technology-based company must be involved in the design, development, manufacture, production, or application of the fields and activities indicated in the Schedule under the Regulations in order to be eligible for the deduction.

    Such activities must be certified by Bursa Malaysia Securities Berhad as the principal business activity of the technology-based company. The technology-based company must apply for listing in ACE or LEAP in order to claim for the deduction of the listing fees.

    The technology-based company is required to apply for listing in either ACE or LEAP to be eligible for a deduction of the following listing fees:-

    • payment of fees to Bursa Malaysia Securities Berhad and Securities Commission Malaysia
    • professional fees such as advisory fees, fees to solicitors, company secretaries, tax advisers etc, and
    • underwriting, placement and brokerage fees.

    The deduction on the above fees is given up to RM1.5m.

    Proposal

    To further encourage more technology-based companies and Micro, Small and Medium Enterprises to expand their business by increasing capital funds through listing on BURSA Malaysia, it is proposed the treatment be reviewed as follows:

    1. the existing tax deduction of up to RM1.5 million on the cost of listing on the ACE and LEAP Markets is extended for a period of 3 years; and
    2. this tax deduction is also expanded to cover the cost of listing technology-based companies on BURSA Main Market.

    Effective Date

    From the year of assessment 2023 until the year of assessment 2025

    Schedule – fields and activities

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    19
  • Tax Deduction on Issuance Cost of Sustainable and Responsible Investment Linked Sukuk

    Tax Deduction on Issuance Cost of Sustainable and Responsible Investment Linked Sukuk

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    The Securities Commission Malaysia has introduced the framework on Sustainable and Responsible Investment Sukuk (SRI), which enables fundraising by companies through financing towards improving sustainability practices and supporting the transition to low-carbon activities.

    The framework on SRI-linked Sukuk aims to address a wider range of financing needs for companies at different stages of their sustainability journey, providing companies more opportunities for transition to net zero carbon targets and further meet the Government’s desire to achieve net zero carbon emissions targets by 2050

    Proposal

    It is proposed that a tax deduction be given for a period of 5 years on the cost of issuing SRI-linked Sukuk that is approved/permitted/deposited with the Securities Commission Malaysia to provide innovative Shariah-Compliant Financing and place Malaysia as a regional hub of SRI-Linked Sukuk Issuance.

    Effective Date

    From the year of assessment 2023 until the year of assessment 2027.

    Comments

    This proposal aims to incentivize companies to adopt sustainable and responsible investment practices and contribute towards the achievement of the government’s net-zero carbon emissions targets by 2050.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    19
  • Stamp Duty Treatment for Transfer of Property by Way of Love and Affection

    Stamp Duty Treatment for Transfer of Property by Way of Love and Affection

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Effective from 1 January 2019, the stamp duty rate on the instrument of transfer of property is as follows:

    Transfer between Husband and Wife

    The full imposition of stamp duty is exempted on any instrument of transfer of property executed between a husband and wife.

    Transfer between Parents and Children

    On the instrument of property transfer completed between parents and children who hold citizenship in Malaysia, the payment of stamp duty is waived in the amount of 50%.

    Proposal

    To reduce the cost of stamp duty for the transfer of property by way of love and affection between parents and children, grandparents and grandchildren, it is proposed that duty stamp on the instruments of property transfer be fully exempted, limited to the first RM1 million of the property’s value.

    The remaining balance of the property’s value is subject to the ad valorem duty rate and is given a 50% remission on the stamp duty imposed.

    This stamp duty treatment applies to the recipients who are Malaysian citizens.

    Effective Date

    For the instrument of transfer of property executed from 1 April 2023.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    CTIM welcomes that this is extended to cover grandparents to grandchildren, which looks at three generations of succession planning.

    However, recognising the various family situations, there could be very legitimate passing on of property between siblings, and hence it would be inclusive for stamp duty exemption also to cover transfers between siblings so that, among others, property owners without children would not suffer tax for transfer of property by way of love and affection to their natural next choice in their immediate family circle.

    Feedback from MOF:

    The views of CTIM (Chartered Tax Institute of Malaysia) are noted, but they will need more study.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    21
  • Stamp Duty Treatment for Educational Loan/Scholarship Agreement

    Stamp Duty Treatment for Educational Loan/Scholarship Agreement

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    According to Item 22(4) of the First Schedule of the Stamp Act 1949, an educational loan or scholarship agreement to pursue tertiary education level (diploma and above) at higher learning institutions is subject to stamp duty at a fixed duty of RM10; however, stamp duty is charged at an ad valorem rate for other levels of education.

    Proposal

    It is proposed that the imposition of a fixed duty of RM10 be expanded to include educational loan/scholarship agreement to pursue education at all levels including certificate (education/skills/professionals) in any educational and training institutions.

    This would help to streamline the stamp duty treatment for all levels of education.

    Effective Date

    For educational loan/scholarship agreement executed from 1 June 2023.

    Comments

    The rationale could be to provide greater clarity and consistency in the stamp duty treatment for all educational levels.

    This could simplify the administrative process and reduce the burden on taxpayers while supporting access to education at all levels.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Extension of Stamp Duty Exemption on Restructuring or Rescheduling of Loan/Financing Agreement

    Extension of Stamp Duty Exemption on Restructuring or Rescheduling of Loan/Financing Agreement

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    On the restructuring or rescheduling of a loan or financing arrangement between borrowers and financial institutions that is executed from January 1, 2022, to December 31, 2022, a full exemption from stamp duty is granted, provided that the following conditions are met:

    1. the original loan/financing agreement has been duly stamped; and
    2. restructuring or rescheduling of the loan/financing agreement does not have the element of additional value to the original amount of loan/ financing.

    Proposal

    It has been suggested that the full stamp duty exemption on restructuring or rescheduling of the loan or financing arrangement be extended for a period of 2 years.

    This would help to lower the cost of borrowing and would improve the cash flow of borrowers.

    Effective Date

    For restructuring or rescheduling of loan/financing agreement executed from 1 January 2023 until 31 December 2024.

    Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]

    CTIM asked if stamp duty has already been paid on these instruments executed after 31 December 2022 until the announcement of the exemption and publication in the gazette, will a refund be available, and how the taxpayer should go about seeking the refund.

    LHDNM’s Feedback:

    Further exemptions have been announced on 2 May 2023 under the Stamp Duty (Exemption) (No.11) 2021 (Amendment) Order 2023, P.U.(A) 141/2023.

    Applications for refunds must be made through the STAMPS system using the original adjudication number used to pay the ad valorem duty.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    20
  • Special Tax Deduction for Expenditure on Malaysian-Made Handicraft by Hotel Industry

    Special Tax Deduction for Expenditure on Malaysian-Made Handicraft by Hotel Industry

    Updated on 15 July 2023 - Dialogue between MOF,LHDNM, and CTIM [21/6/2023]

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    The hotel industry has the opportunity to advertise itself as an enabler and assist in promoting the use of local handicraft products within the premises.

    Some examples of these products include songket decorations, ceramic, and wood-based products.

    Under normal circumstances, Capital Allowance is granted under Schedule 3 of the Income Tax Act 1967 when an eligible asset (if qualified as a “plant”) is purchased.

    Assets with a life span of less than two years are deductible on a replacement basis; subsequent purchases to replace an asset with a value of less than RM2,000 are eligible for a tax deduction under Section 33 of the Income Tax Act 1967.

    Proposal

    It is proposed that a special tax deduction be given for expenditures on qualified Malaysian-made handicrafts purchased from handicraft entrepreneurs certified by Perbadanan Kemajuan Kraftangan Malaysia incurred by hoteliers.

    The amount of this deduction would be capped at RM150,000.

    The purpose of this proposal is to support the recovery of Malaysian-made handicraft.

    Effective Date

    For eligible expenditure on handicraft products incurred from 1 January 2023 until 31 December 2025

    Dialogue between MOF, LHDNM and CTIM [21/6/2023]

    As mentioned under the current position, the purchase for replacement of assets with a value of less than RM2,000 qualifies for outright deduction under S.33 of the ITA 1967.

    CTIM was seeking confirmation on whether this is a concession given by the IRB and where it is legislated.

    LHDNM’s Feedback:

    • It is not a concession.
    • For asset categories valued at RM2,000 and below, claims can be made through:
      • Special allowance claims under paragraph 19A of Schedule 3 of the ITA 1967; or
      • Capital allowance claims under paragraphs 10 and 15 of Schedule 3 of the ITA 1967.
    • For assets with a useful life not exceeding two years, claims can be allowed on a replacement basis under Section 33 of the ITA 1967.

    Are taxpayers given an option whether to choose a special tax deduction claim on the items or to claim capital allowance / outright tax deduction under S33 if, let’s say, this item is potentially a long-lasting item that is capital in nature?

    LHDNM’s Feedback:

    Companies are allowed to choose to claim eligible capital expenditure as:

    • special tax deduction for Malaysian handicraft products; or
    • deduction under subsection 33(1) of the ITA 1967; or
    • capital allowance under Schedule 3 of the ITA 1967.

    The tax treatment option, once decided, is final and cannot be amended.

    CTIM sought clarification on what are the “ceramic and wood-based products in hotel premise” in the context illustrated.

    MOF’s Feedback: The product details will be discussed with the Malaysian Handicraft Development Corporation (PKKM) and will be informed accordingly through guidelines.

    Disclaimer:

    The articles, templates, and other materials on our website are provided only for your reference.

    While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.

    If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:

    1. Verify that the information provided is current, accurate, and complete.
    2. Seek additional professional opinions, as the scope and extent of each issue, may be unique.

    免责声明:

    我们网站上的文章、模板和其他材料只供参考。

    虽然我们努力确保所提供的信息是最新和准确的,但我们不能保证网站或其内容,包括任何相关图形的完整性、可靠性、适用性或可用性。因此,您需要承担使用这些信息所带来的风险。

    如果你打算使用我们的视频和出版物的内容作为参考,我们建议你采取以下步骤:

    1. 核实所提供的信息是最新的、准确的和完整的。
    2. 寻求额外的专业意见,因为每个问题的范围和程度,可能是独特的。

    Keep in touch with us so that you can receive timely updates

    请与我们保持联系,以获得即时更新。

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    21
  • Employment of Inmate and Ex-Inmate of Henry Gurney School and Institutions under the SWD

    Employment of Inmate and Ex-Inmate of Henry Gurney School and Institutions under the SWD

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    An employer is allowed a further deduction on remuneration paid to the following categories of employees:

    • a senior citizen who shall be 60 years and above
    • an ex-convict
    • a parolee
    • a supervised person, or
    • an ex-drug dependant.

    To qualify for further deduction, the following conditions apply:

    • the employee is employed on a full-time basis;
    • the monthly remuneration does not exceed RM4,000
    • the employer and employee are not the same person
    • the employer is not —
      • a spouse
      • a parent (including a step-parent or parent-in-law)
      • a child (including a step-child or adopted child)
      • a brother or sister (including step-brother or step-sister), or
      • a grandparent or a grandchild (including a step-grandparent or a step-child), and
    • the employer must produce a written confirmation from the Malaysian Prison Department or the National Anti-Drugs Agency in the case of an ex-drug dependant.

    The tax incentive is given until year of assessment 2025.

    Proposal

    In line with Malaysia’s Sustainable Development Goals (SDG) 2030 which aimed to provide suitable job opportunities without neglecting certain group, it is proposed the scope of tax incentive be expanded to include remuneration paid to inmate and ex-inmate of:

    • Henry Gurney School under Malaysian Prison Department,
    • Protection and rehabilitation institution and non-government care centres registered under the Social Welfare Department (SWD).

    Effective Date

    From the year of assessment 2023 until the year of assessment 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    20
  • Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Import Duty and Sales Tax Exemption on Nicotine Replacement Therapy

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Smoking cessation services at Government health clinics and hospitals have been implemented since 2000.

    Starting in 2015, this programme expanded to private health facilities, including hospitals, clinics and pharmacies, through public and private collaboration under the mQuit Programme.

    In this programme, Nicotine Replacement Therapy (NRT) is used as one of the medical treatment options for smoking cessation.

    The NRT aims to supply smokers with enough nicotine to gradually reduce the symptoms of addiction without the harmful substances resulting from burning cigarettes or heating the liquid of electronic cigarettes.

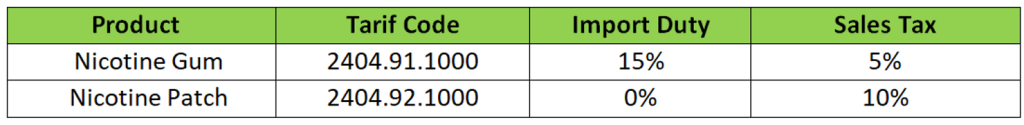
    Two NRT products in the market are subject to import duty and sales tax as follows:

    Proposal

    To support the mQuit Programme and encourage the use of NRT as an option for smoking cessation, it is proposed that import duty and sales tax exemption be given to nicotine gum and nicotine patch for a period of 3 years.

    Effective Date

    For applications received by the Ministry of Finance from 1 April 2023 until 31 March 2026.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/

    18
  • Tax Deduction for Sponsorship of Smart Artificial Intelligence (AI)-Driven Reverse Vending Machine

    Tax Deduction for Sponsorship of Smart Artificial Intelligence (AI)-Driven Reverse Vending Machine

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    In December 2021, the Malaysia Plastic Sustainability Roadmap, 2021–2030 (hereinafter “the Roadmap”) was published in Malaysia. The Roadmap identifies strategies and concrete action plans for achieving plastic circularity within the country.

    The Roadmap presents the concept and mechanism of a circular economy and analyzes the current state of policy measures, regulations, technologies, R&D, and economics with regard to the entire life cycle of plastics from production to disposal, outlining responding action plans.

    This road map is intended to serve as a set of guidelines for all relevant stakeholders in ensuring sustainability throughout the plastic value chain, with the end goal being the creation of new value that is beneficial to society and the environment.

    Three objectives for controlling plastics as set out in the Roadmap are:

    • To sustainably address plastic pollution in Malaysia, ensuring economic development, environmental protection and societal wellbeing;
    • To provide guidance and promote sustainable business practices in ensuring plastics circularity and sustainability through circular economy approach; and
    • To harmonise actions along plastic value chain through adoption of life cycle approach.

    Following this road map, the government’s objective is to maximise the percentage of plastic collected for recycling to 40% by 2025.

    Tax deductions under Section 34(6)(h) of the Income Tax Act 1967 can be given to any relevant person who carries out community projects that provide significant benefits to the public in Malaysia related to the fields of education, health, housing, infrastructure, information and communication technology or maintenance of a building designated as a heritage site, projects to increase the income of the poor as well as environmental preservation/conservation projects.

    Approval requirements include:

    1. projects benefiting only the public in Malaysia without having any interest in contributors; and
    2. projects that are voluntarily contributed and are not required by the authorities under any regulation.

    Proposal

    To support the recycling of plastic waste as an economic resource and to ensure the collected-for-recycling rate can be increased through a more effective and organised plastic waste collection programme, it is proposed that tax deduction under Section 34(6)(h) of the Income Tax Act 1967 be given to companies and other than companies (individuals, partnerships, trusts and cooperatives that have business income) that make donations or sponsorships of Artificial Intelligence (AI) – Driven Reverse Vending Machine.

    Effective Date

    For contribution/sponsorship and application received by the Ministry of Finance from 1 April 2023 until 31 December 2024.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is, therefore, strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    20
  • Review of Tax Incentives for Food Production Project

    Review of Tax Incentives for Food Production Project

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    Certain food production projects, including the planting of vegetables, fruits, kenaf, herbs or spices; the rearing of cows, buffaloes, goats or sheep; and aquaculture and deep-sea fishing, are eligible for certain tax incentives, provided that applications were received by the Ministry of Agriculture and Food Security (MAFS) by December 31, 2022.

    Tax incentives for food production projects are given under the:-

    • Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]
    • Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]

    Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]

    • An investment company that undertakes investment in a subsidiary company engaging in a new food production project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made; and

    Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]

    • A qualified person (which includes companies, sole proprietorships, partnerships and associations solely engaged in agriculture or fishery) that is resident in Malaysia and is engaging in food production projects is exempted from the payment of income tax in relation to:
      1. A new project is given income tax exemption of 100% on statutory income for 10 years of assessment; or
      2. An expansion project for an existing company is given an income tax exemption of 100% on statutory income for 5 years of assessment.

    New project

    A project which involves the following:

    1. Planting of industrial crops, vegetables, fruits, herbs, spices and cash crops;
    2. Aquaculture;
    3. Rearing of honey and urena lobata bees;
    4. Rearing of cows, buffaloes, goats, sheep and deer;
    5. Deep-sea fishing; and
    6. Planting of feed mill (cultivated in a project which has been identified by the Minister charged with the responsibility of that project and approved by the Minister)

    In year 2021, the scope of the food production project was expanded to planting of seeds for agro-food and high seas fishing projects.

    Expansion project

    A project:

    1. To expand the new project (as above)
    2. Which involves a new area of land; and
    3. Which is approved by the Minister

    Proposal

    To further promote the participation of industry players in the agriculture sector and to ensure the security of domestic food supply, it is proposed tax incentives be reviewed as follows:

    • scope of tax incentives is expanded to include agricultural-based projects on Controlled Environment Agriculture (CEA); and
    • the tax incentive is extended for 3 years.

    Effective Date

    For applications received by MAFS from 1 January 2023 until 31 December 2025

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    16