In December 2021, the Malaysia Plastic Sustainability Roadmap, 2021–2030 (hereinafter “the Roadmap”) was published in Malaysia. The Roadmap identifies strategies and concrete action plans for achieving plastic circularity within the country.
The Roadmap presents the concept and mechanism of a circular economy and analyzes the current state of policy measures, regulations, technologies, R&D, and economics with regard to the entire life cycle of plastics from production to disposal, outlining responding action plans.
This road map is intended to serve as a set of guidelines for all relevant stakeholders in ensuring sustainability throughout the plastic value chain, with the end goal being the creation of new value that is beneficial to society and the environment.
Three objectives for controlling plastics as set out in the Roadmap are:
To sustainably address plastic pollution in Malaysia, ensuring economic development, environmental protection and societal wellbeing;
To provide guidance and promote sustainable business practices in ensuring plastics circularity and sustainability through circular economy approach; and
To harmonise actions along plastic value chain through adoption of life cycle approach.
Following this road map, the government’s objective is to maximise the percentage of plastic collected for recycling to 40% by 2025.
Tax deductions under Section 34(6)(h) of the Income Tax Act 1967 can be given to any relevant person who carries out community projects that provide significant benefits to the public in Malaysia related to the fields of education, health, housing, infrastructure, information and communication technology or maintenance of a building designated as a heritage site, projects to increase the income of the poor as well as environmental preservation/conservation projects.
Approval requirements include:
projects benefiting only the public in Malaysia without having any interest in contributors; and
projects that are voluntarily contributed and are not required by the authorities under any regulation.
Proposal
To support the recycling of plastic waste as an economic resource and to ensure the collected-for-recycling rate can be increased through a more effective and organised plastic waste collection programme, it is proposed that tax deduction under Section 34(6)(h) of the Income Tax Act 1967 be given to companies and other than companies (individuals, partnerships, trusts and cooperatives that have business income) that make donations or sponsorships of Artificial Intelligence (AI) – Driven Reverse Vending Machine.
Effective Date
For contribution/sponsorship and application received by the Ministry of Finance from 1 April 2023 until 31 December 2024.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is, therefore, strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
Certain food production projects, including the planting of vegetables, fruits, kenaf, herbs or spices; the rearing of cows, buffaloes, goats or sheep; and aquaculture and deep-sea fishing, are eligible for certain tax incentives, provided that applications were received by the Ministry of Agriculture and Food Security (MAFS) by December 31, 2022.
Tax incentives for food production projects are given under the:-
Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]
Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]
Income Tax (Deduction of Investment in New Food Production Project or Expansion Project) Rules 2020 [P.U.(A) 374]
An investment company that undertakes investment in a subsidiary company engaging in a new food production project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made; and
Income Tax (Exemption) (No. 6) Order 2020 [P.U.(A) 373]
A qualified person (which includes companies, sole proprietorships, partnerships and associations solely engaged in agriculture or fishery) that is resident in Malaysia and is engaging in food production projects is exempted from the payment of income tax in relation to:
A new project is given income tax exemption of 100% on statutory income for 10 years of assessment; or
An expansion project for an existing company is given an income tax exemption of 100% on statutory income for 5 years of assessment.
Planting of industrial crops, vegetables, fruits, herbs, spices and cash crops;
Aquaculture;
Rearing of honey and urena lobata bees;
Rearing of cows, buffaloes, goats, sheep and deer;
Deep-sea fishing; and
Planting of feed mill (cultivated in a project which has been identified by the Minister charged with the responsibility of that project and approved by the Minister)
In year 2021, the scope of the food production project was expanded to planting of seeds for agro-food and high seas fishing projects.
Expansion project
A project:
To expand the new project (as above)
Which involves a new area of land; and
Which is approved by the Minister
Proposal
To further promote the participation of industry players in the agriculture sector and to ensure the security of domestic food supply, it is proposed tax incentives be reviewed as follows:
scope of tax incentives is expanded to include agricultural-based projects on Controlled Environment Agriculture (CEA); and
the tax incentive is extended for 3 years.
Effective Date
For applications received by MAFS from 1 January 2023 until 31 December 2025
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Therefore, any reliance on such information is strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
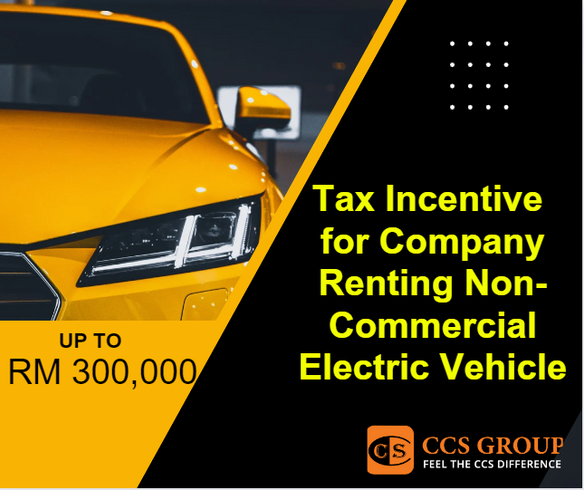
Companies renting non-commercial motor vehicles, including Electric Vehicles (EV), are given tax deductions under Section 39(1)(k), Income Tax Act 1967, as follows:
cost of the vehicle not exceeding RM150,000, the maximum rental amount allowed for tax deduction is limited up to RM100,000; and
cost of the vehicle exceeding RM150,000, the maximum rental amount allowed for tax deduction is limited to RM50,000.
The tax treatment is effective from the year of assessment 2002.
Proposal
The maximum rental amount for electric vehicles that can be deducted for tax purposes is proposed to be capped at RM300,000 to incentivise the use of low-carbon automobiles.
Effective Date
From the year of assessment 2023 until the year of assessment 2025.
Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]
Currently, the capital allowance (“CA”) treatment for a non-commercial electric vehicle (“EV”) is provided under Para 2(2) of Sch 3 of the ITA 1967.
Similar to the above proposed RM300,000 limit for a tax deduction on rental, CTIM suggested that the limit for qualifying plant expenditure incurred on a non-commercial EV should be increased to RM300,000 in a corresponding PU Order on capital allowance to encourage usage of low-carbon vehicles and for neutral tax treatment on leased vehicles and purchased vehicles.
MOF’s Feedback:
This proposal has been duly noted.
However, MOF will conduct further studies on the impact of the proposal.
CTIM appreciated the Government’s policy to have incentives for short periods, but three years appears too short when adopting non-commercial EVs. It is recommended to have a longer window to provide more certainty for taxpayers who are considering this option.
MOF’s Feedback:
This proposal has been duly noted.
Introducing a 3-year leasing period is intended to assess companies’ acceptance and utilisation of green mobility.
By doing so, it will provide the government with the opportunity to review this initiative and make interventions/improvements if necessary.
CTIM sought confirmation on the above effective date means that the first rental for the noncommercial EV must be during the period from YA 2023 to YA 2025, and the tax deduction for the entire RM300,000 amount does not necessarily need to be claimed during this period.
For example, if the non-commercial EV is rented in 2025 and the company continues to pay for that same vehicle up to 2027, then the company can claim the tax deduction on the rental up to 2027 as long as the RM300,000 cap is not breached.
This same principle should apply to the CA CTIM asked for above as long as the non-commercial EV is purchased from YA 2023 to YA 2025.
MOF’s Feedback:
Details of tax treatments are being finalised.
Appendix 14 states “proposed company”. CTIM suggested that it should apply to any person carrying on a business.
Response from LHDNM (Inland Revenue Board):
The eligible companies for this incentive are companies as interpreted under Section 2 of the ITA 1967.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
“Bio Nexus Status Company” means a company incorporated under the Companies Act 2016 [Act 777] engaged in the life sciences business.
Tax incentives for BioNexus status companies are given as follows:
a company undertaking biotechnology activity and approved with BioNexus status:
Income Tax Exemption of 70% on statutory income commencing from the first statutory income for a period of 10 or 5 years, subject to new or existing business (expansion project);
concessionary tax rate of 20% on income from qualifying activities for 10 years upon the expiry of the tax exemption period;
Double Tax Deduction on research & development expenditure;
Industrial Building Allowance on building for biotechnology research activities; and
Import Duty Exemption on raw materials / components and machinery / equipment.
a company that undertakes investment in a BioNexus status subsidiary company engaging in a new project is given a tax deduction equivalent to the amount of investment made in the basis year the investment is made.
The tax incentive is for applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2021 until 31 December 2022.
Proposal
To encourage more industry players, it is proposed tax incentives be reviewed as follows:
income tax exemption on statutory income be increased from 70% to 100%; and
the application period for tax incentives is extended for 2 years.
Effective Date
For applications received by the Malaysian Bioeconomy Development Corporation from 1 January 2023 until 31 December 2024.
Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]
BioNexus status companies also get an income tax exemption which is equivalent to the allowance based on 100% of qualifying capital expenditure (“QCE”), i.e. Investment Tax Allowance (“ITA”).
CTIM sought to confirm that the proposed two years application period extension applies to all tax incentives for BioNexus status companies, including the ITA and is not just restricted to the items listed in Appendix 19.
MOF’s Feedback:
Extending the 2-year application period applies to all tax incentives for BioNexus status companies, including the Investment Tax Allowance.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
Under the National Automotive Policy 2020 and the Low Carbon Mobility Blueprint 2021 – 2030, Malaysia is making significant strides toward developing an ecosystem for electric mobility.
The National Automotive Policy 2020 was launched on February 21, 2020, with the goal of improving the automotive industry during the digital industrial transformation era. Its focus is on Next-Generation Vehicles (NxGV), Industrial Revolution 4.0 (IR 4.0), and Mobility-as-a-Service (MaaS) to position Malaysia as a regional leader in manufacturing, engineering, and technology.
The policy builds upon the objectives of the NAP 2014, which aimed to establish Malaysia as a hub for Energy Efficient Vehicles (EEV) through research and development capabilities for right-hand drive vehicles and related technologies such as fuel efficiency, light materials, telematics, tooling, and component design. To widen the infrastructure network of charging equipment, it is vital to ensure that the product can be produced locally at competitive cost.
Proposal
It is proposed that the following tax incentives be offered to better complement the ecosystem for electric vehicles and to attract immediate high-value investment in the manufacturing of electric vehicle charging equipment.
income tax exemption of 100% on statutory income from the year of assessment 2023 to the year of assessment 2032. Companies that make early investments are eligible to enjoy tax exemption for a period up to 10 years. Thus, companies that make investments after the year of assessment 2023 are eligible to enjoy the remaining exemption period only; or
Investment Tax Allowance of 100% for 5 years, and it can be used to offset up to 100% of statutory income for each year of assessment.
Effective Date
For applications received by the Malaysian Investment Development Authority (MIDA) from 25 February 2023 until 31 December 2025.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
Automation Capital Allowance (ACA) is a tax incentive introduced in Budget 2015 to encourage manufacturers to engage in innovative and productive activities, expedite the adoption of automation, especially for labour-intensive industries, and further spur automation initiatives.
The incentive is split into 2 categories of industries i.e.
Category 1: High Labour-intensive Industries (Rubber products, plastics, wood, furniture and textiles); and
Category 2: Industries Other than Category 1
It was proposed in Budget 2020 that the existing Automation Capital Allowance (ACA) incentive for Category 2 of the manufacturing sector be expanded to the services sector to boost productivity and efficiency in labour-intensive industries.
Manufacturing and services companies which incur qualifying capital expenditure on automation equipment are given tax incentives as follows:
Category 1: Labour-Intensive Industry (rubber, plastic, wood and textile products)
ACA of 100% for automation equipment on the first RM4 million for Qualifying Capital Expenditure incurred and can be utilised within 1 year.
Category 2: Industries other than Category1 including the services sector
ACA of 100% for automation equipment on the first RM2 million for qualifying capital expenditure incurred and can be utilised within 1 year.
Both categories are eligible for income tax exemption equivalent to 100% of qualifying capital expenditure incurred for automation equipment. Thus, eligible capital expenditure that can be absorbed is 200%within a year.
The tax incentive is for applications received by the Malaysian Investment Development Authority (MIDA) until 31 December 2023.
Guideline and Procedure for the Application of Automation Capital Allowance (Automation CA) for Services Sector – for an existing company only.
To further drive productivity and improve efficiency through automation, it is proposed the ACA for automation equipment be enhanced as follows:
scope of automation to include the adaptation of Industry 4.0 elements;
scope of tax incentives is expanded to include the agriculture sector; and
capital expenditure threshold for categories 1, 2 and agriculture be aligned and increased to RM10 million.
For applications received by MIDA and the Ministry of Agriculture and Food Security (MAFS) from 1 January 2023 until 31 December 2027.
Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]
CTIM proposed the mutually exclusive rules to be applied on an asset basis instead of a company basis.
MOF’s Feedback:
The proposal was duly noted.
Further studies will be conducted regarding the mutually exclusive clause to ensure its suitability for implementation.
For assets under hire purchase, kindly confirm there is no requirement for the hire purchase instalments to commence and end within the qualifying period from 1 January 2023 until 31 December 2027 to qualify for the accelerated capital allowance (“ACA”) claim.
In essence, as long as it is a qualifying asset, the incentive applies to the whole capital expenditure incurred.
LHDNM’s Feedback:
The ACA incentive also applies to assets acquired through hire-purchase agreements.
The eligible capital expenditure for hire-purchased assets is the principal amount incurred during the basic period of a particular assessment year for assets acquired between 1 January 2023 and 31 December 2027.
Therefore, principal payments made outside the incentive period are not eligible to enjoy this incentive.
ACA on capital expenditure up to RM10 million is welcomed.
Still, there should be clarity on whether it is a 200% allowance like in the past (i.e. 100% accelerated capital allowance plus 100% automation capital allowance) or just a 100% accelerated capital allowance.
LHDNM’s Feedback:
This extended Accelerated Capital Allowance (ACA) incentive refers to the incentive under ACA (Automation Enhancement).
This incentive should be read and applied with the income tax order that provides an exemption equal to 100% of the ACA (Automation Enhancement) amount.
This exemption applies to statutory income from eligible projects but is limited to 70%.
The characteristics of the incentive are the same as the original incentive.
This matter will be clarified in the relevant subsidiary legislation.
MOF’s Feedback:
The characteristics of the incentive will be the same as the original incentive.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
Malaysia plans to reach its Low Carbon Nation Aspiration by 2040, part of its National Energy Policy 2022–2040.
The government has devised a plan to control CO2 emissions using Carbon Capture and Storage Technology (CCS) to reach this goal.
In Malaysia, the oil and gas and power generation industries are seen as the first ones to use CCS technology.
This technology comprises of 3 activities as follows:
carbon capture;
transportation of captured CO2; and
underground or sea bed carbon storage.
Proposal
To recognise CCS activities as a new source of economic growth and to achieve net zero greenhouse gas emissions, it is proposed tax incentives be given as follows:
i. companies undertaking CCS in-house activity
Investment Tax Allowance (ITA) of 100% of qualifying capital expenditure for a period of 10 years and can be set off against up to 100% of business statutory income;
full import duty and sales tax exemption on equipment for CCS technology commencing from 1 January 2023 until 31 December 2027; and
tax deduction for allowable pre-commencement expenses within 5 years before the date of commencement of operation.
ii. companies undertaking CCS services
ITA of 100% of qualifying capital expenditure for a period of 10 years and can be set off against up to 100% of statutory income; or
tax exemption of 70% on statutory income for a period of 10 years; and
full import duty and sales tax exemption on equipment for CCS technology starting 1 January 2023 until 31 December 2027.
iii. companies engaging in CCS services are to be given tax deductions on fees incurred for using CCS services.
Effective Date
For applications received by the Ministry of Finance from 25 February 2023 until 31 December 2027.
The tax deduction can be claimed through the Income Tax Return Form from the year of assessment 2023 until 2027.
Updated on 15 July 2023- Dialogue between MOF, LHDNM, and CTIM [21/6/2023]
In Budget 2023, the Government proposed the introduction of a raft of tax incentives for carbon capture and storage (“CCS”).
CTIM believed the Government intends for these tax incentives to be available for a broad range of CCS applications across different industrial subsectors (e.g. oil & gas, concrete, plastics, etc.). CTIM sought confirmation.
MOF’s Feedback:
As an introduction to the incentive, the government plans to provide incentives to companies/businesses engaged in carbon capture and compression activities, converting it into liquid form and subsequently storing it through injection methods into geological reservoirs at the seabed using carbon capture and storage (CCS) technology.
With regard to the proposed tax deduction for allowable pre-commencement expenses incurred by Companies undertaking CCS in-house activity within five years from the date of commencement of operation, CTIM sought clarification on the following:
What types of allowable pre-commencement expenses did the Government envisage when proposing this?
Whether the date of commencement of operation refers to the date of commencement of the operation of such company (i.e. new company) or the date of commencement of CCS in-house activity? If the latter, please clarify why this is considered a pre-commencement expense, given that the company would already have commenced operation and is already generating income.
Please clarify if this should also be extended to companies undertaking CCS services.
MOF’s Feedback:
Details of allowable pre-operational expenses and the commencement date of operations will be issued in a detailed guideline that will be published for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
Presently, pre-operational expenses only apply to companies engaged in carbon capture and storage activities.
With regard to the proposed tax deduction on fees incurred for the use of CCS services, CTIM sought clarification on the following:
Please confirm this deduction is meant to be a further deduction.
Whether this is subject to the application received by MOF from 25 February 2023 until 31 December 2027?
Is tax deduction limited to fees incurred from 25 February 2023 until 31 December 2027?
LHDNM’s Feedback:
This incentive will be explained in detail in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
Investment tax allowance for qualifying capital expenditure:
Whether MOF or IRB will issue a list of CCS technologies that qualify for the incentive?
How will the MOF determine the effective date for a chargeable person to qualify for the incentive?
MOF’s Feedback:
Detailed information on the list of CCS technologies and the effective date for eligible taxpayers to qualify for this incentive will be provided in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
Which will be the qualifying person for the tax exemption? (e.g. Identified companies/operators or entities authorised by relevant approving authority)
LHDNM’s Feedback:
This incentive will be explained in detail in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
If a company undertakes “carbon capture” in-house activity and also subscribed to “carbon storage” services from external parties, would the company be eligible for both CCS incentives under proposal items (i) and also (iii) of Appendix 16 to the Budget Speech?
LHDNM’s Feedback:
This incentive will be explained in detail in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
CTIM would like to confirm which Government authority will be the governing body for CCS activities.
MOF’s Feedback:
Details of the administering body for CCS activities will be finalised and explained in detail in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
It was also mentioned in Appendix 16 that tax deduction can be claimed through the Income Tax Return Form (“ITRF”) from YA 2023 until YA 2027.
CTIM urged the Authorities to extend the period to YA 2028 to cater for companies that are having a basis period ending on a date other than 31 December.
LHDNM’s Feedback:
This incentive will be explained in detail in the guidelines that will be issued for general reference in the near future.
MOF is currently in the process of specifying the relevant details.
Disclaimer:
The articles, templates, and other materials on our website are provided only for your reference.
While we strive to ensure that the information presented is current and accurate, we cannot guarantee the completeness, reliability, suitability, or availability of the website or its content, including any related graphics. Consequently, any reliance on this information is entirely at your own risk.
If you intend to use the content of our videos and publications as a reference, we recommend that you take the following steps:
Verify that the information provided is current, accurate, and complete.
Seek additional professional opinions, as the scope and extent of each issue, may be unique.
To alleviate the burden of working parents, effective from the YA 2017, a new paragraph 46(1)(r) of the ITA was introduced to provide a tax deduction to individuals on the amount expended in respect of the payment for child care fees to a child care centre or a kindergarten for a child of that individual aged six years and below.
The establishment of the child care centre must be registered with the DSW under the Child Care Centre Act 1984 [Act 308] under the Ministry of Women, Family and Community Development, while a kindergarten is subject to the Education Act 1996 [Act 550] and must be registered with the State Education Department under the Ministry of Education.
The amount of deduction allowed is limited to a maximum of RM3,000 for the years of assessment 2020 and 2021. regardless of the number of children sent to the child care centre or kindergarten.
This income tax relief is extended until the year of assessment 2023 as announced in Budget 2022.
This deduction can only be claimed by a husband or a wife and must be supported by:-
birth document of the child, such as MyKid or birth certificate; and
receipts of the monthly fees issued by the such child care centre or kindergarten.
Separate Assessment
Where a husband and a wife are assessed separately, the tax deduction under this paragraph can only be claimed either by the husband or the wife who incurs the expenses.
Divorced Couple
Where a husband and a wife are divorced, the tax deduction can be claimed by the former husband and the former wife provided that they both made payment for the child care fees and that child is not the same child.
Proposal
To ease parents’ financial burden in providing early education for children, it is proposed tax relief of up to RM3,000 be extended for a year.
Effective Date
For the year of assessment 2024.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
RA was extended to the agricultural sector to encourage local food production and thus increase its supply.
In Budget 2003, chicken and duck farmers who switched from an open house system to a closed house system were given Reinvestment Allowance (RA) for 15 consecutive years.
The RA is given on 60% of qualifying capital expenditure incurred and is allowed to be set off against 70% (100% for promoted areas) of statutory income.
For YAs 2009 and 2010, chicken and duck rearers who reinvest to expand the closed house system in existing or new locations approved by the Ministry of Agriculture and Agro-based Industry are given incentives as follows:
projects located in the promoted areas are eligible for RA of 60% on qualifying capital expenditure to be set off against 100% of the statutory income, and
projects located outside the promoted areas are eligible for RA of 60% on qualifying capital expenditure to be set off against 70% of the statutory income.
Proposal
To encourage more chicken rearers to adopt an environmental-friendly closed house system, it is proposed tax incentives be given as follows:
Accelerated Capital Allowance (ACA) 100% on the qualifying capital expenditure; and
Income Tax Exemption of 100% equivalent to the qualifying capital expenditure.
These tax incentives are given on the Qualifying Capital Expenditure incurred from the year of assessment 2023 until the year of assessment 2025 and are to be fully absorbed within a year.
Effective Date
From the year of assessment 2023 until the year of assessment 2025.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is, therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |
A Company or Limited Liability Partnership (LLP) that has a paid-up capital of RM2.5 million and below with an annual sales turnover not exceeding RM50 million is categorised as Micro, Small and Medium Enterprises (MSME).
They are subjected to income tax of:
17% (preferential tax rates) for the first RM600,000 of chargeable income; and
24% (prevailing tax rate) on the remaining chargeable income.
Proposal
To boost MSME competitiveness and promote economic growth, it is suggested to cut the tax rate on chargeable income for the first RM150,000 from 17% to 15%, while maintaining the tax rates for the remaining taxable income at 17% and 24% as follows:-
Effective Date
For the year of assessment 2023.
Comments
The reduction of tax rates for the first RM150,000 of chargeable income can provide some relief for MSMEs, which are often cash-strapped and struggling to stay afloat, especially during the COVID-19 pandemic.
By reducing their tax burden, MSMEs can have more resources to invest in their business and grow their operations. This, in turn, can contribute to economic growth and job creation.
Footnotes
A MSME will not be entitled to the preferential tax rate if more than:
50% of the paid-up capital of its ordinary shares is directly or indirectly owned by a related company
50% of the paid-up capital of the ordinary shares of the related company is directly or indirectly owned by the first-mentioned company, or
50% of the paid-up capital of the ordinary shares of the first-mentioned company and the related company is directly or indirectly owned by another company.
“Related Company” means a company which has a paid-up capital in respect of its ordinary shares of more that RM2.5m at the beginning of the basis period for a year of assessment.
Practice Note
The Inland Revenue Board (IRB) released Practice Note No 3/2020 and Practice Note No 4/2020 to explain gross income from business sources of not more than RM50m.
According to the practice note, investment holding companies not listed on Bursa Malaysia are not eligible for the preferential tax rate because they do not have business income. However, Investment holding companies listed on Bursa Malaysia will be considered to have business income and qualify for the preferred tax rate.
Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is therefore strictly at your own risk.
Keep in touch with us so that you can receive timely updates |