Tag: Accelerated Capital Allowance

  • Tax Incentives for Chicken Rearing in Closed House System

    Tax Incentives for Chicken Rearing in Closed House System

    Update: The Ismail Sabri Government Budget is no longer applicable. Malaysia’s national budget for 2023 was re-tabled again in February 2023.

    To Download Revised Budget 2023 Speech and some other related publications – https://www.ccs-co.com/post/budget-2023-malaysia-madani

    Current Position

    RA was extended to the agricultural sector to encourage local food production and thus increase its supply.

    In Budget 2003, chicken and duck farmers who switched from an open house system to a closed house system were given Reinvestment Allowance (RA) for 15 consecutive years.

    The RA is given on 60% of qualifying capital expenditure incurred and is allowed to be set off against 70% (100% for promoted areas) of statutory income.

    For YAs 2009 and 2010, chicken and duck rearers who reinvest to expand the closed house system in existing or new locations approved by the Ministry of Agriculture and Agro-based Industry are given incentives as follows:

    • projects located in the promoted areas are eligible for RA of 60% on qualifying capital expenditure to be set off against 100% of the statutory income, and
    • projects located outside the promoted areas are eligible for RA of 60% on qualifying capital expenditure to be set off against 70% of the statutory income.

    Proposal

    To encourage more chicken rearers to adopt an environmental-friendly closed house system, it is proposed tax incentives be given as follows:

    1. Accelerated Capital Allowance (ACA) 100% on the qualifying capital expenditure; and
    2. Income Tax Exemption of 100% equivalent to the qualifying capital expenditure.

    These tax incentives are given on the Qualifying Capital Expenditure incurred from the year of assessment 2023 until the year of assessment 2025 and are to be fully absorbed within a year.

    Effective Date

    From the year of assessment 2023 until the year of assessment 2025.

    Our website's articles, templates, and material are solely for reference. Although we make every effort to keep the information up to date and accurate, we make no representations or warranties of any kind, either express or implied, regarding the website or the information, articles, templates, or related graphics that are contained on the website in terms of its completeness, accuracy, reliability, suitability, or availability. Any reliance on such information is, therefore strictly at your own risk.

    Keep in touch with us so that you can receive timely updates |

    要获得即时更新,请与我们保持联系

    1. Website ✍️ https://www.ccs-co.com/ 2. Telegram ✍️ http://bit.ly/YourAuditor 3. Facebook ✍

    4. Blog ✍ https://lnkd.in/e-Pu8_G 5. Google ✍ https://lnkd.in/ehZE6mxy

    6. LinkedIn ✍ https://www.linkedin.com/company/74734209/admin/
    22
  • Income Tax  (Accelerated Capital Allowance) (Excursion Bus) (Amendment) Rules 2022

    Income Tax (Accelerated Capital Allowance) (Excursion Bus) (Amendment) Rules 2022

    1. Excursion Bus purchases made between YA 2020 and YA 2021 are eligible for an Accelerated Capital Allowance (ACA) on capital expenses incurred by licensed tour operators.

    2. The ACA given by the Income Tax (Accelerated Capital Allowance) (Excursion Bus) Rules 2021 can be claimed within two years, with an initial allowance of 20% and an annual allowance of 40%.

    3. It was declared in Budget 2022 that the accelerated capital allowance claims on capital expenditure incurred for the purchase of excursion buses would be extended to the YA 2024.

    4. On 11 January 2022, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) of, and paragraphs 10 and 15 of Schedule 3 to, the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Accelerated Capital Allowance)(Excursion Bus) (Amendment) Rules 2022 [P.U. (A) 9] to legislate such extension.

    5. To Join our Telegram ✍️ http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 在2020及2021年的评估年度购买的游览巴士 (Excursion Bus),持旅游运营执照业者 [licensed tour operators] 所产生的资本支出,享有资本津贴加速 (Accelerated Capital Allowance, ACA) 的资格。

    2. 2021年所得税(资本津贴加速)(游览巴士) 细则给予的资本津贴加速,分别为20%的初始津贴 [Initial Allowance] 以及40%的年度津贴 [Annual Allowance] ,业者可以在两年内完全抵扣相关游览巴士的资本支出。

    3. 政府在2022年预算案中宣布,为购买游览巴士而产生的资本支出的加速资本津贴税务优惠,将延长到2024年的评估年度。

    4. 作为立法,2022 年 1 月 11 日,部长行使 1967年所得税法令 [法案53] 第154(1)(b) 段与附表3第10和15段所赋予的权力,在宪报上颁布了 2022年所得税(加速资本津贴)(游览巴士) 细则 [P.U. (A) 9]。

    5. 加入我们的 Telegram ✍️ http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    13
  • Deduction for Relocation Costs for Tun Razak Exchange Marquee Status Company

    Deduction for Relocation Costs for Tun Razak Exchange Marquee Status Company

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Deduction for Relocation Costs for Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [P.U. (A) 475]

    2. These Rules shall have effect from the year of assessment 2021. 3. Under these rules, the period of entitlement will be extended from December 31, 2020, to December 31, 2025. 4. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使 1967年所得税法令 [法案53] 第154(1)(b) 段所赋予的权力,在宪报上颁布了 2021年所得税(敦拉萨国际贸易中心 Marquee 地位公司搬迁费用的扣除)(修订) 细则 [P.U. (A) 475]。

    2. 这项细则将从2021年的评估年度开始生效。

    3. 此细则对2013年所颁布的细则作出修订: 👉 搬迁费用享有扣税资格的期限 👉 将从原有的2020年12月31日延长至2025年12月31日。

    4. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    8
  • Accelerated Capital Allowance – Tun Razak Exchange Marquee Status Company

    Accelerated Capital Allowance – Tun Razak Exchange Marquee Status Company

    1. On 27 December 2021, the Minister, in the exercise of the powers conferred by paragraph 154(1)(b) of the Income Tax Act 1967 [Act 53], gazetted the Income Tax (Accelerated Capital Allowance) (Tun Razak Exchange Marquee Status Company) (Amendment) Rules 2021 [P.U. (A) 474]

    2. These Rules are deemed to have effect from 1 January 2014.

    3. Under these rules, the period of entitlement to accelerated capital allowances for renovation costs incurred on a building or part of a building located in the Tun Razak Exchange used for the purpose of the company’s business will be extended from December 31, 2020, to December 31, 2025.

    4. Join our Telegram: http://bit.ly/YourAuditor

    🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻🌻

    1. 2021 年 12 月 27 日,部长行使1967年所得税法令 [法案53] 第154(1)(b) 段所赋予的权力,在宪报上颁布了2021年所得税 (资本津贴加速)(敦拉萨国际贸易中心 Marquee 地位公司)(修订) 细则 [P.U. (A) 474],并被视为自2014年1月1日起生效。

    2. 根据这项细则,位于敦拉萨国际贸易中心的建筑物或部分建筑物所产生并符合资格的装修费用,享有加速资本津贴的期间将从2020年12月31日延长到2025年12月31日。

    3. 加入我们的 Telegram: http://bit.ly/YourAuditor

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    10
  • Accelerated Capital Allowance (ACA) for the purchase of Machinery and Equipment

    Accelerated Capital Allowance (ACA) for the purchase of Machinery and Equipment

    Accelerated capital allowance (ACA) for the purchase of Machinery and Equipment – PDF

    1. It was proposed in the 2020 Economic Stimulus Package, announced on February 27, 2020, that accelerated capital allowance (ACA), comprised of a 20% initial allowance and a 40% annual allowance, be given on qualifying capital expenditure on machinery and equipment (including ICT equipment) incurred between March 2020 and December 2020.

    2. Following that, in the Short-Term Economic Recovery Plan (PENJANA) announced on June 5, 2020, it was recommended that the ACA be extended to cover such qualified expenditures through December 31, 2021.

    3. Will “office furnishings and fittings” be included in the definition?

    🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼🌼

    1. 在2020年2月27日宣布的2020年经济振兴配套中建议:

    👉 在2020年3月至2020年12月期间所发生的机械和设备(包括 ICT 设备)的合格资本支出

    👉 给予加速资本津贴 [ACA],即:20%的初始津贴和40%的年度津贴。

    2. 随后,在2020年6月5日宣布的《短期经济复苏计划》[PENJANA]中,建议延长加速资本津贴 [ACA] 的期限至2021年12月31日。

    3. “办公设备、办公家具和配件”是否包含在内呢?

    14
  • Income Tax (Accelerated Capital Allowance) (Excursion Bus) Rules 2021

    Income Tax (Accelerated Capital Allowance) (Excursion Bus) Rules 2021

    1) Licensed tour operators were given the ACA on capital expenses incurred on the purchase of excursion buses. The ACA provided under the Income Tax (Accelerated Capital Allowance) (Excursion Bus) Rules 2021 can be claimed within a period of 2 years with an initial allowance of 20% and an annual allowance of 40%.

    2) Budget 2022 has announced the extension of the accelerated capital allowance (ACA) claims on capital expenditure incurred for the purchase of excursion buses to YA 2024.

    7
  • Deduction for Expenses in relation to the Cost of Personal Protective Equipment

    Deduction for Expenses in relation to the Cost of Personal Protective Equipment

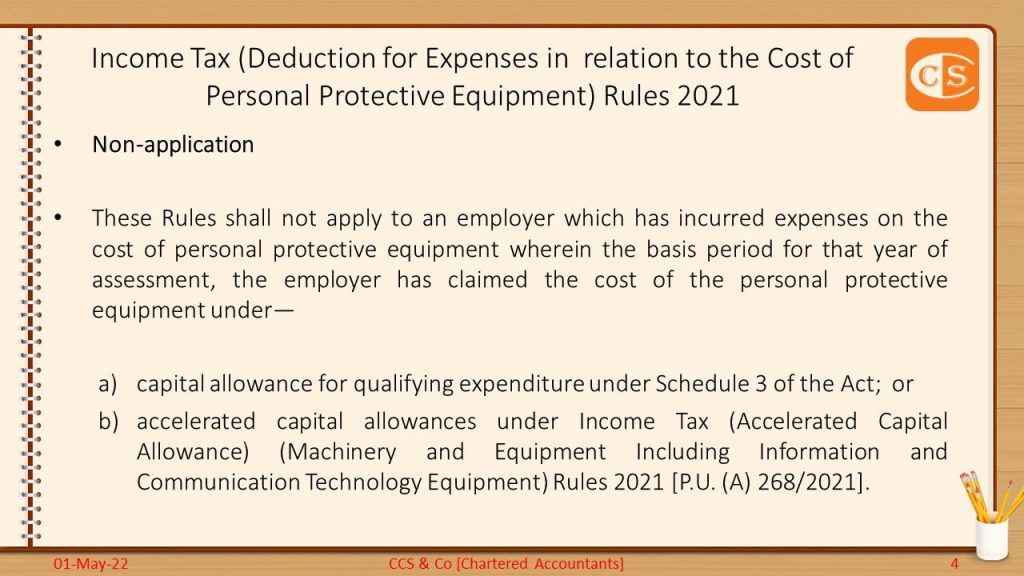
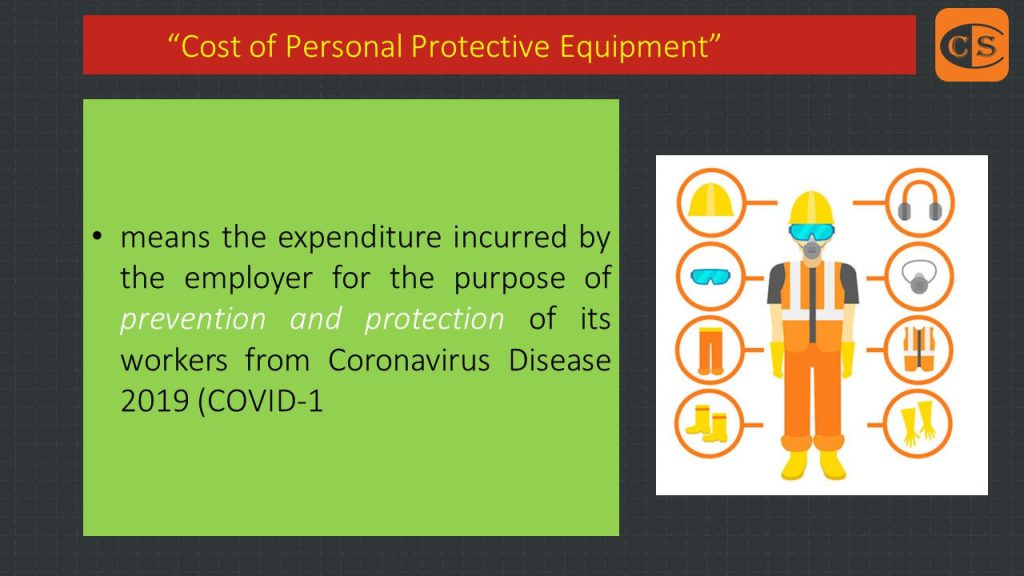
    1. Tax deductions for employers on the cost of personal protective equipment (PPE) are offered by the Income Tax (Deduction for Expenses in Relation to the Cost of Personal Protective Equipment) Rules 2021, which are effective from YA 2020 and define personal protective equipment (PPE) as “expenditure incurred by the employer for the purpose of prevention and protection of its workers from COVID-19.” 2. From the first day of March 2020, the deduction for spending on personal protective equipment (PPE) will be applied against adjusted income. 3. However, a deduction will not be given in which:

    • the employer has claimed capital allowances under the Income Tax Act on the cost of such personal protective equipment, or
    • the employer has claimed ACA under the Income Tax (Accelerated Capital Allowance) (Machinery and Equipment. Including Information and Communication Technology Equipment) Rules 2021 on the cost of such personal protective equipment.

    1. 2020年6月5日下午的直播,首相丹斯里慕尤丁在公布经济复苏短期计划时说:

    👉 政府将为公司提供各种有关防疫措施的税务回扣,其中业者作为商业用途购买的个人防护装备(PPE) ,或进行新冠肺炎检验的费用,可获扣税。

    2. 2021年6月15日,政府在宪报上,颁布了 2021年所得税(针对个人防护装备费用的扣税)细则 [Income Tax (Deduction for Expenses in relation to the Cost of Personal Protective Equipment) Rules 2021]

    3. 这个细则主要说的是:

    👉 雇主所购买的个人防护装备(PPE),可以直接扣税。

    4. 大家都知道,设备一般属于公司的资产,公司是不能直接拿相关的费用来扣税,都是需要通过资本津贴 [Capital Allowance] 的形式,分几年来慢慢扣税的。

    5. 因此,这个细则让公司加快扣税的速度

    6. 当然,大前提还是,公司要有赚钱,有 Adjusted Income 才能达到最大的效益

    7. 然而,如果公司已经选择申索资本津贴 [claim Capital Allowance] 的话,此细则就不适用

    [意思就是说,只能慢慢 Claim Capital Allowance 而不是能从 Adjusted Income 直接扣税了]

    13
  • Accelerated Capital Allowance (Machinery and Equipment including ICT Equipment)

    Accelerated Capital Allowance (Machinery and Equipment including ICT Equipment)

    1) IN exercise of the powers conferred by paragraph 154(1)(b) of, and paragraphs 10 and 15 of Schedule 3 to, the Income Tax Act 1967 [Act 53], the Minister makes these Rules, which were gazetted on 15 June 2021.

    2) These Rules shall have effect from the year of assessment 2020.。

    3) These rules provide that qualifying plant expenditure incurred by a person in the basis period for a year of assessment from 1 March 2020 until 31 December 2021 and used for the purpose of his business, capital expenditure incurred in relation to provision of machinery and equipment including information and communication technology equipment except motor vehicle qualify for an initial allowance of 20% and an annual allowance of 40%.

    4) As specified in the Income Tax (Accelerated Capital Allowance) (Machinery and Equipment, Including Information and Communication Technology Equipment) Rules 2021, capital portions of instalment payments made during the period on machinery and equipment purchased under hire purchase arrangements would be eligible for the ACA.

    5) Anyone who has incurred plant expenditure and has already claimed ACA under the Income Tax (Accelerated Capital Allowance) (Automation Equipment) Rules 2017 or exemption under the Income Tax (Exemption No 8) Order 2017 would not be eligible to claim. 1. 大家应该知道,公司买 Assets,只要符合 Plant 的定义,都可以扣税

    2. 但是,上述 (1)说到的扣税,不是直接从 Profit 扣,而是通过所谓的资本津贴 [Capital Allowance] 分几年慢慢 Claim

    3. 所谓的资本津贴 [Capital Allowance],又再细分为 Initial Allowance 及 Annual Allowance

    4. 一般上,Initial Allowance 都是 20%,而 Annual Allowance 则根据不同资产的类型,有着不同的 Rates

    5. 2021年6月15日,政府在宪报上,颁布了 2021年所得税(加速资本津贴)(机械和设备,包括信息和通信技术设备)细则 [Income Tax (Accelerated Capital Allowance) (Machinery and Equipment including Information and Communication Technology Equipment) Rules 2021]

    5. 这个细则主要说的是:

    👉 在 1.3.2020 – 31.12.2021 这段时间购买的资产 [Assets]

    👉 除了车辆 [Motor Vehicles]

    👉 将享有加速资本津贴

    6. 符合上述 (5)资格的这些资产,将享有: 👉 Initial Allowance – 20% ;及

    👉 Annual Allowance – 40%

    7. 在这种情况下,两年就完全 Claim 完所有的 Capital Allowance

    8. Hire purchase 方式买的资产,只有本金的支付才享有资本津贴

    9. 细则也为 信息和通信技术设备 (Information and Communication Technology Equipment) 给与列明

    8