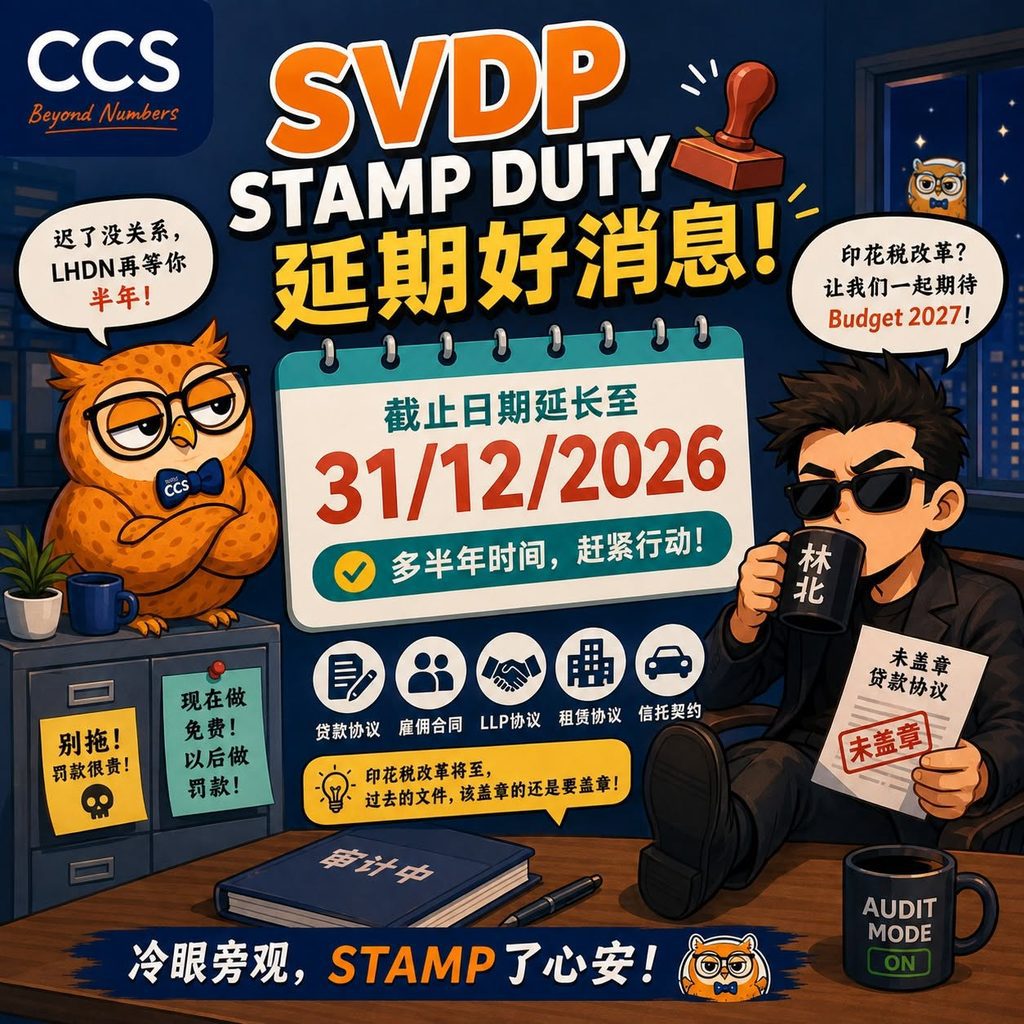
The Stamp Duty Voluntary Disclosure Programme (SVDP) deadline has been extended from 30 June 2026 to 31 December 2026.
This is certainly good news—but it should not be misunderstood as an invitation to delay.
The extension gives businesses an additional six months to regularise documents that should have been stamped but were not. In simple terms, documents stamped now may enjoy a waiver of penalties under the SVDP, while documents dealt with later may be subject to penalties.
It is similar to a parent calling you for dinner several times while you continue playing games. The extra time may seem helpful, but it does not mean the task can be postponed indefinitely.
What Is the SVDP?
The SVDP provides an opportunity to stamp overdue documents without incurring the applicable penalty.
It applies to documents that should have been stamped during the period from 1 January 2023 to 31 December 2025 but remain unstamped.
In practical terms:
- Complete the stamping process now, and the penalty may be waived under the SVDP.
- Wait until later, and penalties may apply.
The choice is yours—but waiting until the last minute may result in unnecessary costs. A fine large enough to cover several fine-dining meals is certainly not a pleasant surprise.
Five Common Types of Documents That May Require Stamping
1. Intra-group Loan Agreements
Loans between related companies should be supported by a proper written loan agreement and stamped accordingly.
The agreement should clearly state:
- Who is lending to whom;
- The date of the loan;
- The loan amount;
- The applicable interest rate; and
- How the interest will be charged or collected.
Without proper documentation, the explanation that “it was only agreed verbally” may not be sufficient. More importantly, the interest expense may not be accepted as a tax deduction.
2. Employment Contracts
On 7 August 2026, LHDN issued a new rule stating that employment contracts for employees earning a monthly salary of not more than RM3,000 do not need to be stamped.
For employees earning more than RM3,000 per month, only the principal employment contract needs to be stamped. Ancillary documents do not need to be stamped again.
This is welcome news for HR teams. However, it does not mean that employment documentation is no longer necessary. It simply means that fewer documents need to be stamped.
In other words, the paperwork may be reduced, but the work itself still needs to be done.
3. LLP Agreements
If an LLP pays remuneration to its partners and intends to claim the remuneration as a tax deduction, there should be a formal and duly stamped LLP agreement.
The agreement should state that the relevant partner is entitled to receive remuneration. It is not necessary to state the exact amount, as LHDN accepts the agreement without a specific figure.
However, if a new partner is admitted or the remuneration is subsequently revised, a supplementary agreement should be prepared and stamped as well.
There is another important point. LHDN has stated that even if the remuneration is not deductible at the LLP level, the partner may still be taxed on the remuneration received.
In short, it is not possible to enjoy the benefits on both sides while avoiding the tax implications.
4. Tenancy Agreements
Many businesses assume that a verbal agreement or a simple written document is sufficient for their tenancy arrangements.
From a tax perspective, however, rental expenses may not be deductible without a valid and stamped tenancy agreement.
Businesses should also take note of the following:
- Renew the agreement even if the previous agreement has expired;
- Do not overlook the need to regularise overdue documentation; and
- Ensure that the tenant stated in the agreement is the company, rather than the director personally.
If the director’s name is stated as the tenant, LHDN may regard the expense as a personal expense and disallow the deduction.
That can become a difficult issue to resolve later.
5. Trust Deeds
Some business owners place vehicles registered in their personal names into the business, with the company making the instalment payments and paying for maintenance.
However, this arrangement is not achieved simply by transferring the use or responsibility for the vehicle to the company. It may involve a Trust Deed, which is a document that requires stamping.
A vehicle being used by the company does not automatically mean that the arrangement will be accepted for tax purposes. If the relevant documentation is not properly prepared, LHDN may still refuse to recognise the arrangement.
It is like placing money in a safe but losing the key: the asset may exist, but it may not be accessible when needed.
The Extension Is an Opportunity, Not a Reason to Delay
Overall, the extension of the SVDP deadline to 31 December 2026 is a positive development. It gives businesses another opportunity to review their records, identify unstamped documents and regularise them.
However, businesses should act promptly instead of waiting until LHDN comes knocking.
At the NTC 2026 conference, an LHDN officer indicated that significant reforms to the stamp duty legislation are expected, with the overall system likely to become more streamlined.
Nevertheless, documents from the past that should have been stamped must still be stamped. Waiting for future reforms is not a solution, because an audit will not wait for the reforms to be completed.
The details of what will change, when the changes will take effect and how they will be implemented remain to be seen. Let us look forward to the announcement of Budget 2027.
In the meantime, take care of the unstamped documents first.
Stamping your documents today can provide greater peace of mind tomorrow. Most importantly, remember the deadline.
印花税自愿披露计划延长至2026年12月31日:企业应把握期限及时处理
印花税自愿披露计划(Stamp Duty Voluntary Disclosure Programme,简称 SVDP)的截止日期,已从2026年6月30日延长至2026年12月31日。
这当然是一个好消息,但企业不应把这项延长期限理解为可以继续拖延的理由。
这次延期为企业多提供六个月的时间,以处理原本应当缴纳印花税但尚未盖章的文件。简单来说,在 SVDP 期限内处理相关文件,罚款可能获得豁免;如果继续拖延到之后才处理,则可能需要面对罚款。
这就像妈妈叫你吃饭,叫了五次,你却还在继续打游戏。多给你一点时间,确实是好事,但并不代表你可以无限期拖下去。
什么是 SVDP?
SVDP 为企业提供一个补盖逾期文件印花税的机会,并豁免相关罚款。
这项计划适用于在2023年1月1日至2025年12月31日期间本来应该盖章,但至今仍未盖章的文件。
实际情况可以简单理解为:
- 现在处理盖章手续,相关罚款可能在 SVDP 下获得豁免;
- 继续拖延到之后才处理,则可能面对罚款。
选择权在你手上,但等到最后一分钟才处理,可能会带来不必要的成本。一笔足以支付几餐 fine dining 的罚款,显然不会是令人愉快的惊喜。
五类常见的印花税文件
1. 关联公司之间的贷款协议
关联公司之间的借款,应当有一份正式的书面贷款协议,并按照规定完成盖章。
协议应清楚列明:
- 谁借钱给谁;
- 借款日期;
- 借款金额;
- 利率;以及
- 利息如何收取。
如果没有完整的文件记录,只说“当时只是口头讲好”,未必能够获得接受。更重要的是,相关利息支出可能无法获得税务扣除。
2. 雇佣合同
LHDN 于2026年8月7日发布新规则,规定月薪不超过 RM3,000 的雇佣合同无需盖章。
对于月薪超过 RM3,000 的员工,只需要为主要雇佣合同盖章,附属文件则无需再次盖章。
这对 HR 团队来说无疑是一个好消息。不过,这并不代表雇佣文件不需要准备,而只是需要盖章的文件减少了。
换句话说,文件工作可能少了一些,但该完成的工作仍然必须完成。
3. LLP 协议
如果 LLP 向合伙人支付薪酬,并希望将该笔薪酬作为税务扣除,则应当准备一份正式且已经盖章的 LLP 协议。
协议应清楚说明相关合伙人有权获得薪酬。协议不一定需要写明确切金额,LHDN 接受没有列出具体金额的安排。
不过,如果之后加入新合伙人,或调整合伙人的薪酬,就需要准备 supplementary agreement,并同样完成盖章手续。
还有一点非常重要。LHDN 已经说明,即使有关薪酬不能在 LLP 层面获得税务扣除,合伙人收到的薪酬仍然可能需要被征税。
简单来说,不能一边享有两方面的好处,一边又完全避开税务影响。
4. 租赁协议
许多企业以为,口头协议或简单写在一张纸上的安排就已经足够。
但从税务角度来看,如果没有有效且已经盖章的租赁协议,相关租金支出可能无法获得税务扣除。
企业也应特别注意以下事项:
- 即使原有协议已经逾期,也应及时续签;
- 不要忽略处理逾期文件的需要;以及
- 确保租赁协议中的 tenant 栏目填写的是公司名称,而不是董事个人的名字。
如果租户写的是董事个人的名字,LHDN 可能会将有关支出视为个人开支,并拒绝相关税务扣除。
到了那个时候,处理起来就会非常棘手。
5. 信托契约
有些老板会把登记在自己名下的车辆“放进”公司,由公司负责供车及支付维修保养费用。
不过,这项安排并不是把车辆交给公司使用就完成了。有关安排可能涉及 Trust Deed,而 Trust Deed 是需要盖章的文件。
车辆由公司使用,并不代表相关安排自然会被税务机关接受。如果文件没有妥善准备,LHDN 仍然可能不承认有关安排。
这就像把钱放进保险箱,却把钥匙弄丢了:资产可能还在,但需要使用时却无法取出。
延期是机会,不是继续拖延的理由
整体而言,SVDP 延长至2026年12月31日,是一项对企业有利的安排。企业可以借此重新检查记录,找出尚未盖章的文件,并及时完成补盖手续。
不过,企业应尽快行动,而不是等到 LHDN 上门“喝茶”时才开始询问该怎么办。
LHDN 官员曾在 NTC 2026 会议上透露,印花税税法预计将进行重大改革,整体制度也可能进一步简化。
但无论未来如何改革,过去应该盖章的文件,仍然需要完成盖章手续。不要等到改革后才处理,因为审计不会等到改革完成之后才开始。
至于会改什么、几时改,以及具体如何落实,目前仍有待进一步公布。让我们一起期待 Budget 2027 的宣布。
不过在那之前,请先把手上尚未盖章的文件处理好。
今天完成盖章,明天才能更加安心。最重要的是,记得截止日期。