Financial statements should not only reflect the past. They should also provide users with relevant information about important events occurring after the reporting period.
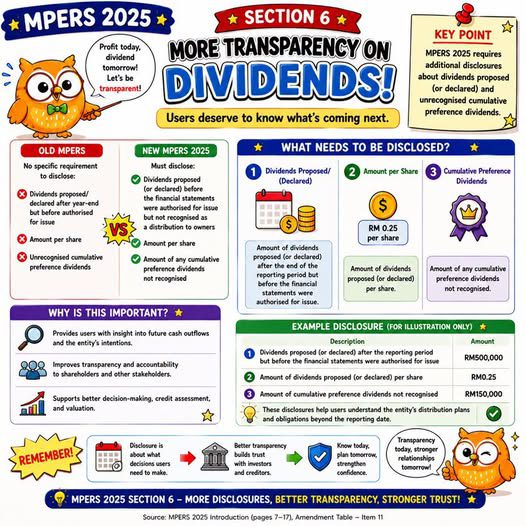
MPERS 2025 Section 6 enhances dividend disclosures by requiring information about:
- Dividends proposed or declared after the reporting date;
- Dividend amounts per share; and
- Unrecognised cumulative preference dividends.
These disclosures help shareholders, investors and creditors understand the company’s potential future cash commitments and dividend distribution plans.
Greater transparency supports better decision-making, strengthens trust and makes financial reporting more meaningful.
Financial reporting should not stop at the year-end balance. Important post-reporting-date information also matters.
CCS | Beyond Numbers
MPERS 2025 第 6 节:股息披露与报告期后事项
财务报表不应只反映过去,也应向使用者提供报告期后发生的重要事项及其相关信息。
MPERS 2025 第 6 节强化了股息披露要求,企业需要披露:
- 报告日后建议或宣派的股息;
- 每股股息金额;以及
- 尚未确认的累积优先股股息。
这些披露有助于股东、投资者及债权人了解企业未来可能承担的现金流出,以及利润分配计划。
更高的透明度能够支持更好的决策、增强信任,并让财务报告更具实际价值。
财务报告不应在年结日就停止。报告期后的重要资料同样值得关注。
CCS | Beyond Numbers