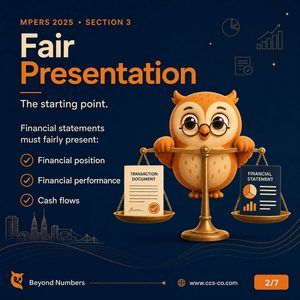
For Malaysian private entities, the starting point for proper financial statement presentation is fair presentation.
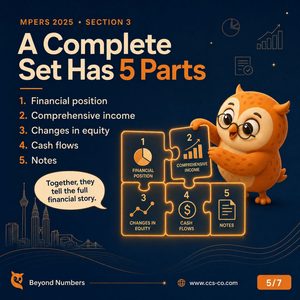
Financial statements should faithfully present the entity’s:
- Financial position;
- Financial performance; and
- Cash flows.
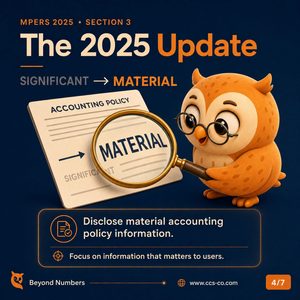
Section 3 also reinforces an important 2025 update: entities should disclose material accounting policy information, rather than merely listing accounting policies that appear significant.
This means that the focus should be on whether the accounting policy information is relevant and material to users’ understanding of the financial statements.
The revised MPERS 2025 is effective for annual periods beginning on or after 1 January 2027, with early application permitted.
Private entities should review their financial statement presentation and accounting policy disclosures before the revised requirements take effect.
Fair presentation is not only about preparing correct figures. It is also about providing information that helps users understand the entity’s financial position, performance and cash flows.
This article is a general information summary. Businesses should refer to the full MPERS 2025 requirements and assess their individual circumstances where appropriate.
CCS | Beyond Numbers
MPERS 2025 第 3 节:公允列报与重要会计政策信息
对于马来西亚私人实体而言,正确列报财务报表的基础是公允列报(Fair Presentation)。
财务报表应当如实反映企业的:
- 财务状况;
- 财务表现;以及
- 现金流量。
Section 3 也加强了 2025 年的一项重要更新:企业应披露重要会计政策信息(Material Accounting Policy Information),而不是只是罗列看起来较为重要的会计政策。
这表示,企业应关注相关会计政策信息是否对财务报表使用者理解财务资料具有相关性及重要性。
修订后的 MPERS 2025 适用于 2027 年 1 月 1 日或之后开始的年度期间,企业也可以选择提早采用。
私人实体应在修订要求生效前,检讨财务报表的列报方式及会计政策披露内容。
公允列报不只是把数字做对,也包括提供有助于使用者了解企业财务状况、财务表现及现金流量的信息。
本文仅作一般资讯用途。企业应参考 MPERS 2025 的完整要求,并在适当情况下根据自身情况进行评估。
CCS | Beyond Numbers