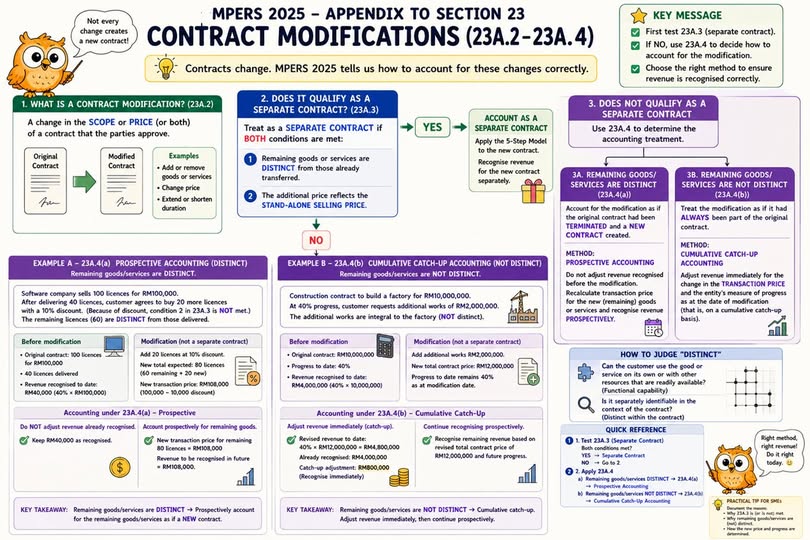
Not every contract modification creates a new contract.
Under MPERS 2025 Section 23A.2 to 23A.4, businesses must carefully assess the nature of a contract modification before determining the appropriate revenue recognition treatment.
The key questions are:
- Are the remaining goods or services distinct; and
- Does the revised price reflect the stand-alone selling price?
The answer to these questions determines how the contract modification should be accounted for.
A contract modification may require prospective accounting or cumulative catch-up accounting, depending on the circumstances and the nature of the remaining goods or services.
An incorrect assessment may result in revenue being recognised in the wrong period. This can affect reported profits, financial statements and audit conclusions.
Understanding the difference between prospective accounting and cumulative catch-up accounting helps businesses recognise revenue accurately and consistently throughout the life of a contract.
CCS | Beyond Numbers
MPERS 2025 第 23A 节:合同修改的会计处理
并非每一次合同变更,都等于一份新合同。
根据 MPERS 2025 第 23A.2 至第 23A.4 段,企业在确定收入确认处理方式之前,必须先仔细评估合同修改的性质。
关键问题包括:
- 剩余的商品或服务是否属于独立履约义务(Distinct);以及
- 修改后的价格是否反映单独售价(Stand-alone Selling Price)?
这些问题的答案,将决定企业应如何对合同修改进行会计处理。
根据实际情况及剩余商品或服务的性质,合同修改可能需要采用未来适用法(Prospective Accounting),或进行累计追溯调整(Cumulative Catch-up Accounting)。
如果判断错误,企业可能会在错误的期间确认收入,进而影响利润、财务报表及审计结论。
理解未来适用法与累计追溯调整法之间的区别,有助于企业在整个合同期间准确、一致地确认收入,并符合 MPERS 2025 的要求。
CCS | Beyond Numbers